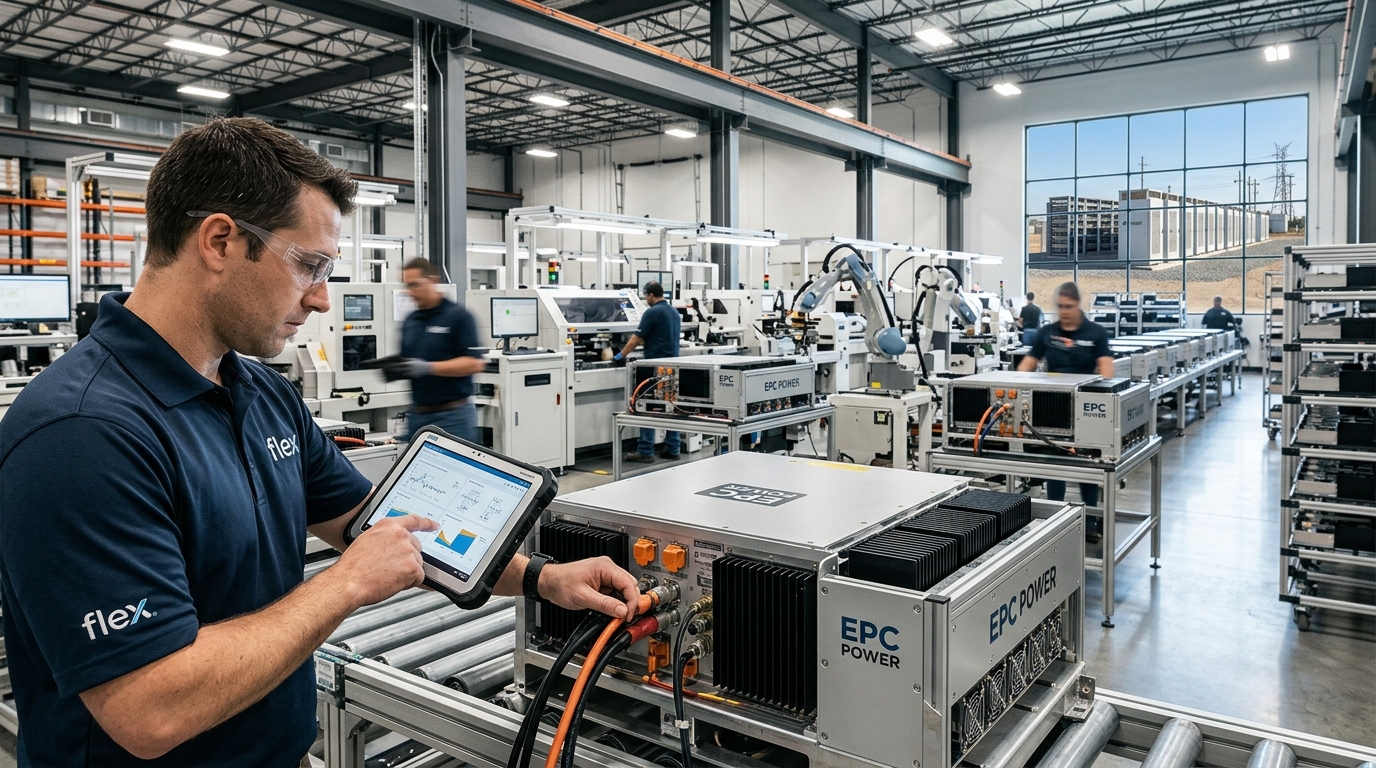
Flex is not a company you typically associate with bold, binary bets. It is a major contract manufacturer, a disciplined executor that assembles complex products for other people’s brands across roughly 30 countries. Then September 3, 2026 happened.
Flex announced a definitive agreement to acquire EPC Power at a value of $4.4 billion, subject to customary adjustments. EPC Power designs and builds power conversion systems for battery storage, grid, and data-center applications. That is, in plain terms, the hardware that bridges a utility line and the rack holding a GPU cluster. Flex just decided that hardware is worth a 5.5x revenue multiple.
The Business
Founded in 2010 and headquartered in California, EPC Power is a leading provider of intelligent power conversion solutions for data center and grid applications, combining internally developed hardware, software, and controls with U.S.-based engineering and manufacturing. The company delivers 800V power conversion today and is building toward solid-state transformers. That 800V architecture matters: it is the emerging data-center power architecture Flex is explicitly positioning around for increasingly power-intensive AI computing facilities.
EPC Power has deployed more than 15 GW across 62 countries and says its annual U.S. manufacturing capacity will surpass 30 GW in 2027. That is an operational footprint with real pricing leverage, not a startup with a prototype.
Why Wall Street Is Paying Attention
The deal lands inside a larger structural story. The acquisition will place EPC Power within Flex’s Cloud and Power Infrastructure business, which Flex plans to separate into an independent publicly traded company in the first quarter of 2027. The new entity, referred to as SpinCo, is positioned by Flex as a critical digital and electrical infrastructure company targeting end-to-end power and thermal management technologies for AI data centers, from grid to chip.
Flex is essentially fattening SpinCo before the separation. Flex anticipates that EPC Power will achieve around 40% organic revenue growth in 2027, accompanied by double-digit margin expansion, which could drive its EBITDA margin toward 30%. Flex has also said it is targeting SpinCo to generate approximately 65% to 75% revenue growth in fiscal 2027, with an acceleration to 80%+ in fiscal 2028. That is not contract manufacturing math. That is pure infrastructure-software-adjacent growth, and investors currently holding FLEX get a claim on it.
FLEX shares are around $109.51 as of September 5, 2026. Based on 8 Wall Street analysts, the average 12-month price target sits at $157.14. The gap suggests analysts think the re-rating has further to run, particularly once SpinCo files its Form 10 and the market can value the two businesses independently.
What’s Driving the Opportunity
The purchase lands as U.S. electricity demand rises after years of relatively flat consumption, driven by data centers, electrification, and new manufacturing. EPC Power’s Agile Grid Forming solutions are designed to enhance on-site energy storage, microgrids, and grid-support configurations, making EPC Power useful to both hyperscalers and utilities simultaneously. That dual-market positioning is rare and reduces customer concentration risk considerably.
The spinoff is targeted to close in the first quarter of 2027 and is intended to be structured to be tax-free for shareholders. Flex shareholders would receive SpinCo shares without a tax event if it is completed on those intended terms. The clock is short: roughly two quarters to go.
What Could Go Wrong
The multiple is the most direct concern. Paying 5.5x forward revenue for an industrial power electronics company requires EPC Power to actually deliver its growth projections, which assume rapid data-center demand and continued U.S. manufacturing expansion. Either could slow. Flex has said it expects to fund the $4.4 billion purchase through a combination of debt and equity, which means leverage increases at the consolidated level before the separation closes. Integration on a tight timeline is aggressive. Execution risk is real.
There is also the separation itself. Actual value creation will depend on execution, spin-off costs, and post-transaction customer and supplier dynamics. SpinCo’s post-separation valuation will not be determined by Flex’s intentions. It will be determined by what the market assigns on day one of independent trading.
The Bottom Line
Flex is making a concentrated argument: that the most valuable thing it owns is the infrastructure between the grid and the GPU, and that owning it inside a contract-manufacturing conglomerate permanently suppresses its multiple. Adding EPC Power’s 800V conversion platform and roughly $800 million in expected 2026 revenue ahead of the SpinCo separation is not diversification. It is deliberate pre-IPO asset assembly. If the separation executes cleanly and SpinCo earns a pure-play infrastructure multiple, current FLEX holders will have bought a premium power infrastructure company at a discount. The window for that trade closes in Q1 2027.