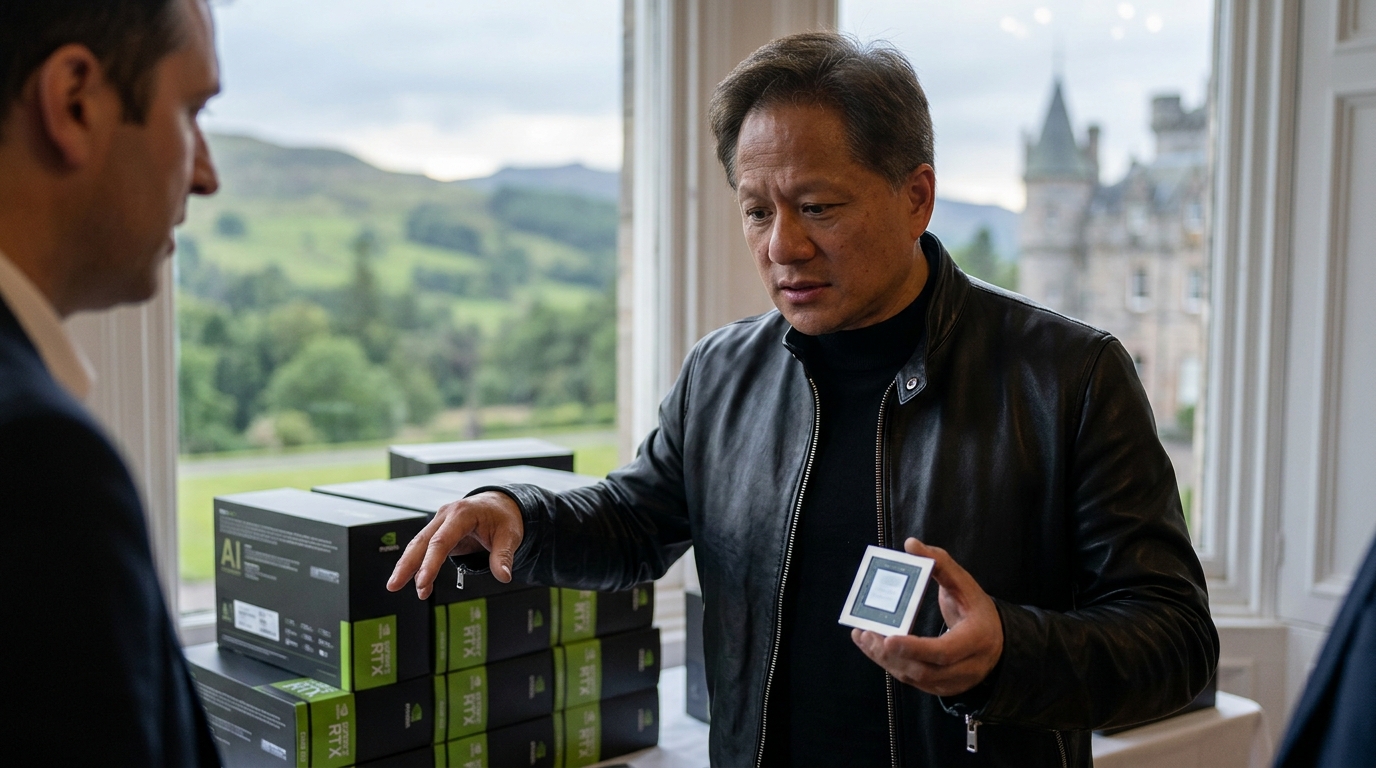
Jensen Huang spent last week telling anyone who would listen that Nvidia will sell twice as many chips next year as it does today. “I expect Nvidia to sell twice as many chips this next year as we do this year,” Huang said on the sidelines of an AI summit hosted by King Charles III in Scotland. The stock moved up. Then it kept trading at a valuation that would embarrass a regional bank.
At under 19 times profit expected over the next 12 months, Nvidia shares are trading near the cheapest level in more than a decade. The multiple is far below what the stock commanded in 2025, and down sharply from earlier this year. So which is it: a decade-low valuation on a business doubling its chip volumes, or a market telling you something the bulls haven’t priced in?
The Bull Case
Nvidia’s revenue and net income are expected to jump sharply in fiscal 2027, which ends in January. In its second-quarter earnings report in late August, Nvidia projected that sales would expand about 70% in fiscal 2028, well above what had been expected. That is not a company running out of road.
There is an important distinction between selling twice as many chips and doubling revenue. Nvidia does not disclose its total chip shipments, and its products vary widely in price. But the volume commitment reflects real demand. Early positive performance from Meta’s new AI agent has improved market expectations for AI chip demand, driving the Philadelphia Semiconductor Index up 4.3% on Monday, its biggest single-day gain since August 4. Paying under 19 times for that kind of growth trajectory is the kind of valuation that, in retrospect, looks obvious.
The Bear Case
The semiconductor index has surged almost 76% in 2026. That move was led by memory chipmaker Micron and Nvidia rivals Intel and AMD, which have each gained more than 180%. Nvidia is among the laggards in the index, which itself trades at around 20 times estimated profit. Nvidia is cheaper than the index it anchors. That is not a compliment.
Market strategists point to tightening margins and rising competition as core drivers of the stock’s valuation discount. While Nvidia reported roughly a 75% gross margin in the second quarter, the company has indicated it expects margins to bottom in Q4 in the 71% to 72% range before settling lower than the recent peak in fiscal 2028.
The deeper threat is structural. Google’s TPU v7, Amazon’s Trainium 3, Microsoft’s Maia 2, and Meta’s MTIA 2 all ramped into volume production from 2025 to 2026. Combined hyperscaler custom silicon deployment is estimated at approximately 1.9 million accelerators in 2026, gradually reducing Nvidia’s share of total data center AI accelerator deployment. Meanwhile, AMD has accelerated its AI product launches and moved beyond selling individual chips to offering complete systems combining processors, networking gear and related hardware, positioning itself as the closest U.S. rival to Nvidia in AI accelerators. As one Seaport analyst put it, hyperscalers are pursuing custom silicon because they don’t want to be stuck behind an Nvidia monopoly, and the high cost of Nvidia’s AI chips has meant cloud providers make lower profits renting out those chips than they could renting their own.
Where the Evidence Leads
“The stock has de-rated pretty significantly, which suggests a healthy dose of skepticism that the company’s current earnings power is sustainable,” said Eli Horton, senior portfolio manager at TCW. “The stock’s performance is surprising, given the backdrop of incredible fundamentals, but it tells you the market is expecting less than what the consensus is currently estimating.”
That is the crux. Horton noted that Nvidia’s current valuation already reflects some expectation of an AI capex slowdown. The bull case does not require believing growth will reaccelerate from here, it only requires that the consensus numbers prove roughly correct. The bear case requires something more specific: that AMD, custom ASICs, and softening margins erode earnings faster than the revenue line grows.
What Could Shift the Debate
While custom chips may be cheaper to use, AI developers often prefer Nvidia’s chips because of the software stack that goes with them. CUDA remains the stickiest moat in semiconductors. If that holds, the under-19-times multiple looks like a gift. If hyperscaler custom silicon scales from 1.9 million units toward the volumes Nvidia ships, the earnings estimates supporting that under-19-times look fragile.
Watch gross margins in Q4. Watch AMD’s MI450 ramp. And watch whether Microsoft and Meta start reducing GPU orders rather than just supplementing them with in-house designs. Those are the data points that will answer which side of this debate the evidence actually supports.
Verdict
The valuation compression is real, and it is warranted as a reflection of uncertainty, not as a signal of permanent impairment. Nvidia’s earnings trajectory over the next six quarters is strong enough that the bull case carries slightly more weight today. But the market is not wrong to discount it. This is a stock where the difference between cheap and cheap-for-a-reason will be decided by margin data and competitive order flow, not by Jensen Huang’s confidence at a Scottish summit.