Skip to content
Bull Bear Daily

Bull Bear Daily

Primary Menu
  • Home
  • Business
  • Domestic
  • Economy
  • Money
  • Politics
  • Top News
  • Newsletters
  • Home
  • 2026
  • September
  • 12
  • Chipotle’s Beef Bill Is What Investors Actually Need to Price In
  • Economy

Chipotle’s Beef Bill Is What Investors Actually Need to Price In

The cyclospora cloud has lifted. What remains is a margin squeeze that a 1-2% menu price increase may not fully fix.
Bull Bear Daily September 12, 2026 3 minutes read
aae80687-f970-41a2-8d22-fffd485210d9

On September 11, the CDC declared the multistate cyclospora outbreak linked to iceberg lettuce over. Restaurant stocks, Chipotle included, bounced on the news. That relief is real. The food-safety overhang that had rattled dining rooms since July is gone. But for CMG shareholders, clearing one headwind simply puts the underlying cost problem in sharper focus.

During the Q2 earnings call, CFO Adam Rymer noted a softening of roughly 200 basis points in traffic trends tied to the cyclospora issue affecting the industry. Now that drag is fading. What stays is beef.

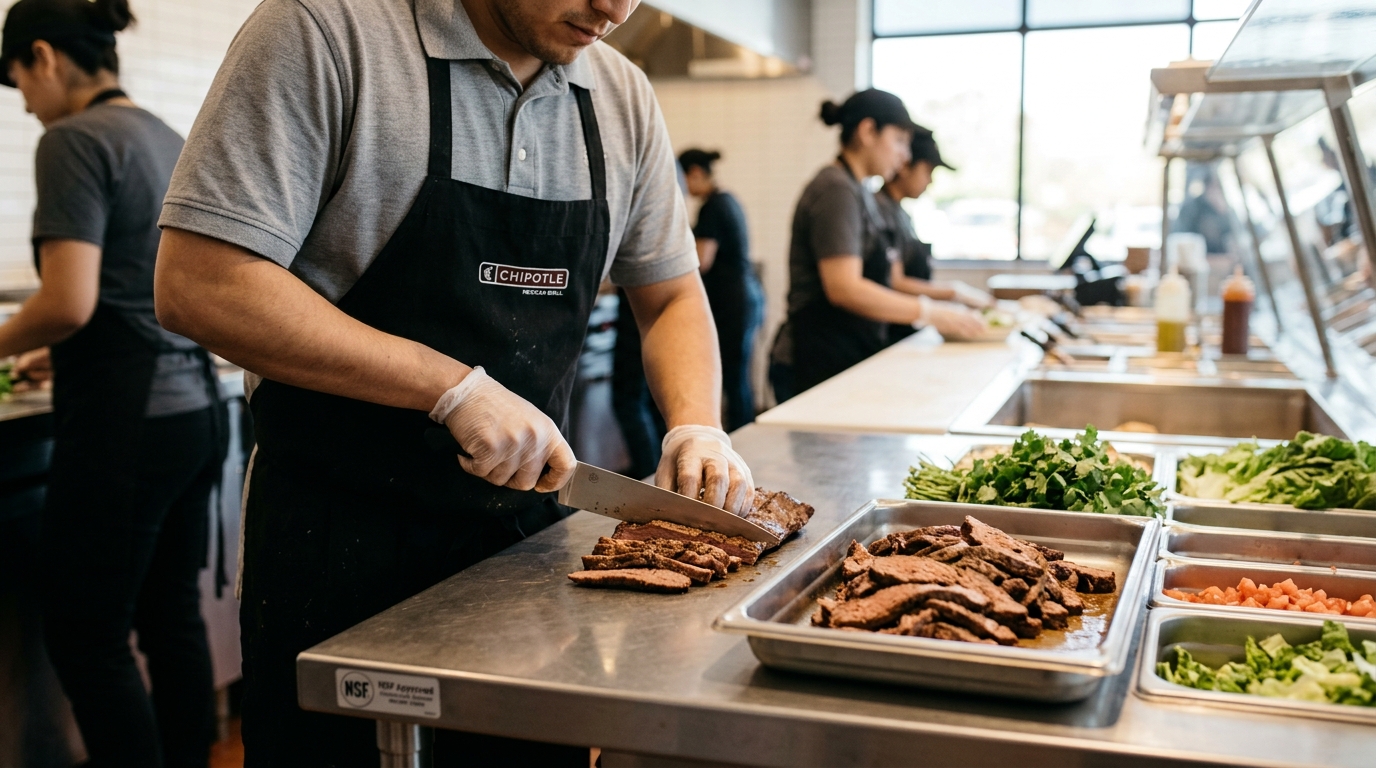
Food, beverage, and packaging costs in Q2 2026 hit 29.7% of total revenue, up from 28.9% a year earlier, driven primarily by inflation in beef and freight. Restaurant-level margin fell 220 basis points year-over-year to 25.2%, weighed down by higher labor, marketing, and other operating costs. Those are not small moves for a company whose premium valuation rests on expanding margins, not compressing them.

Management’s answer is measured: pass some of it on. CFO Adam Rymer told investors that margins in 2026 would be under pressure and that the company planned 1% to 2% menu price increases, which is modest relative to where the company pegged industry pricing. That increment is modest relative to the cost gap. For Q3, management projected inflation running near 3% against pricing in the mid-2% range, a combination that could keep pressing margins.

The confidence behind those price increases comes from a deliberate customer segmentation. CEO Scott Boatwright said internal research shows roughly 60% of Chipotle’s core customers earn more than $100,000 annually, a finding that has given executives confidence to lean into that group even as some lower-income diners pull back.

The comps tell a more cautious version of that story. Q2 comparable sales grew 2.2%, comprising a 1.2% increase in average check and a 1.0% gain in transactions. Management guided full-year comp sales growth to the low single-digit range, citing cautious consumer behavior and industry headwinds. Low single digits on a 33-times-earnings stock is a narrow margin for error.

The Real Question at This Valuation

Chipotle’s trailing price-to-earnings ratio stood near 34 in late August. Measured against that history, CMG looks compressed. But measured against the current growth rate, 33-to-34 times earnings still prices in a recovery that has not arrived yet.

The cyclospora episode will not appear in the full-year results as a lasting scar. Federal health officials described nearly 13,000 reported cyclospora cases tied to the multistate outbreak in 21 states, concentrated in a summer window that is now closed. What the episode did was delay an honest accounting of what CMG is worth when beef costs stay elevated and comp growth runs in the low single digits.

Long-term investors who believe Chipotle’s brand and unit economics are durable have a genuine argument. Rewards enrollment reached nearly 23 million active members, with daily sign-ups running nearly 20% higher since the April relaunch. The customer relationship is intact. The company’s innovation pipeline for the second half of 2026 includes additional limited-time protein options and more meaningful beverage innovation. These are real assets.

The wealth-building lesson here is not whether Chipotle is a good business. It clearly is. The question is the price you pay for patience. At current levels, CMG is not obviously cheap. Investors willing to own it through a beef-cost cycle at 33 times earnings are making a quality bet, not a bargain one. That is a legitimate strategy, but it requires knowing exactly what you are holding while you wait for margins to recover.
Post navigation

Previous: Hold onto your nuts… and bolts (Invest by 9/17)
Next: Google Is Buying Nuclear Power for 22 Years

Related Stories

9b99d1c7-7c2b-4000-a463-0d69087fb4dc
  • Economy

The Yen Is Up Three Days Running. Who Is Still Short?

Bull Bear Daily October 30, 2026
f490eb94-e6c1-463d-b960-b0b0d2337f40
  • Economy

Prologis Has 5.8 GW in Pipeline. Digital Realty Runs 3.1 GW.

Bull Bear Daily October 29, 2026
accba3bb-5593-4e70-9e89-f22cda39205b
  • Economy

Two Rate Decisions, One Day: What the Gilt Curve Signals

Bull Bear Daily October 28, 2026

Live Market Pulse

The charting technology is provided by TradingView. Learn how to use theTradingView Stock Screener.

Sign up for our free Bull Bear Daily Newsletter!

Discover new market trends and ideas directly to your inbox.

By providing your email, you agreed to receive informational and promotional messages from us. You may opt out at any time by clicking the unsubscribe at the bottom of each email. See our Privacy Policy for more information.

Recent Posts

  • Elon Musk’s Mission X – REVEALED
  • Lilly Beat Estimates by $1.8 Billion. The Third Raise Matters More.
  • AbbVie’s Dividend Is Growing Because Its Drugs Are Growing
  • ServiceNow Grew 21% and Still Lost a Sixth of Its Value. Who Is Right?
  • The Yen Is Up Three Days Running. Who Is Still Short?
  • promising isn’t enough
  • Lilly’s Ad War With Novo Has to Show Up in Sales Today

You may have missed

e4296cf7-7810-4e38-875c-db7593f3d4d1
  • Newsletters

Elon Musk’s Mission X – REVEALED

Bull Bear Daily October 31, 2026
7c7b0521-0eec-409e-b11d-25284c39e998
  • Business

Lilly Beat Estimates by $1.8 Billion. The Third Raise Matters More.

Bull Bear Daily October 31, 2026
c6ceb6de-2692-4232-8283-2d24091e00bb
  • Top News

AbbVie’s Dividend Is Growing Because Its Drugs Are Growing

Bull Bear Daily October 30, 2026
491d655c-b31a-4341-86bc-43f199dc8972
  • Newsletters

ServiceNow Grew 21% and Still Lost a Sixth of Its Value. Who Is Right?

Bull Bear Daily October 30, 2026
  • About Us
  • Disclaimer
  • Privacy Policy
  • Terms of Service/Use Agreement
  • Contact Us
Copyright 2026 © All rights reserved | Bull Bear Daily | bullbeardaily.com
SITE_OK
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}