Skip to content
Bull Bear Daily

Bull Bear Daily

Primary Menu
  • Home
  • Business
  • Domestic
  • Economy
  • Money
  • Politics
  • Top News
  • Newsletters
  • Home
  • 2026
  • October
  • 30
  • ServiceNow Grew 21% and Still Lost a Sixth of Its Value. Who Is Right?
  • Newsletters

ServiceNow Grew 21% and Still Lost a Sixth of Its Value. Who Is Right?

Bull Bear Daily October 30, 2026 5 minutes read
491d655c-b31a-4341-86bc-43f199dc8972

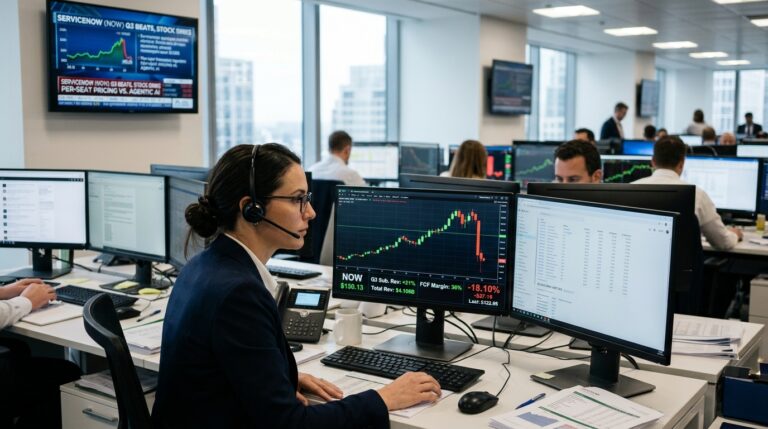
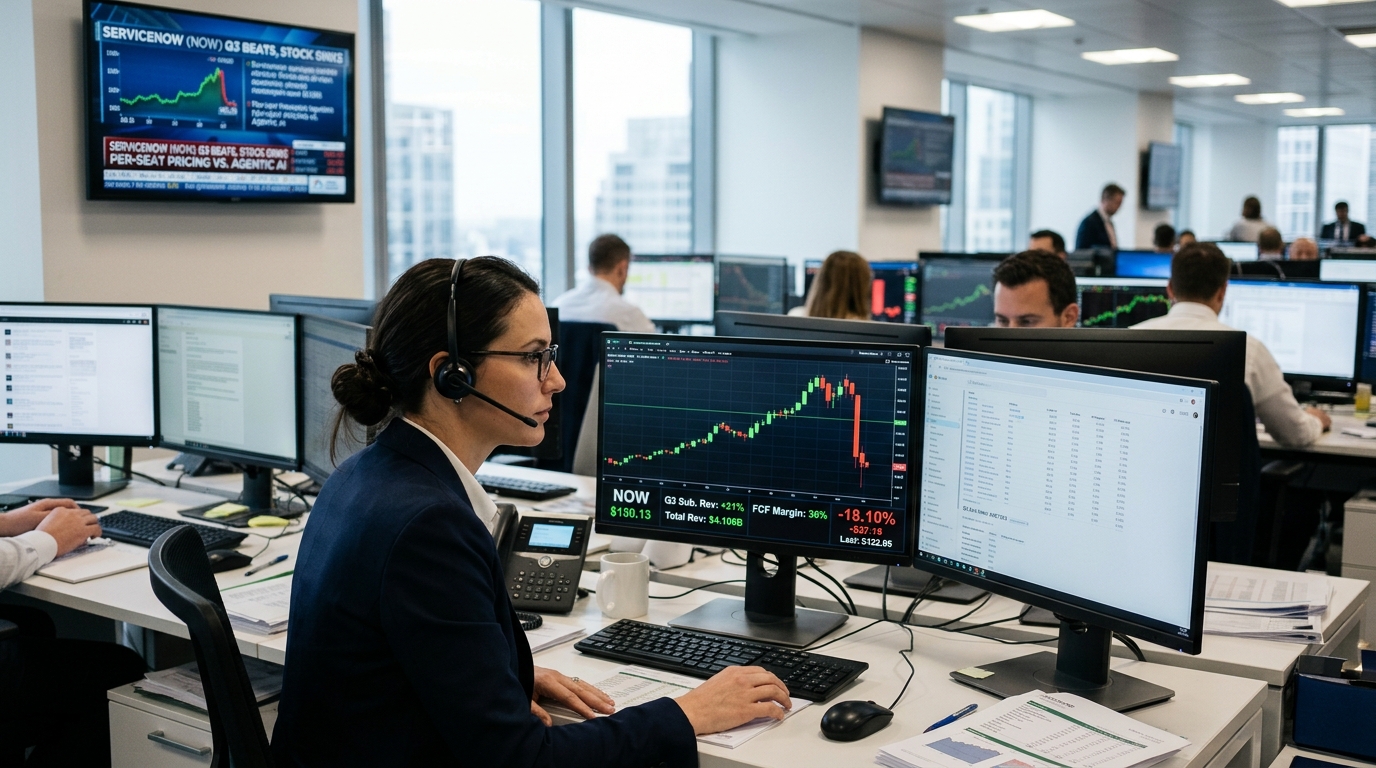
ServiceNow reported Tuesday night that subscription revenue rose 21%, total revenue hit $4.106 billion beating consensus, and management raised its full-year free cash flow margin target to 36%. Then the stock fell about 18%.

Sponsored

‘Please, Please, Please’: OpenAI CEO Sam Altman Begs Small Company for Help

As reported by Financial Times, those are the exact words OpenAI CEO Sam Altman spoke on an open line to a small company in Arapahoe County, Colorado… which now controls what could be the most important technology in the world. Altman is desperate to get his hands on it… and he’s not alone. This tech is now backed by Elon Musk, Jensen Huang, and more.

Click here to learn how you could invest in this breakthrough alongside Sam Altman and Elon Musk.

Shares closed the regular October 28 session at $150.13. After hours, the stock traded around $122.95, down $27.18 or 18.10%. By this morning, ServiceNow was trading near $122.95 with a market capitalization around $155 billion. The question investors need to answer is not whether management executed. They did. The question is whether the pricing model that built this company still works in an agentic AI world.

The Bull Case: This Is Simply a Cheap, Fast-Growing Company

The numbers are hard to dismiss. ServiceNow beat the high end of its Q3 guidance on subscription revenue, cRPO, and operating margin, with cRPO growing 21% in constant currency, 100 basis points above guidance, and operating margin reaching 32.5%, 150 basis points above guidance. The company reported a 98% renewal rate and ended the quarter with 680 customers generating more than $5 million in annual contract value, including 31 additional customers surpassing $20 million in ACV over the past year.

AI monetization is not speculative. ServiceNow raised its 2026 AI annual contract value target to $1.7 billion, up from $1 billion at the start of the year, and management reported that year-to-date agentic AI consumption in production had increased 13-fold from a year earlier. AI net new ACV rose 65% year over year.

The pricing transition ServiceNow is navigating is not unique to one vendor. Salesforce is simultaneously running three live Agentforce pricing models, reflecting how genuinely difficult it is to translate agentic work into a billing structure.

Sponsored

60,000 Americans Discovered This Affordable European Paradise

Imagine Parisian-style penthouses for just $650 a month, steak dinners with wine for $11, and a lifestyle that feels straight out of the French Riviera. More than 60,000 Americans have discovered this surprisingly affordable destination, where European luxury meets everyday prices. But it’s not where you’d expect…

Discover where Americans are living the European dream for less!

The trailing P/E ratio now stands at roughly 93 times, below a level some data services show for recent history. For a company growing revenue at 21% with a 98% renewal rate and $29.7 billion in total RPO, that contraction is not obviously deserved.

The Bear Case: Per-Seat Pricing Is Broken

The market’s verdict may be less a panic and more a structural reset. The core anxiety is straightforward: AI agents do not need seats. A seat represented an authorized human user, and seat count was a reasonable proxy for software’s organizational footprint. An AI agent’s marginal cost of additional work is near zero, meaning an agent handling 1,000 support tickets per day can handle 5,000 on the same infrastructure, while 5,000 human tickets would require 5,000 human seats.

ServiceNow has acknowledged the shift. Management has said that more than 50% of net new ACV is already coming from non-seat licenses, and that the new AI-native packaging can come with 20% to 30% average price lift. Salesforce’s Agentforce is priced at $2 per conversation, with no seat concept at all. Microsoft, whose Copilot suite runs inside the same enterprise workflows ServiceNow touches, can bundle AI capability at scale no independent vendor can match.

The earnings result itself handed bears a real number. ServiceNow’s Q4 revenue guidance range of $4.25 to $4.26 billion came in below the analyst consensus of about $4.36 billion. Q4 cRPO growth guidance of 18.5% in constant currency reflects a deceleration from Q3’s 21%, partly due to early renewals in Q3 that pulled deals forward and a higher on-premises mix. Management explained those dynamics carefully; the market did not wait for the explanation.

Sponsored

5 Stocks Built for a Strong Finish to 2026

Higher interest rates, a reshuffled Washington and a market that wants proof of AI profits will all test stocks before the year is out. These 5 companies have the earnings to handle it. Download our free report for the catalysts, recent results and analyst price targets behind each one.

Download our free Report

Where the Evidence Leads

The strongest bearish evidence is the Q4 revenue guidance gap, not the EPS miss. The company did not raise full-year subscription revenue guidance by the full Q3 beat, passing through only a portion of the outperformance. At a premium valuation, a partial pass-through reads as a signal that growth headroom is compressing, not expanding. The strongest bullish evidence is the $1.7 billion AI ACV target and the 13x consumption surge, which suggest the transition to outcome-based pricing is proceeding faster than the stock price reflects.

CEO Bill McDermott noted that more than 50% of net new business is already non-seat-based, and AI-native SKUs carry 20% to 30% average price lift, which is precisely the answer to the bear case. If that figure is real and durable, the per-seat concern dissolves. If it is aspirational, the Q4 guidance gap is the leading indicator.

What Could Change the Debate

Watch Q4 cRPO closely when ServiceNow reports in January. If the 18.5% constant-currency guidance proves conservative the way Q3 guidance did, the bull case rebuilds quickly. If it lands at or below guidance while Salesforce and Microsoft report accelerating Agentforce and Copilot consumption numbers, the structural reset deepens.

The more compelling side today, on balance, belongs to the bears, but narrowly. A two-cent EPS miss does not erase 21% subscription growth or a 98% renewal rate. What it does is remind investors that at roughly 93 times trailing earnings, ServiceNow needed a clean beat and clear acceleration. It delivered neither. The stock is not broken. The pricing model it was built on is being renegotiated in real time, and the market just sent that invoice.
Post navigation

Previous: The Yen Is Up Three Days Running. Who Is Still Short?
Next: AbbVie’s Dividend Is Growing Because Its Drugs Are Growing

Related Stories

1916b40a-52df-445e-bacb-4c4a5d77f050
  • Newsletters

promising isn’t enough

Bull Bear Daily October 30, 2026
ad9214ee-7663-4161-a3fa-a5774acfe2a6
  • Newsletters

Lilly’s Ad War With Novo Has to Show Up in Sales Today

Bull Bear Daily October 29, 2026
4cc8ebf1-ed4f-4192-9101-d7e74f94d919
  • Newsletters

Don’t lose access to this

Bull Bear Daily October 29, 2026

Live Market Pulse

The charting technology is provided by TradingView. Learn how to use theTradingView Stock Screener.

Sign up for our free Bull Bear Daily Newsletter!

Discover new market trends and ideas directly to your inbox.

By providing your email, you agreed to receive informational and promotional messages from us. You may opt out at any time by clicking the unsubscribe at the bottom of each email. See our Privacy Policy for more information.

Recent Posts

  • AbbVie’s Dividend Is Growing Because Its Drugs Are Growing
  • ServiceNow Grew 21% and Still Lost a Sixth of Its Value. Who Is Right?
  • The Yen Is Up Three Days Running. Who Is Still Short?
  • promising isn’t enough
  • Lilly’s Ad War With Novo Has to Show Up in Sales Today
  • Prologis Has 5.8 GW in Pipeline. Digital Realty Runs 3.1 GW.
  • Don’t lose access to this

You may have missed

c6ceb6de-2692-4232-8283-2d24091e00bb
  • Top News

AbbVie’s Dividend Is Growing Because Its Drugs Are Growing

Bull Bear Daily October 30, 2026
491d655c-b31a-4341-86bc-43f199dc8972
  • Newsletters

ServiceNow Grew 21% and Still Lost a Sixth of Its Value. Who Is Right?

Bull Bear Daily October 30, 2026
9b99d1c7-7c2b-4000-a463-0d69087fb4dc
  • Economy

The Yen Is Up Three Days Running. Who Is Still Short?

Bull Bear Daily October 30, 2026
1916b40a-52df-445e-bacb-4c4a5d77f050
  • Newsletters

promising isn’t enough

Bull Bear Daily October 30, 2026
  • About Us
  • Disclaimer
  • Privacy Policy
  • Terms of Service/Use Agreement
  • Contact Us
Copyright 2026 © All rights reserved | Bull Bear Daily | bullbeardaily.com
SITE_OK
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}