Everyone is talking about the square footage. Nobody is doing the machine math.
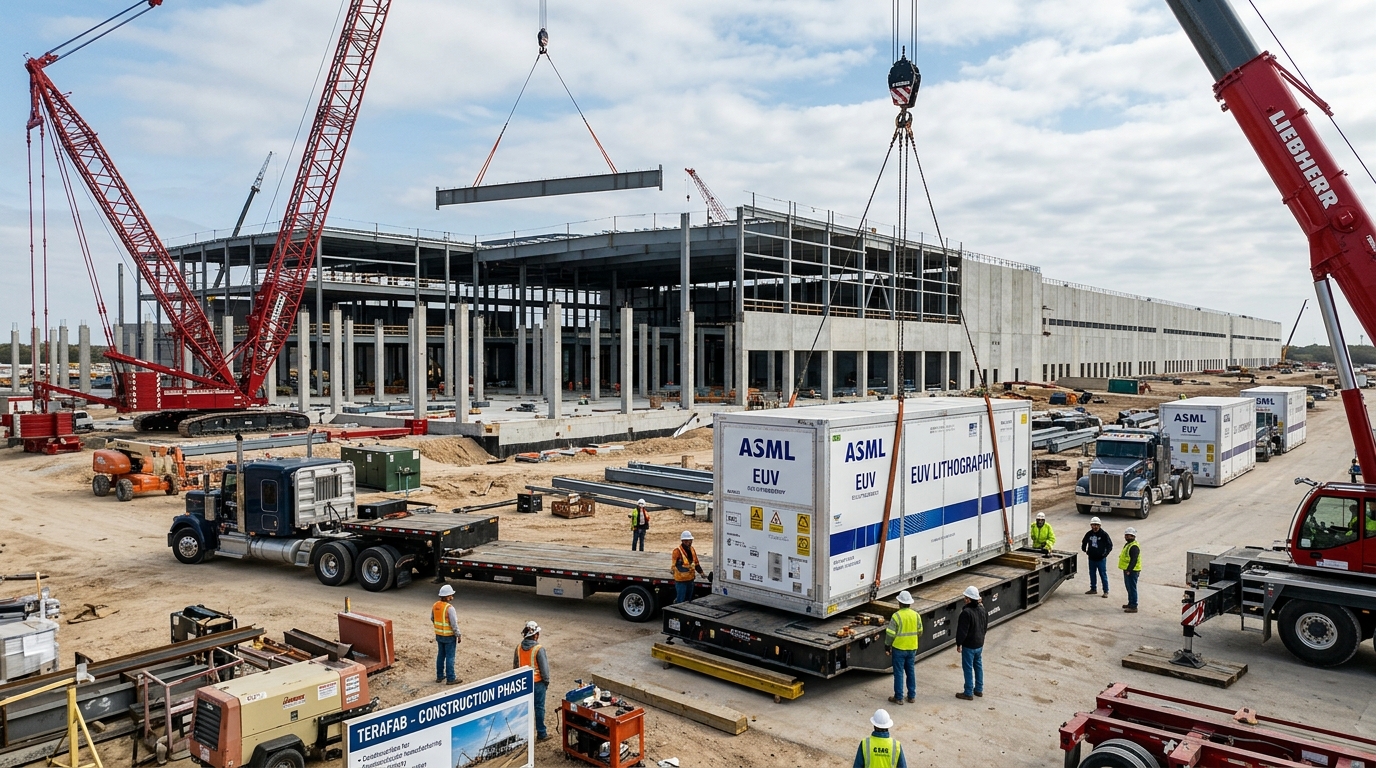
Elon Musk is betting that the next phase of his sprawling technology empire will require a building on a scale that has never existed before. SpaceX and Tesla are building TeraFab, a semiconductor manufacturing facility planned for Grimes County, Texas, that has been described in recent reporting as exceeding 100 million square feet of manufacturing space. The headlines have focused on that comparison ever since the project details surfaced publicly on August 6. The $16.8 billion figure represents only an initial investment figure discussed publicly. Beyond that, SpaceX’s May 2026 S-1 describes a general framework with timelines, milestones, and capital expenditures not yet determined.
None of that capital solves the constraint that actually governs this project’s timeline. That constraint sits in Veldhoven, Netherlands, and it ships fewer than 100 units per year.
Why This Stock Matters Now
ASML has gained meaningfully in recent months, pushing into the high end of the range that has put it among Europe’s most valuable listed companies. In its Q1 2026 results, ASML raised its full-year 2026 outlook to €36 billion to €40 billion.
The move is logical. What the market has not fully priced is just how hard ASML’s equipment ceiling makes the TeraFab ambition to execute, and what that means for ASML as a long-duration position rather than a news-driven trade.
The Investment Thesis
ASML is the sole global manufacturer of the extreme ultraviolet lithography systems that any leading-edge chip fab must have. Any serious new entrant to advanced chipmaking, TeraFab included, would need to procure billions of dollars in ASML equipment. That monopoly is not new. What is new is the scale of demand now pointed at a supplier that cannot simply be asked to double output.
Pinning a precise EUV-machine count to a hypothetical “fully ramped” TeraFab is speculative without a disclosed process mix, tool configuration, and wafer-output target. What is not speculative is ASML’s current throughput. ASML shipped 48 EUV lithography systems in all of 2025, and management has discussed output of at least 60 low-NA EUV systems in 2026 and at least 80 in 2027. The math alone illustrates the supply chain challenge: acquiring several hundred machines from a manufacturer with a current annual run rate well below 100 units is a multi-year undertaking even after an order is placed, and it competes directly with the allocation needs of existing customers.
The thesis is not that TeraFab gets built on schedule. It is that whether it does or does not, every serious dollar committed to leading-edge capacity flows through ASML first.
The Business Behind the Stock
ASML designs and manufactures the photolithography machines that transfer circuit patterns onto silicon wafers. Its EUV systems use light at a wavelength of 13.5 nanometers, generated by firing a laser at tin droplets, to enable features at leading-edge nodes. No other company has made this work at production scale. A fab at that node cannot run without ASML’s EUV tools, and ASML is the sole global supplier.
In Q1 2026, ASML reported total net sales of €8.8 billion with gross margin at 53.0% and basic EPS of €7.15. Analysts at several major banks have argued EUV capacity could rise further into the coming years, but those forecasts vary and should be treated as estimates rather than commitments. That production ramp, modest as it sounds against TeraFab’s stated ambitions, is itself a multibillion-euro revenue driver.
ASML CEO Christophe Fouquet confirmed direct talks with Musk in May, calling him “very serious” while cautioning that ASML’s supply limits are real. No equipment order has been announced. The relationship is currently a CEO-level conversation, not a purchase agreement. That gap between conversation and contract is where the investment question lives.
What’s Changing
Three things converged in the past eight weeks. First, public reporting on August 6 tied SpaceX and Tesla to a planned TeraFab project in Grimes County, Texas, with an initial investment figure of $16.8 billion and more than 100 million square feet described. Second, public reporting has cited local tax materials describing on-site power generation expectations, though the project’s final power and interconnection plan has not been disclosed in a definitive, company-filed build plan. Third, Musk has publicly linked TeraFab to scaling constraints for future products, framing the facility as part of a broader manufacturing roadmap.
That last comment matters for the stock. It signals that TeraFab is no longer a speculative whiteboard project. It is now being discussed as part of Musk’s operational bottlenecks.
The Intel piece reinforces this. SpaceX’s May 2026 S-1 states that Intel joined the project in April 2026. The same filing characterizes the collaboration as a general framework agreement, with specific projects subject to separate negotiations and approvals. Claims about precise node timelines and design-kit release dates should be treated as tentative unless confirmed by Intel’s own disclosures.
Every month of delay on the process and partner side is another month ASML’s order window stays open.
The Risks
The bull case for ASML rests partly on a TeraFab order that has not been placed. In its May 2026 S-1, SpaceX described an agreement with Tesla as a general framework for the future development of TeraFab, explicitly noting that timelines, milestones, and capital expenditures have not yet been determined and that definitive agreements may never be reached. There is a material gap between what is said publicly and what is legally committed.
The execution risk is also structural. Neither Tesla nor SpaceX has ever operated a semiconductor fabrication facility. Building a fab is among the most technically demanding manufacturing endeavors on Earth, requiring extreme contamination control, specialized supply chains, and a workforce with highly specific expertise.
For ASML specifically, export control risk is also real, and China exposure remains a topic investors watch closely. Valuation risk matters too, especially when a stock is priced for perfect execution.
And then there is the equipment timeline itself. EUV tools are allocated years out, meaning equipment procurement is a binding constraint for any new customer that has not yet placed a confirmed order.
What Investors Should Watch Next
Three signals will determine whether this thesis is playing out.
First, watch for a formal ASML equipment order tied to TeraFab. No equipment order has been announced; the relationship remains a CEO-level supply discussion. A confirmed purchase agreement would be the clearest possible signal that the project has moved from framework to execution.
Second, watch ASML’s Q2 and Q3 2026 bookings numbers. The relevant disclosed metric in ASML’s reporting is net bookings in euros. In Q4 2025, ASML reported net bookings of €13.2 billion, of which €7.4 billion was EUV. Any sustained acceleration above that level, particularly with a new, named customer in the mix, changes the multi-year revenue model meaningfully.
Third, watch the concrete Intel deliverables that would make a 14A-based plan real, including official Intel updates on node readiness and customer design enablement. If those timelines slip, every downstream schedule shifts, and every downstream schedule affects when ASML needs to deliver.
Bottom Line
TeraFab is the most ambitious manufacturing announcement in a generation. The building comparison captures the imagination. The EUV machine math is where the actual investment question lives.
The bull case is straightforward: AI capex is structurally tight, and ASML is the chokepoint. That was true before Musk put TeraFab in the public conversation, and it remains true regardless of whether TeraFab delivers on schedule or not. What the project adds is a new, extremely large, and extremely urgent source of demand aimed at the same production queue that TSMC, Samsung, and Intel are already fighting over.
A fully ramped TeraFab, as described in public commentary, would require more EUV machines than ASML ships in a single year at today’s run rate. ASML is the one player in this story whose leverage only increases as the project grows. That is not a trade on a building. It is a position on a supply constraint with a very visible new source of demand just added to the queue.