October 8, 2026
Three straight quarters of 5% gates at OCIC and OTIC raise a question: circuit breaker or warning light?
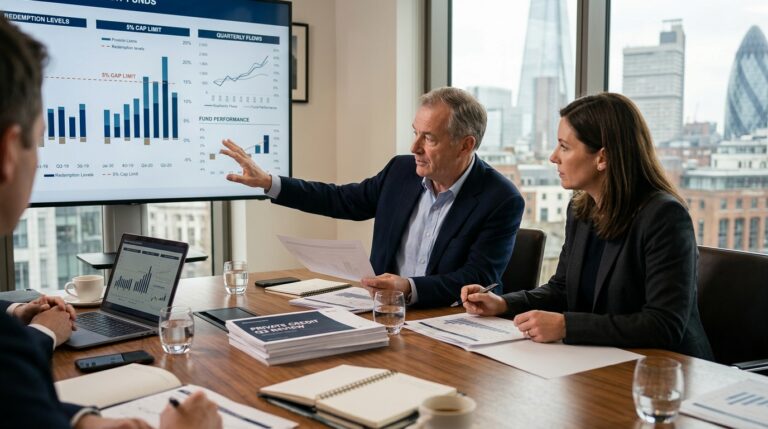
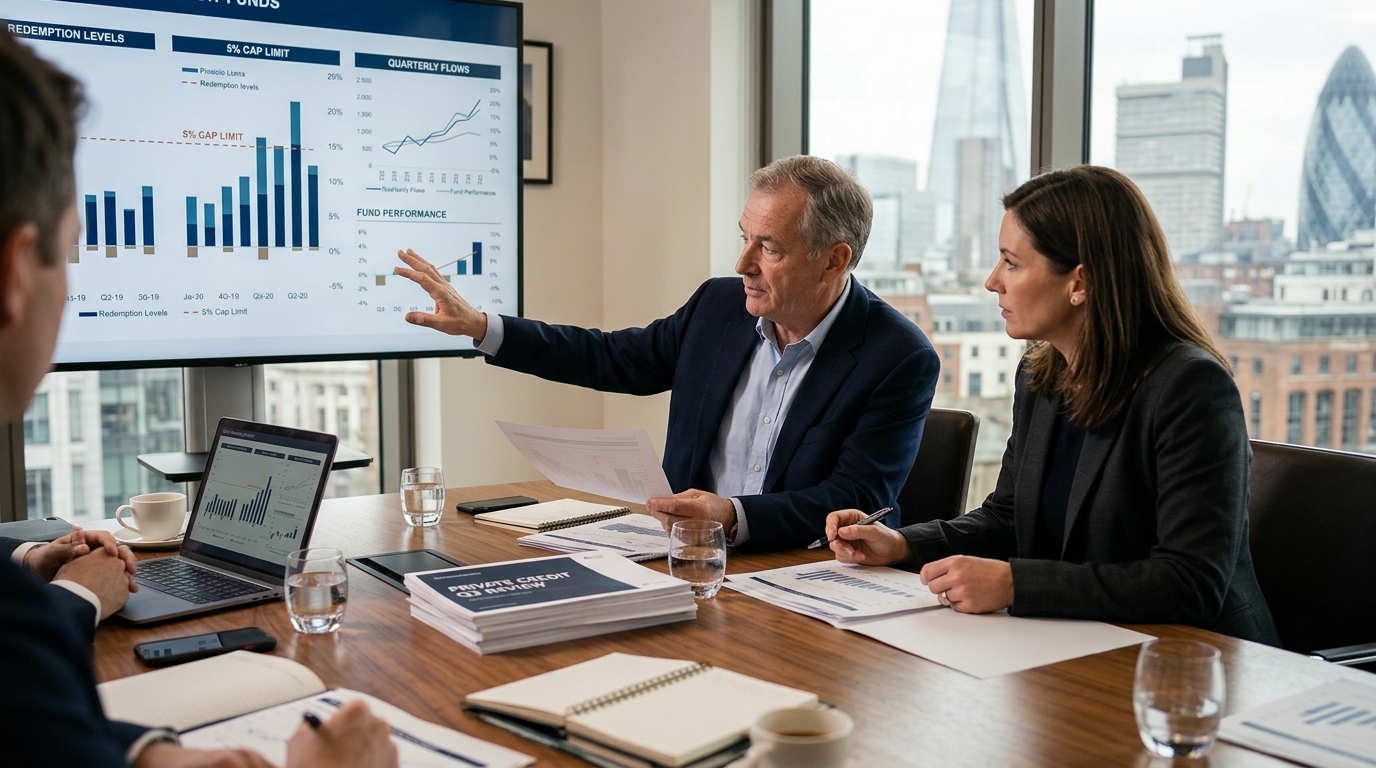
For the third consecutive quarter, Blue Owl Capital has told investors in two of its non-traded private credit funds that they cannot have their money back, at least not all of it. Reuters reported that Blue Owl again limited redemptions from two of its private credit funds at 5%, even as requests at its technology-focused fund remained elevated. Bulls will call this the system functioning exactly as designed. Bears will call it something else.
D-Day for AI Stocks
Where will you be at 9:30 AM on November 15?
That’s when The Great AI Shock promises to hit…
The moment the stock market splits in two.
The Bull Case: Structure Is the Feature, Not the Bug
Start with what the numbers actually show inside the portfolios. In shareholder materials, Blue Owl has pointed to low non-accruals at OCIC, including non-accruals around 0.2% of fair value as of March 31, 2026, and reiterated low non-accruals as of June 30, 2026. That is not a portfolio in distress. Those are the numbers of a book performing well.
The flagship fund has also said it has substantial available liquidity, and in communications earlier in 2026 it described liquidity on the order of tens of billions of dollars, across cash and available financing capacity. That is the point: the vehicle was built to meet periodic repurchase offers without being forced into selling loans. Blue Owl has also highlighted that OCIC has delivered roughly a 9% annualized return since inception in company disclosures.
The redemption cap itself is not improvisation. In fund documents and shareholder explanations, Blue Owl has framed the 5% quarterly repurchase limit as a way to balance periodic liquidity with protecting remaining shareholders from fire-sale dynamics. What looks alarming from the outside is, by design, unremarkable from the inside.
The trend in aggregate demand to exit is also moving the right direction. Reuters reported that investors sought to withdraw $4.2 billion from Blue Owl’s two funds in the third quarter, down from $4.7 billion in Q2 and a record $5.4 billion in Q1. Reuters also reported that Blue Owl said most requests reflected investors resubmitting previously unfulfilled tenders rather than new withdrawal demand, meaning fresh sellers are not piling in.
Watch this system catch Wall Street – live
A former insider built a machine to spot quiet Wall Street money moves as they happen.
Now watch it work – live.
And see it catch BlackRock sneaking $1 billion into one overlooked AI stock.
The Bear Case: OTIC Is Not Getting Better
The flagship OCIC fund is, slowly, improving. OTIC is not. Reuters reported that at technology-focused Blue Owl Technology Income Corp., investors sought to withdraw $1.1 billion, equal to 39% of shares, up from 38.1% in the prior quarter. Withdrawal pressure at the technology fund has now ticked higher for the most recent period, against the broad industry trend of stabilization.
These vehicles have come under pressure this year as investors rushed to exit private credit amid concerns about asset quality and, in tech-oriented portfolios, how advances in artificial intelligence could affect software borrowers and valuations.
There is also a structural concern that outlasts any single quarter’s redemption figure. Reuters reported that Blue Owl executives told sell-side analysts that software portfolio performance had remained broadly stable but refinancing risk could become more important as loans mature, particularly around 2028. The credit quality defense that bulls are leaning on today may face a genuine test in roughly 15 months, as 2028 approaches and borrowers begin negotiating extensions in earnest. Reuters also reported that Blue Owl management acknowledged that weaker credits may need to reduce leverage materially or could ultimately be sold or handed over to lenders.
Reuters also cited Evercore analyst Glenn Schorr noting that a more persistent challenge for non-traded BDCs may be weak new subscriptions, as direct lending could take time to regain favor among wealth-management clients and advisers. A fund that cannot attract new capital while serving existing redemption queues is running a slow arithmetic problem.
A Forgotten Energy Source Is Powering Back Up
While investors chase the next tech story, one long-ignored sector is quietly heating up. A mix of global policy, rising demand, and tightening supply could reignite this market before 2026. See what the latest research reveals.
Where the Evidence Leads
The bull case rests on verified credit fundamentals: low non-accruals and ample liquidity. Those are real. The bear case rests on something equally real: sentiment risk is not abating at OTIC, and the refinancing wall of 2028 has not been stress-tested publicly in a way investors can easily underwrite.
The two cases are not mutually exclusive. The redemption caps are working as designed, and the portfolio is, today, sound. But “working as designed” and “a stress signal worth watching” are not opposites. The structure absorbs the shock; it does not explain why the shock keeps coming at a fund where the fundamentals are supposedly fine.
What Could Change the Debate
Watch Q4 redemption requests at OTIC specifically. Three consecutive quarters at or above 38% makes it harder to attribute the pattern entirely to a concentrated shareholder base cycling through a queue. Any deterioration in non-accruals or portfolio-level operating metrics would shift the balance sharply toward the bears. Conversely, a meaningful drop in OTIC withdrawal requests in Q4 would validate the bull argument that the overhang is technical, not fundamental.
Final Verdict
The bull case is better supported today, but with a narrowing margin. Underlying credit quality at both funds remains defensible, total withdrawal demand is declining, and the cap mechanism is operating exactly as the fund documents describe. Blue Owl is not in crisis. However, OTIC is an outlier within an industry that is broadly stabilizing, and the 2028 refinancing cycle is a real, unresolved variable. This is not a broken structure. It is a functioning one carrying a concentrated AI-sentiment risk that has not yet found its floor.