Two catalysts in 48 hours. First, Senator Elizabeth Warren’s expected elevation to chair of the Senate Banking Committee sent a regulatory chill through digital assets on Wednesday. Then a roughly 5.5% plunge in the Nasdaq dragged Bitcoin back down on Thursday, crushing any post-election relief rally and reopening a debate that the crypto industry would prefer to leave closed: does Bitcoin function as a store of value, or is it simply a leveraged technology trade in disguise?
The Bull Case: Correlation Is Not Character
Start with what the bulls have on their side. As recently as late August, Grayscale research showed Bitcoin’s correlation with the Nasdaq falling to roughly 33% while its correlation with gold rose above 50%. That is not the behavior of a pure risk asset. When Bitcoin actually tracked gold rather than semiconductors, the store-of-value argument had data behind it.
The long-term supply case remains unchanged. After Thursday’s selloff, total crypto market capitalization sat at approximately $2.54 trillion. That is still above the roughly $2.3 trillion level the market touched during a comparable selloff on June 3, 2026. Every major drawdown has found a higher floor than the last. That is a pattern bulls point to as evidence of structural accumulation, not speculative froth.
The regulatory shock from Warren, meanwhile, may already be priced. If she assumes control of the Senate Banking Committee in January 2027, Warren is expected to exert greater authority over the direction of crypto legislation. That is a future risk, not a present one. Markets often overreact to anticipated headlines.
The Bear Case: The Evidence From Today Is Damning
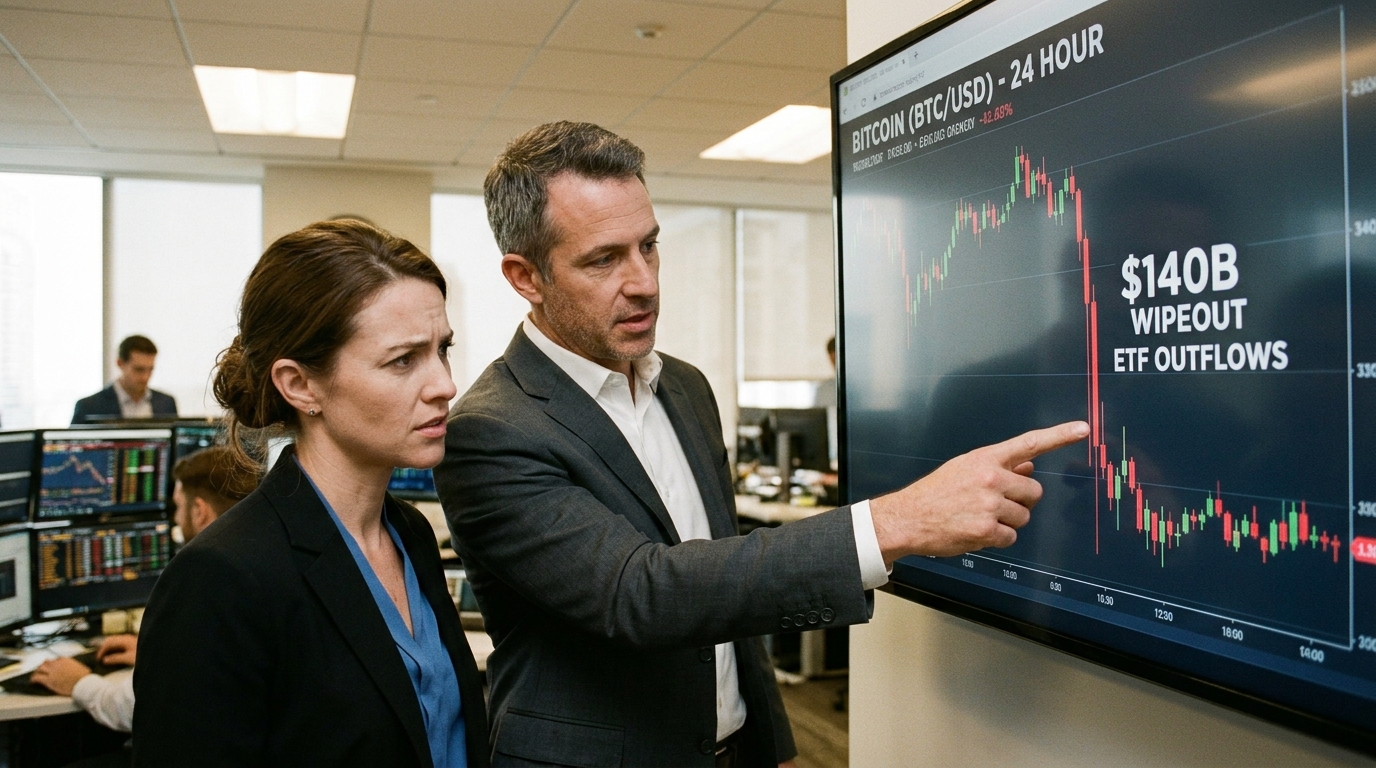
The problem is what actually happened this week. Bitcoin fell sharply as a roughly 5.5% decline in the Nasdaq triggered a broader risk-off move. The sell-off erased approximately $140 billion from the digital asset market within four hours, while liquidations across leveraged crypto positions rose above $1 billion. Most of the wiped-out positions were on the long side. That lopsided skew describes a market stuffed with one-directional, leveraged exposure, not a reserve asset held by conviction.
XRP fell sharply as Bitcoin, Ethereum, and XRP all declined in tandem on November 6. Broad-based altcoin collapses of this kind reflect sentiment contagion, the kind that strikes markets built on speculation rather than fundamental demand.
The ETF data is equally uncomfortable for Bitcoin advocates. Spot Bitcoin ETFs have seen net outflows of $869.8 million over four settled trading days so far in November 2026, with the largest single-day outflow reaching $430.2 million on November 5. BlackRock’s IBIT led the category with net outflows of $806.5 million for the month so far. These are not retail investors panic-selling. IBIT’s holders are institutions and financial advisors who built positions on the store-of-value thesis. When they exit, the thesis takes the hit.
The correlation data has also swung back sharply. Bitcoin’s correlation with the Nasdaq strengthened again amid rising U.S. inflation and AI-related stock sell-offs, with IBIT options becoming a central venue in Bitcoin options market open interest. The instrument that was supposed to democratize access to digital gold is now deeply embedded in the same institutional risk framework that governs tech stocks. Bitcoin also exhibits asymmetry, tending to suffer disproportionately during risk-off episodes. That is the worst of both worlds: correlated to the downside, inconsistently uncorrelated to the upside.
Where the Evidence Leads
The honest answer is that Bitcoin behaves like whichever asset class dominates the marginal flow. In 2025, when liquidity was abundant and institutional adoption was accelerating, it tracked gold. Today, with Warren expected to chair the Senate Banking Committee as Bitcoin falls toward $75,500 and the Nasdaq in a rout driven by AI spending fears, it trades like the highest-beta item in the risk-off liquidation queue.
The same risk-off pressure hits crypto-adjacent equities differently depending on how much of their revenue depends on Bitcoin cooperating. Coinbase and Robinhood expose that split clearly — one business needs Bitcoin to move, the other has already diversified past it.
That is not a verdict on Bitcoin’s long-term worth. It is a verdict on who holds it now and how they hold it. Reports point to liquidations of leveraged positions as a factor that accelerated Bitcoin’s price drop once key support levels were breached. Leverage transforms any asset into a momentum instrument. The roughly $140 billion lost on Thursday says less about Bitcoin’s nature than about the crowded, leveraged structure sitting on top of it.
Final Verdict
The bear case wins today, narrowly but clearly. The early-November ETF outflow trend, liquidations above $1 billion, and Bitcoin’s close mirroring of the Nasdaq’s AI-fear selloff all point to an asset trading on risk appetite rather than scarcity. If Bitcoin fails to consolidate support above $75,500 and weakness persists on Wall Street, selling pressure could push prices toward lower ranges; a rebound in traditional stock indexes could support stabilization in upcoming sessions. Watch IBIT daily flows and the Nasdaq’s AI earnings commentary for the clearest signal on which direction resolves first.