October 31, 2026
Bonus Content: Twilio Fell 15% on a Beat. Is Software Broken or Mispriced?
Dear Reader,
Everyone wants to know what Elon Musk is planning next.
I believe this is it – what I’m calling, “Mission X.”
Elon’s bold new plan to ship AI off the Earth entirely – and launch it into the stars.
He confirmed it himself:
“I see a path to SpaceX being worth orders of magnitude more than the current Earth economy.”
– Elon Musk
Because I promise you, he’s not just talking about launching rockets.
It’s why I’ve just released all the details of “Mission X” – including a FREE ticker to get positioned at practically the ground floor – without buying SpaceX or Tesla.
Click Here to Watch – 100% Free. No Credit Card Required.
Best,
Tim Bohen
P.S. Billionaire Peter Thiel once said: “I would never bet against Elon, in anything. That’s hard rule number one.”
The skeptics are lining up again. But you don’t have to miss out.
REVEALED: Free Ticker to Claim Your Stake in “Musk’s Mission X.”
Twilio Fell 15% on a Beat. Is Software Broken or Mispriced?
The question hanging over software right now is not whether individual companies can grow. This week showed they can. The question is whether the market has decided that the growth they are delivering is the wrong kind.
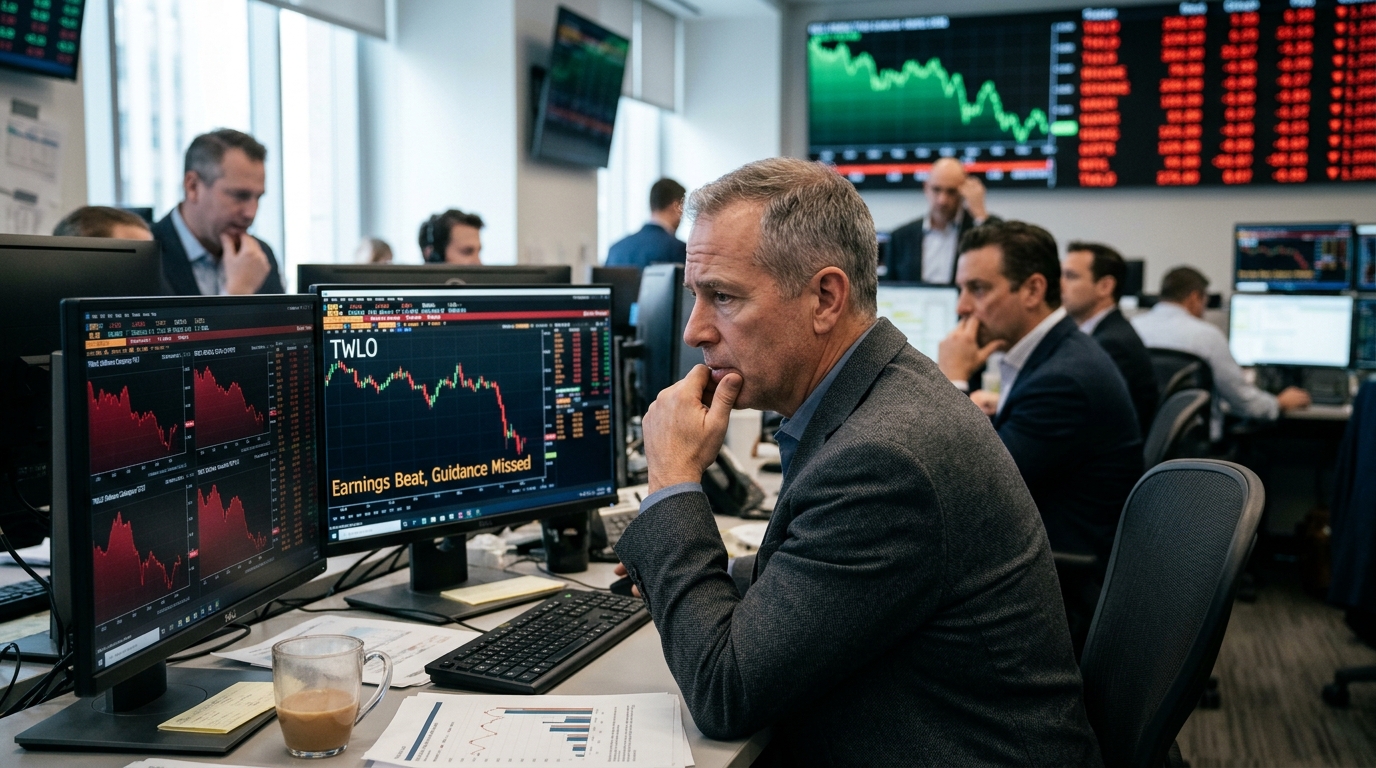
Twilio became the latest exhibit on Friday. The company reported non-GAAP earnings of $1.65 per share, beating the $1.47 consensus estimate, on revenue of $1.56 billion. Total revenue rose 20% year over year, driven by broad-based strength across the product portfolio. The stock fell roughly 15% on the day. It was the fourth software name to suffer that fate in five sessions, following Fortinet and ServiceNow earlier in the week. The software ETF IGV fell 5.7% across the week ending October 30.
The Bull Case: Selling the Wrong Thing
Start with what Twilio actually reported. Q3 organic growth came in at 16% year over year. Operating cash flow reached $389 million and free cash flow totaled $370 million. The company raised its full-year 2026 reported revenue growth forecast to 20% from a previous range of 18% to 18.5%. That is not a struggling business.
The bull argument is that this week’s software selloff is indiscriminate. Twilio highlighted increased AI adoption as a demand driver for its infrastructure products and reported a higher dollar-based net expansion rate, indicating increased spending by existing customers. The CEO framed the AI opportunity as early-stage, with monetization still scaling. Management also emphasized that the 11% to 12% Q4 organic growth guidance is the company’s strongest quarterly organic revenue growth guidance in several years.
The broader peer group tells a similar story. Fortinet reported Q3 revenue of $2.08 billion, up 20% year over year, with non-GAAP earnings of $0.91 a share and billings up 29% to $2.34 billion. That is a clean beat by any conventional measure. The stock still fell roughly 20% in the session following its results. If the market is punishing 20% revenue growth accompanied by rising billings, the bear thesis is less about fundamentals and more about positioning at elevated multiples.
The Bear Case: The Guidance Gap Is the Story
The counter-argument is more uncomfortable for holders. Investors focused on Twilio’s Q4 organic revenue guidance of 11% to 12%, a significant slowdown from the third quarter’s 16% organic growth rate. That five-point deceleration is not noise. Messaging, which accounts for about 59% of Twilio’s revenue by its own quarterly mix disclosure, was the primary reason the revenue beat was smaller than those recorded in the first half.
Software earnings have been a stress test for expectations because investors are still debating whether newer AI models become features that help vendors charge more, or substitutes that weaken pricing power. That uncertainty is real and probably structural. ServiceNow fell more than 25% after its results. The concern is that AI agents could reduce per-seat software economics, and ServiceNow, as a bellwether for the sector, saw its weaker outlook add fears about growth across the industry.
The same AI-disruption fear has weighed on the entire enterprise software cohort, not just workflow and communications vendors. Salesforce has been navigating the same per-seat disruption concern while its Agentforce ARR surged more than 240% year over year.
Twilio’s valuation is high enough that it leaves limited room for execution missteps. When you pay a premium multiple, you are paying for acceleration, not deceleration. A guide-down from 16% to 11-12% organic growth, regardless of the absolute level, violates the contract the valuation implies.
Adobe’s experience illustrates the same valuation trap. A software company beating on earnings and raising guidance can still fall when guidance misses the acceleration investors priced into a premium multiple.
Where the Evidence Leads
The two cases are not actually incompatible. Software is being sold indiscriminately in the short run, but the indiscriminate selling is being triggered by a legitimate signal: guidance deceleration at companies priced for the opposite.
Software companies have been under intense scrutiny this year as investors weigh the likelihood of newer AI models disrupting traditional business models, and many software stocks have lagged the broader S&P 500. The sector entered earnings season expensive and without much margin for disappointment.
Twilio’s own CFO acknowledged on the call that the company did not expect the large beats from the first half to persist. The Q4 organic guide above 10% is, by management’s own description, the strongest in years. But that framing only works if the market trusts management’s longer-term outlook for sustained double-digit organic growth. Premium valuation multiples leave limited room for execution missteps or guidance disappointments.
The verdict: software has not been broken by AI, but the market’s tolerance for paying growth-stock multiples on decelerating organic growth clearly has. For Twilio specifically, the fundamentals are intact. The risk is a reset in valuation, not collapse. Watch whether Q4 organic growth comes in above the 12% ceiling of guidance. If it does, and the stock stays down, the bull case becomes considerably more compelling.