On Thursday morning, an oncology news website breached ESMO’s embargo and circulated screenshots of the INTerpath-001 results. ESMO subsequently responded by lifting the embargo and releasing the abstract publicly. What followed was one of biotech’s stranger afternoons: a company whose stock fell roughly 25% intraday on data that confirmed its drug works.
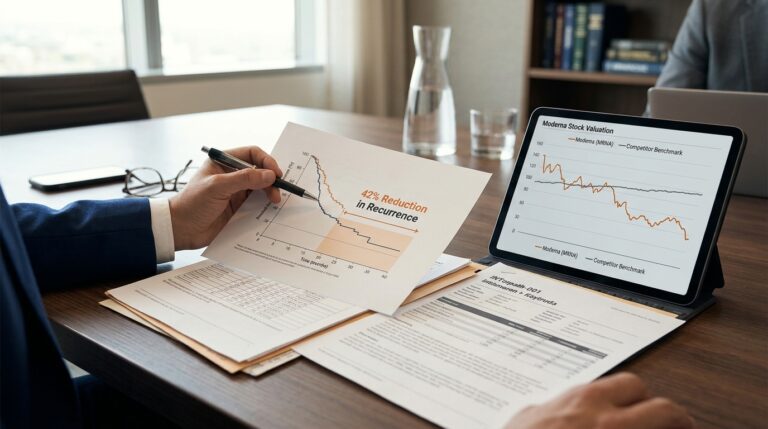
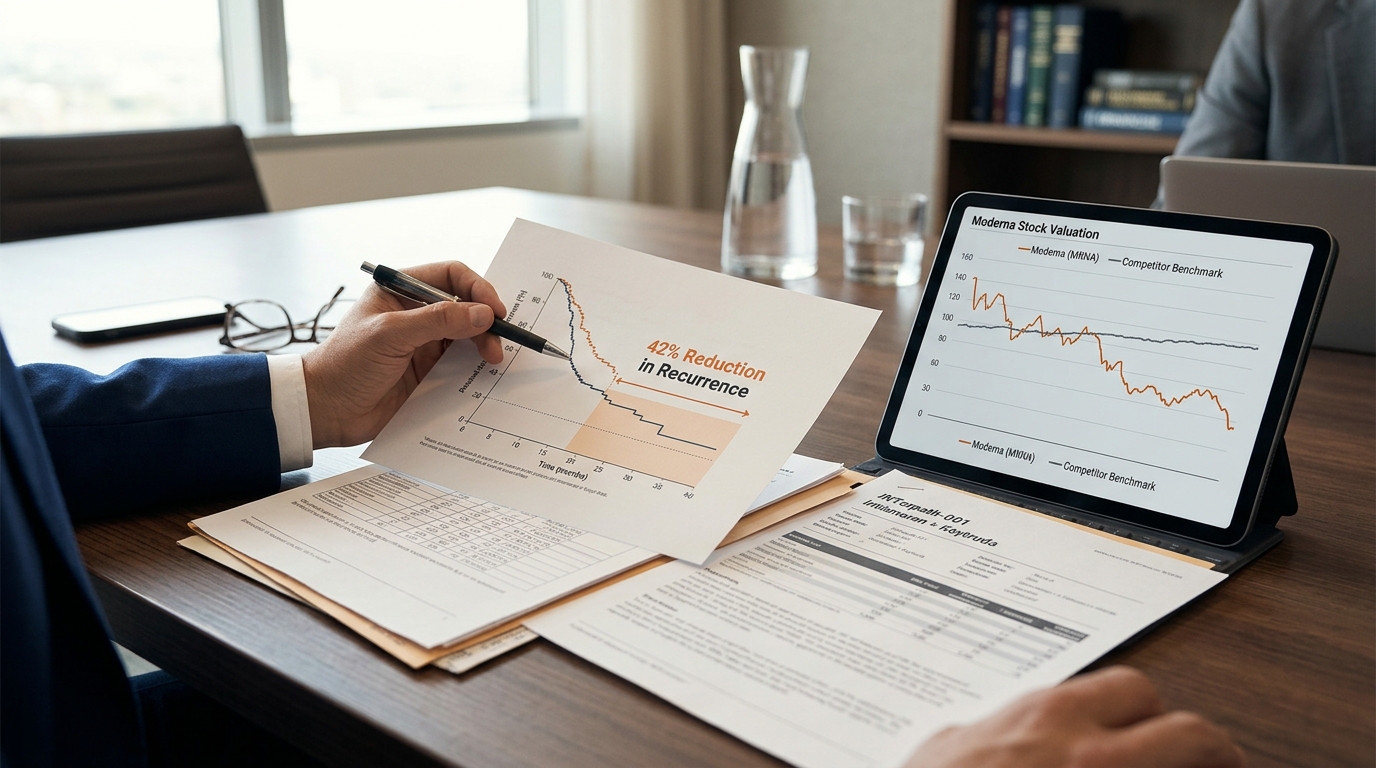
Intismeran plus Keytruda significantly reduced the risk of recurrence or death by 42% (HR=0.58; p<0.001) compared to Keytruda alone in patients with completely resected stage IIB-IV melanoma. The combination also significantly reduced the risk of distant metastasis or death by 38% (HR=0.62; p=0.002). By any conventional reading, this is a positive Phase 3 result. The debate is whether it is good enough to justify what Moderna’s stock had already priced in.
The Bull Case
INTerpath-001 is a large, active-comparator Phase 3 trial against standard-of-care Keytruda, and it met both recurrence-free survival and distant metastasis-free survival endpoints in 1,137 patients. That is not a minor distinction. Keytruda alone is a potent comparator, and beating it at this scale carries regulatory and commercial weight that a placebo-controlled study would not.
TD Cowen analyst Tyler Van Buren wrote that the findings represent a compelling efficacy profile and clear the physician-defined bar for a practice-changing dataset in adjuvant melanoma, according to BioPharma Dive. Outcomes were comparable between arms in the first six months, but later analyses highlighted that the separation appeared after that early period. That delayed but durable signal is exactly what you would expect from a vaccine building an immune response over time. Two years in, 82.2% of patients on the combination were alive and recurrence-free, against 70.0% on Keytruda alone.
Merck and Moderna are also testing intismeran across additional tumor types, including non-small cell lung cancer and bladder cancer. The platform argument, not just the melanoma label, is what the bull case ultimately rests on.
The Bear Case
The same hazard ratio that bulls call practice-changing is the number some skeptics framed as the low end of expectations, pointing to a clear step down from earlier testing. The comparison is direct: Merck said five-year follow-up data from Phase 2 presented at ASCO 2026 showed intismeran plus pembrolizumab reduced the risk of recurrence or death by 49% (HR=0.51). The Phase 3 HR of 0.58 sits near the bottom of the range investors had anticipated.
The metastasis endpoint tells a starker story. Merck said Phase 2 follow-up showed a 59% reduction in distant metastasis or death at five years (HR=0.411). The Phase 3 figure is 38%. Even if approval looks likely, commercial success is far less certain if physicians decide neoadjuvant immunotherapy already captures much of the achievable benefit without individualized manufacturing and added complexity.
Overall survival data remain immature, so the endpoint that ultimately moves oncology practice cannot yet be assessed.
Where the Evidence Leads
The clinically honest answer is that both camps are reading the same data correctly. The distinction between relative and absolute benefit matters: the vaccine improved outcomes on top of an active immunotherapy, but the control arm still performed well, meaning the clinical decision is not simply whether the treatment works, but whether the added reduction in recurrence risk justifies individualized manufacturing, repeated injections, and additional treatment burden.
That framing matters more than the data itself for judging Moderna’s current price. Against a Thursday close of about $202.63 on Oct. 22, 2026, some widely followed consensus datasets still show an average analyst price target around $123.61, implying substantial downside if those targets prove directionally right. The science appears to have cleared the regulatory bar. The stock arguably cleared a much higher bar before the detailed results arrived, and that gap may not be fully closed.
The full Presidential Symposium presentation in Madrid today may sharpen the subgroup data and provide context that the early screenshots and abstract could not. Watch for overall survival trends and any signal in the lung and bladder programs over time. Those are the readouts that will settle whether the platform is worth what remains priced in, or whether Thursday’s sell-off was only the beginning.