Alphabet fell 3.73% on September 23, its worst single session in weeks, while Meta rose and Microsoft closed essentially flat. Two things happened that day: the UK’s Competition and Markets Authority published its toughest proposals yet for Google’s search distribution, and Meta’s Muse AI agent kept accumulating downloads at a pace that is beginning to unsettle investors who have long treated Google’s default placements as untouchable. Both forces point in the same direction.
The Bull Case for Alphabet
Default distribution is powerful, but what the bears keep underweighting is how deeply Google search is wired into behavior rather than merely into settings menus. A large chunk of Google’s traffic is navigational: users typing a brand name instead of a URL, which is the hardest kind of usage for a competitor to steal. Google holds 91.27% of the global search market as of June 2026, and the market share erosion so far is measured in tenths of a percentage point per year. Annual re-prompts on Android did not appear from nowhere either: UK users already see basic search engine choice screens. Choice screens existed in Europe after the 2018 antitrust ruling, and Google kept roughly the same share in affected markets. Habit is extraordinarily sticky.
Mobile is Google’s strongest ground, with a roughly 94.6% global mobile share locked in by default Android placements and Chrome’s tight integration with Google Search. The CMA framework changes the initial choice on that surface. It does not change what users type once they land there.
The Bear Case
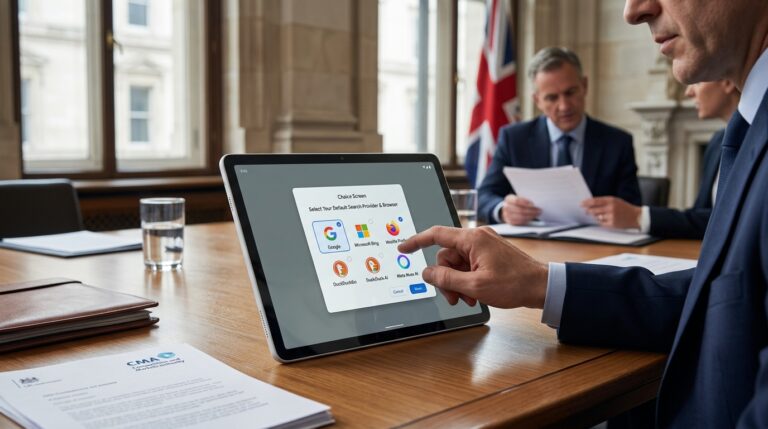
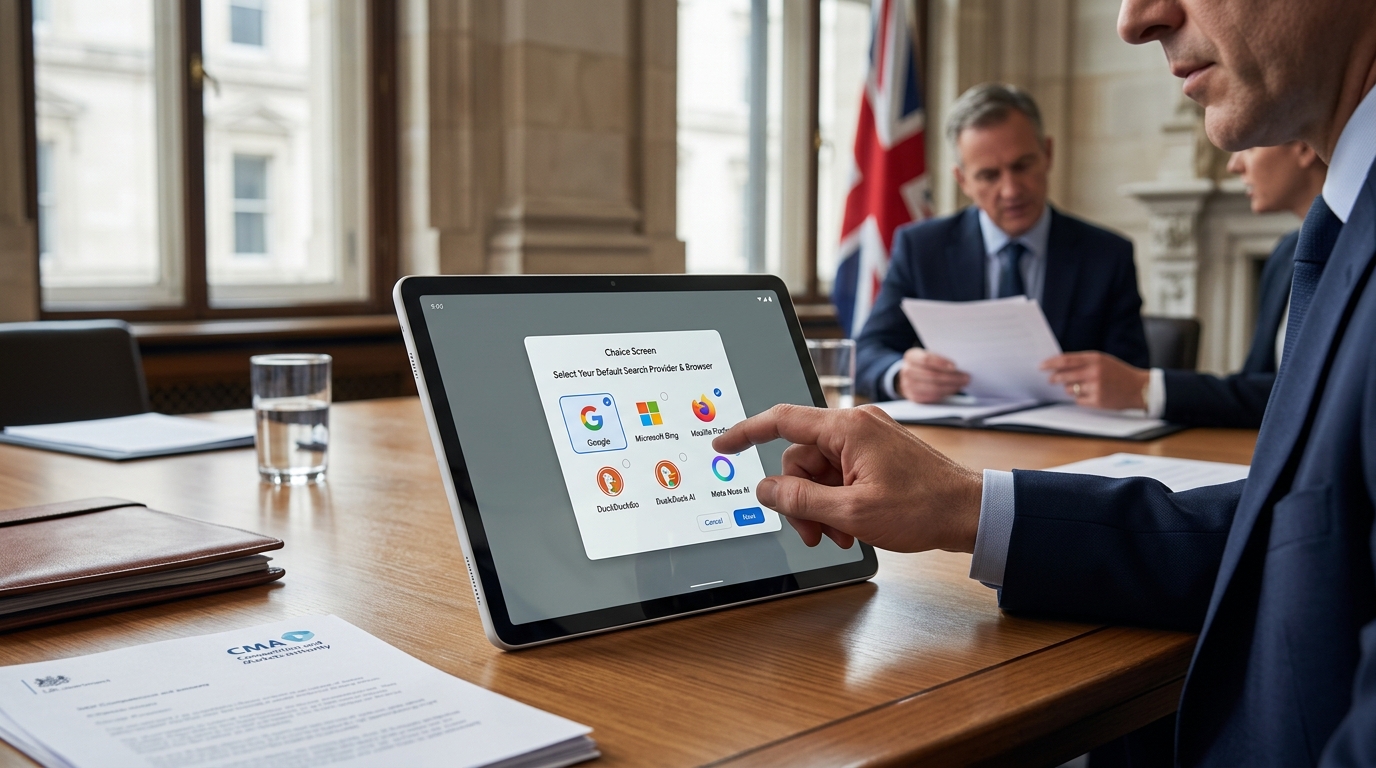
The CMA’s September 23 proposals go meaningfully further than anything before them. The rules would require Google to show users a choice of search providers when they use an Android phone or open Chrome for the first time, prompt them once a year to pick a default, and allow AI assistants meeting technical and security criteria to appear on those screens. Products such as ChatGPT and Perplexity, which the CMA cited as examples of newer services people are using, would be eligible to appear if they meet the regulator’s technical and security criteria.
That last point is the structural shift. Prior choice screens were contests between search engines. This one would place conversational AI assistants on the same ballot. The revised draft redraws the boundary of what counts as a search service. The regulator says the line between conventional search engines and AI-based services is now increasingly blurred, and it no longer wants to exclude products simply because they use an AI interface.
The timing compounds the problem. Meta’s Muse AI assistant surpassed 2.8 million installs in its first 12 days, according to Apptopia data. For Alphabet, consumer agents capable of executing tasks directly challenge the ad auction model that generates the bulk of its operating profit. Meanwhile, Alphabet is directing record sums into data centers and hardware, raising its 2026 capital expenditure forecast to between $195 billion and $205 billion, according to CFO Anat Ashkenazi on the company’s second-quarter 2026 earnings call. Regulatory exposure and a capex supercycle is an uncomfortable combination.
Google’s all-device share dropped roughly 1.5 percentage points year-over-year, the largest single-year erosion since 2009. The direction of travel matters as much as the level.
Where the Evidence Leads
The annual re-prompt is the mechanism worth watching most closely. The yearly re-prompt matters most for everyday users. Defaults stick because most people never revisit them. A prompt every year gives people a regular moment to switch without digging through settings. That is a genuine structural change, not a theoretical one.
Still, the bear case requires a behavioral shift that has not materialized at scale anywhere else choice screens have been deployed. What is different this time is the quality of the alternatives. ChatGPT and Perplexity are not Bing circa 2010. They offer a meaningfully different product, and AI search referrals are clearly rising across multiple third-party datasets. The base is still small, but the trajectory is real.
What Could Change the Debate
The CMA consultation closes October 9, with a final decision expected by year-end, building on the October 2025 strategic-market-status designation. If the proposals are weakened in the final ruling, the bear case loses its regulatory leg. If ChatGPT or Perplexity fail to meet the technical and security eligibility criteria, the choice screen reverts to a contest Google has won before.
Watch for whether the US Department of Justice’s parallel remedies process, still unresolved, mirrors the CMA’s approach on default distribution. If it does, the addressable scale of the problem for Alphabet multiplies considerably beyond the UK.
Final Verdict
The bull case rests on the resilience of habit, and that is not a weak argument. But it is being tested simultaneously by better-funded competitors, an annual regulatory re-prompt, and a capex commitment that leaves little margin for a structural revenue decline. The bear case carries more weight today than it did 12 months ago. Alphabet’s moat is not gone, but it is, for the first time in a decade, measurably narrower. Investors should hold the position lightly until the CMA’s final ruling and the DOJ’s remedy decision give the regulatory picture a cleaner shape.