Sunday’s most important oil market event was not what Iran did. It was what Brent did afterward.
Iran’s Islamic Revolutionary Guard Corps said it launched six drones at a U.S. air-defense radar system at Bahrain’s Al Riffa helicopter base, describing the strike as retaliation for hostile U.S. actions. The IRGC claimed a “successful impact,” while Bahrain said its air defenses intercepted and destroyed several aerial attacks. Blasts and sirens woke Manama before dawn. Saudi forces were striking Houthi positions across three Yemeni governorates. By any geopolitical checklist, this was a significant escalation rung.
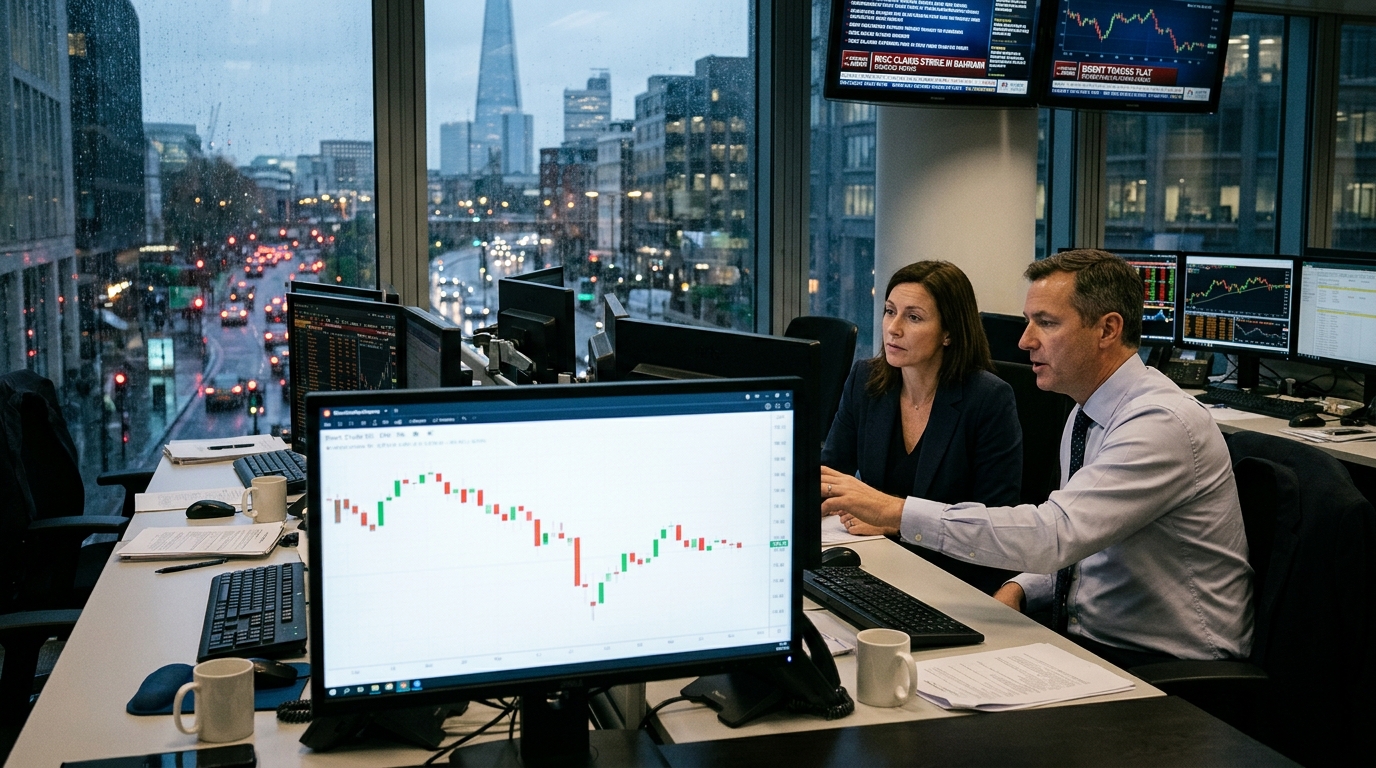
Brent’s response: a brief dip below $95 in Asian trade, a bounce near the mid-$96s at the European open, and then a drift back toward $95 by mid-morning. By Monday’s session, Brent was trading around $94.88, down about 1% from the previous close. The market, in other words, looked at a claimed Iranian attack on a Gulf state hosting American forces and sold off anyway. That is the signal worth reading.
Why Supply Is Winning the Argument
The fundamental explanation arrived on Friday, the day before the drones flew. The International Energy Agency said in its November oil market report that its balances point to a return to surplus in the fourth quarter of 2026, after a sharp rebound in Gulf exports outpaced global demand. In the same report, the IEA said global supply rose to about 105.4 million barrels per day in October, and observed inventories rose by roughly 52 million barrels, or about 1.7 million barrels per day, in October as exports recovered faster than demand.
The mechanism behind that shift is worth understanding. Even with ongoing attacks and elevated security risk in and around the Strait of Hormuz, exports have adapted and flows have recovered compared with earlier in the war. The market already knew this before Sunday morning.
Other analysts have also flagged the risk of renewed excess supply even without a clean geopolitical resolution. When the IEA is leaning that way, a drone strike on a radar site is not going to override the balance sheet.
What the Market May Be Missing
The price action is rational on the supply side. Where it deserves more scrutiny is the risk premium being assigned to an escalation pattern that has not stopped accelerating. Sunday was the second time in three days that the IRGC claimed to have targeted a U.S. radar system in Bahrain. Each attack that is intercepted and absorbed without a price response teaches the market to discount the next one more aggressively. That is a reasonable heuristic until the one attack that is not intercepted.
Shipping and insurance costs remain elevated due to ongoing risks around the Strait of Hormuz, even as oil supply stabilizes and incidents keep freight rate premiums supported. That divergence, spot crude falling while freight stays elevated, is the structural tension the headline price obscures. Refiners paying more to move barrels are not experiencing the same relief the futures strip implies.
Where It Shows Up
For energy equities, the read is mixed. Saudi output and export normalization is part of what sits behind the IEA’s upward tilt to Gulf supply, which is bearish for realized prices but positive for volumes. The XLE and the broader energy sector face the same crosscurrent: physical flows are recovering, but the geopolitical premium that inflated valuations from March through October is now being systematically priced out.
What to Watch
The IEA also cautioned that shipping security remains fragile, with attacks continuing even as more authorized cargoes pass through. The level to watch on Brent is $91, the recent ten-week low touched on November 10, 2026. A close below there would confirm that the supply-surplus thesis is overriding geopolitical risk entirely. A sustained move back above $98 would suggest the market has finally begun charging for the escalation it has spent two months dismissing.