Back in the 1860s, settlers from France, Italy, and Germany built grand Parisian boulevards…
…neoclassical facades…
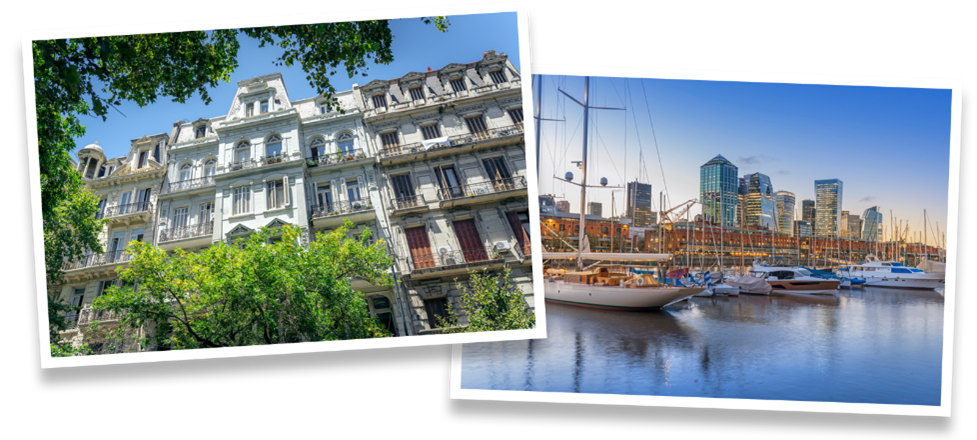
… and cobblestone Bavarian villages halfway across the globe.
Then the rest of the world largely forgot about them.
Today, expats are uncovering a European standard of living…
… Lakefront rental homes for $721 a month…
… private chauffeur service…
… and elite healthcare – completely free from tourist crowds and inflated European price tags.
Two Different Economies, One Household Debt Report
On Tuesday morning at 11:00 ET, the Federal Reserve Bank of New York will drop its Q3 2026 Household Debt and Credit Report. The timing could not be more loaded. October payrolls came in at 165,000, more than double consensus forecasts. The National Retail Federation is projecting holiday spending to top $1.013 trillion for the first time. CME FedWatch now prices an 81% probability of a December rate hike. By any of those measures, the American consumer is holding up fine.
By the measure that lands Tuesday, something else is happening entirely.
The Bull Case: Spending Holds, Payrolls Lead
Start with what is undeniably true. October’s jobs number was not a rounding-error beat. Nonfarm payrolls rose 165,000 against a consensus near 65,000, with upward revisions adding 84,000 jobs to August and September. The three-month average climbed to 137,000. Professional and business services alone added 70,000 jobs, the fastest monthly rate in years.
Spending data backs the resilience argument. Visa Business and Economic Insights forecasts holiday retail sales rising 4.5% year over year, the strongest seasonal growth since 2021. Adobe projects a record $275.1 billion in online holiday sales, up 6.7%. Ally Financial, the country’s largest all-digital auto bank, reported $12.9 billion in consumer auto originations in Q3, up roughly $1.2 billion from a year earlier. Capital One’s 30-day auto delinquency rate actually improved year over year, to 4.64% from 7.92%. The bull reads these figures and concludes that the household sector, in aggregate, is absorbing rate pressure and spending anyway.
The Bear Case: The Subprime Floor Is Cracking
Aggregate figures have a habit of hiding exactly who is breaking down. Fitch Ratings’ index of subprime auto loan delinquencies hit 6.9% on a 60-day-plus basis in early 2026 and sat near 5.8% by mid-2026. Even after easing from the peak, the structural conditions that produced it, extended loan terms, near-record vehicle prices, and average new-car payments around the high-$700s per month, have not changed.
The NY Fed’s own Q2 data show 90-day auto delinquencies at 5.49% of balances and student loan balances with 10.6% of their total 90-plus days past due. Meanwhile, the University of Michigan’s consumer sentiment index sat at 48.0 in October, 10.4% below where it was a year ago and near the bottom of its survey history. Consumers say one thing in surveys and do something different at the register. That gap rarely holds indefinitely.
Ally’s Q3 earnings report revealed the tension directly. Provision for credit losses rose 27% year over year to $529 million, with 30-day retail auto delinquencies climbing to 4.96%. Executives said loans originated in late 2025 and early 2026 are showing higher early-stage delinquencies, a trend they described as being closely monitored. For Credit Acceptance, whose entire business sits in the deepest subprime tier, that vintage risk is not an abstraction.
Where the Evidence Leads
The two-speed economy thesis is not new, but Tuesday’s report will show whether the gap between prime and subprime borrowers is widening or stabilizing through Q3. What makes this release different from previous quarters is the Fed backdrop. The FOMC held at 3.75%-4.00% in late October, and futures markets are now assigning roughly an 80% chance of a 25-basis-point hike on December 9. A rate increase would arrive at precisely the balance sheet Tuesday’s report describes: auto debt at $1.71 trillion, credit card balances at $1.26 trillion, and subprime borrowers already stretched.
The holiday spending record and the delinquency peak are not contradictory, they are the same economy viewed from different income levels. Upper-income households are driving the aggregate spending gains that make the NRF forecast achievable. Subprime borrowers are driving the delinquency data that makes Credit Acceptance and Santander Consumer worth watching carefully into year-end.
That income-level split is not unique to auto lending. Credit card delinquency dispersion between JPMorgan and Synchrony shows the same bifurcation playing out across the broader consumer lending sector.
What Could Change the Debate
October CPI, due the same week as the NY Fed report, is the more immediate swing factor for December Fed odds. A cool reading could push hike probability back below 70% and relieve some pressure on variable-rate debt holders. A hot reading reinforces the December hike path and tightens conditions further for the borrowers already showing up in delinquency tables.
Final Verdict
The bear case carries more weight here, with moderate confidence. Strong payrolls and record holiday forecasts describe the top half of the income distribution with reasonable accuracy. The subprime auto delinquency data, the Michigan sentiment readings, and rising provision expenses at Ally describe the bottom half with equal accuracy. The problem for investors in Ally, Capital One, Synchrony, and Bread Financial is that a December rate hike does not hurt the top half much. It hits the borrowers already 60 days past due on a roughly $780-a-month car payment. That is not a rounding error. Tuesday’s report will tell us how much further that stress has traveled through Q3.