The prospectus is due any day. The roadshow begins in mid-October. And if the calendar holds, Anthropic will complete what could be the largest IPO ever attempted just days before the U.S. midterm elections on November 3, 2026. The company is expected to begin marketing its initial public offering in mid-October at the earliest and complete the listing days before the U.S. midterm elections in November. That compressed window is not the most consequential thing about this deal. The financials are.
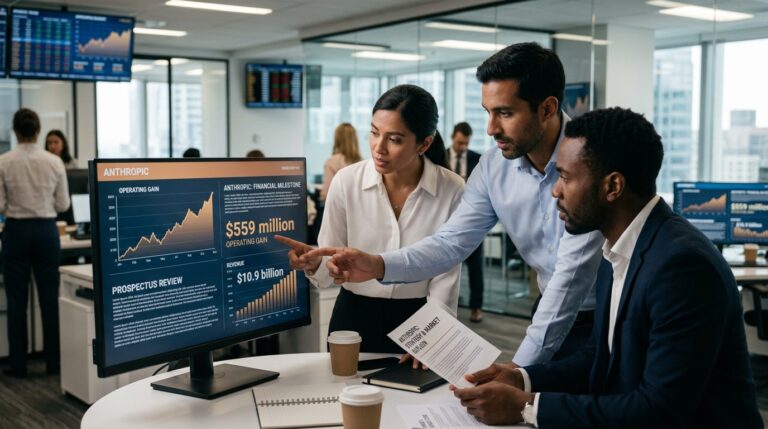
Anthropic is projected to post its first operating profit in Q2 2026, with revenue of $10.9 billion and an operating gain of roughly $559 million, more than double the $4.8 billion it recorded in Q1, a growth rate that places Anthropic among the fastest-scaling software businesses in history. For context: Anthropic’s growth is running ahead of Zoom during the pandemic, ahead of Google before its IPO, ahead of Facebook before its IPO. And unlike those companies at comparable stages, Anthropic is already generating positive operating income.
The mechanism behind the margin turn matters. The company spent 71 cents on compute for every dollar of revenue in Q1 2026. The Q2 projection shows that ratio falling to 56 cents, a fifteen-cent shift in a single quarter. That is the lever that turns a near-break-even result into a $559 million operating profit. Claude Code surpassed $1 billion in annualized run-rate revenue within six months of its launch, driven by enterprise developers. Coding workloads, where customers pay for completed output rather than idle capacity, carry structurally better economics than general consumer inference. That distinction is what moved the numbers.
The run rate has kept climbing. Anthropic’s annualized revenue run rate reportedly exceeded $65 billion by the end of July 2026, up from approximately $47 billion in May and about $9 billion at the end of 2025. On reported run-rate revenue, Anthropic has pulled ahead of OpenAI, with Anthropic at approximately $45 billion annualized revenue versus OpenAI around $33 billion as of May 2026. OpenAI is generating significant losses, with shareholder documents first reported by The Information showing it burned $3.7 billion in Q1 2026 on $5.7 billion of revenue. The contrast is sharp enough to reframe the competitive question entirely.
But the prospectus will also force investors to confront the cost side of the ledger. Nscale’s S-1, filed September 18, 2026, disclosed that the company agreed to provide Anthropic with dedicated GPU infrastructure at its Monarch Compute Campus, with aggregate payments of up to approximately $44.6 billion. Anthropic’s agreement with Nscale is contingent on Nscale obtaining financing, and Anthropic retains the right to walk away if Nscale fails to hit milestones the filing explicitly categorizes as “stringent.” That contingency is a reminder that contracted compute and delivered compute are different things, and that the obligations Anthropic is accumulating across multiple suppliers will need to appear in its own public filing.
The numbers represent a sharp reversal from financial guidance Anthropic gave investors last summer, which suggested the company did not expect to turn a full-year profit until at least 2028. Anthropic has cautioned it may not sustain profitability for the full year, given planned spending tied to computing infrastructure.
At a valuation of $2 trillion, Anthropic would be priced at about 31 times its annual run rate, making it an expensive stock. That is not disqualifying for a business growing this fast. But the underwriters, Morgan Stanley, Goldman Sachs, JPMorgan and Citigroup, will need to answer whether the first profitable quarter is a durable inflection or a high-water mark that compute obligations could quickly erode. The prospectus, arriving now, is where that question stops being theoretical.