The investment committee question used to be whether Oracle could build fast enough. Now it is whether the customer paying for the build is creditworthy at all.
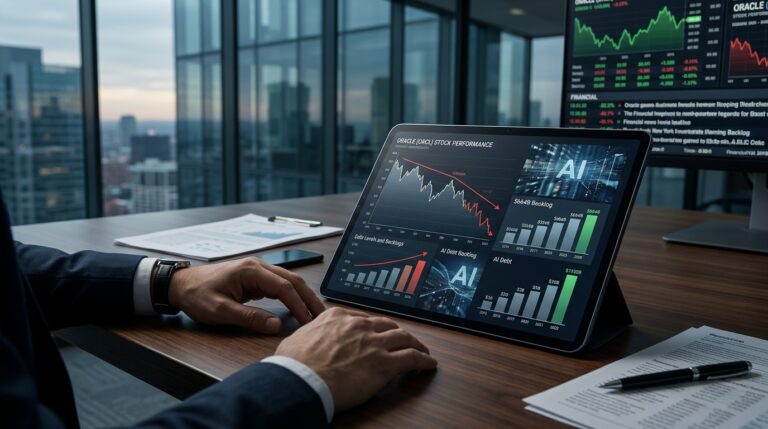
Oracle fell 5.1% to about $118.94 on November 16, extending a year that has taken the stock down roughly 34% and more than 60% from the $323.43 peak it reached in September 2025. This is not noise. It is the equity market completing a reset that credit markets began months earlier.
Why Wall Street Cares
The issue is structural, not cyclical. Analysts point to Oracle’s planned $90 billion to $95 billion in data center spending, rising debt, and negative free cash flow as the core concern. Oracle reported negative free cash flow of $23.7 billion for fiscal 2026 as it invested to expand cloud infrastructure. And the credit market got there first: the yield on CoreWeave’s 2032 bond with a 9.625% coupon climbed above 16%, while its five-year credit default swaps spiked above 1,289 basis points.
That CoreWeave signal matters for Oracle specifically. Both companies are leveraged proxies for the same AI demand story, and when the weakest borrower in a chain resets, the question moves up the ladder.
The Bull Case
At the end of its last quarter, Oracle reported remaining performance obligations of $664 billion. Bulls argue that cloud revenue growing 44% year-on-year confirms the demand is real, and despite aggressive spending, the consensus analyst rating remains “Strong Buy,” with the mean price target near $241, implying potential upside of nearly 100% from current levels.
The Bear Case
The backlog number is where the bull case gets complicated. At least $300 billion of that backlog is widely estimated to come from OpenAI, meaning around half of Oracle’s contracted future revenue may rest with a single customer. OpenAI lost roughly $20.9 billion on an operating basis in 2025, and its IPO has reportedly slipped to 2027.
Ratings pressure and legal risk have followed the financing. Oracle has been sued by bondholders who claim the company concealed how much additional debt it would need to sell to support the AI buildout for its OpenAI deal.
What Investors Are Missing
The debate is framed as a debt question. The deeper issue is an underwriting question. Oracle’s backlog is not an enterprise software order book with hundreds of counterparties. None of this means the backlog is illusory. It means the backlog is contingent in a way that a traditional enterprise software order book is not, and investors are right to demand a discount for that. The unspoken risk: if OpenAI delays or restructures its compute commitments, Oracle does not simply lose revenue. It holds stranded infrastructure financed by bonds whose investors are already in court.
Oracle ended its August 2026 quarter with $125.34 billion in notes payable and other borrowings. Every subsequent capital raise has tested the same question at a higher number. The market’s answer on Monday was clear.
Stocks to Watch
Oracle (ORCL). The central position. At roughly 14 times forward earnings, the valuation reflects the financing risk, but not necessarily an OpenAI revenue shortfall on top of it.
CoreWeave (CRWV). Down sharply year to date and carrying bonds that have yielded above 16%, CoreWeave is Oracle’s stressed mirror image. Its earnings trajectory and debt refinancing capacity will tell investors how much room the broader AI credit story has left.
Microsoft (MSFT). Amazon and Microsoft fund AI expansion mainly from internal cash flows, giving them a balance sheet edge over debt-reliant Oracle and CoreWeave. Every dollar Oracle’s credibility loses is a dollar Microsoft’s cloud pricing power gains.