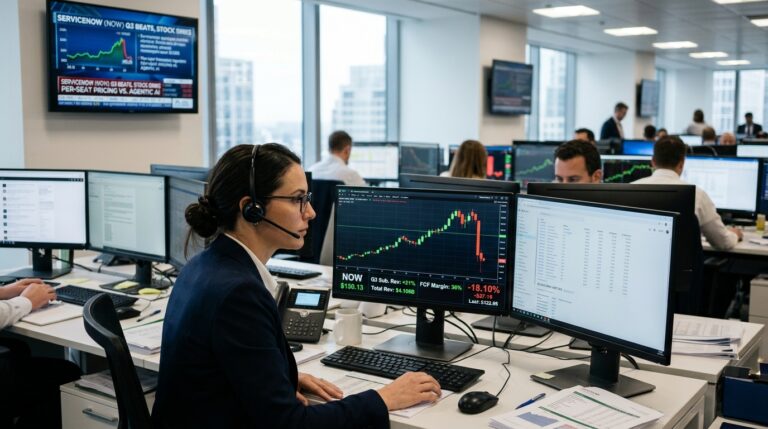
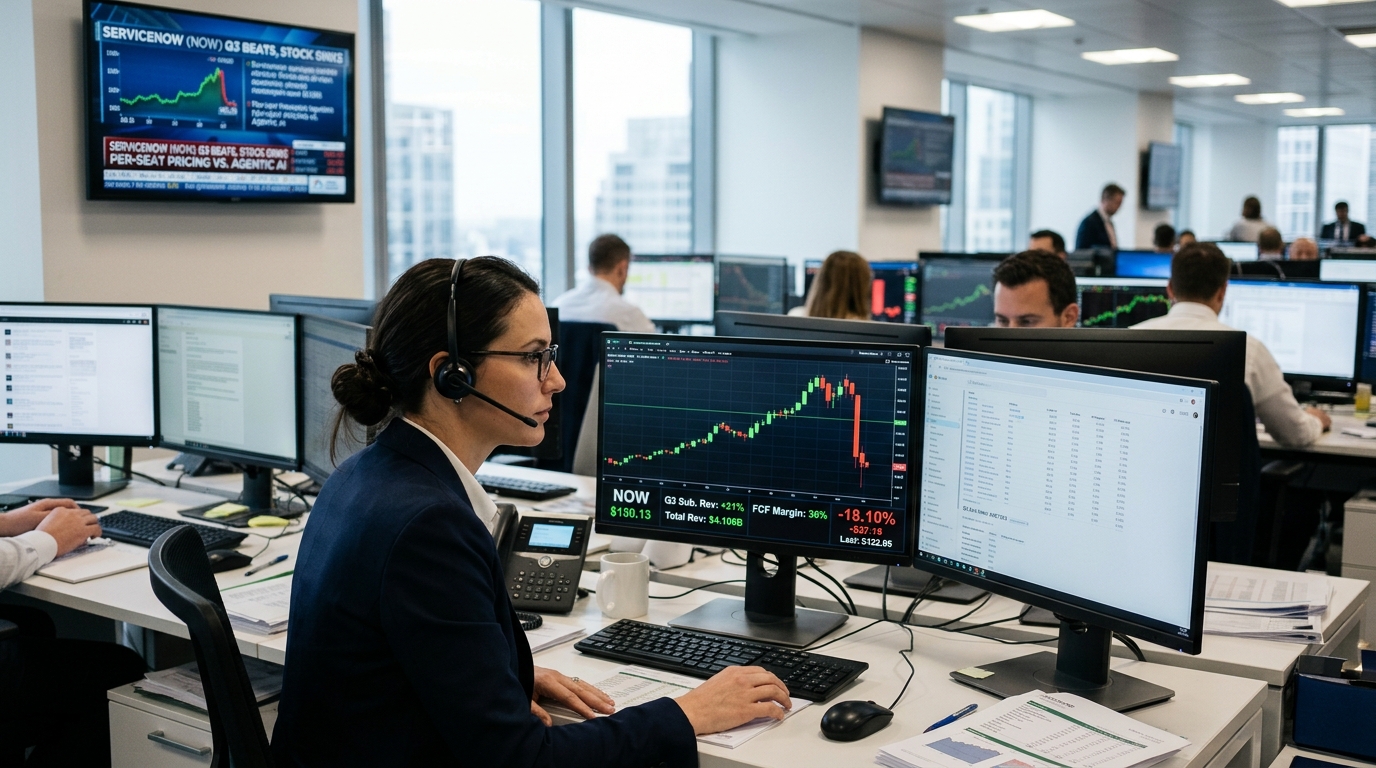
ServiceNow reported Tuesday night that subscription revenue rose 21%, total revenue hit $4.106 billion beating consensus, and management raised its full-year free cash flow margin target to 36%. Then the stock fell about 18%.
Shares closed the regular October 28 session at $150.13. After hours, the stock traded around $122.95, down $27.18 or 18.10%. By this morning, ServiceNow was trading near $122.95 with a market capitalization around $155 billion. The question investors need to answer is not whether management executed. They did. The question is whether the pricing model that built this company still works in an agentic AI world.
The Bull Case: This Is Simply a Cheap, Fast-Growing Company
The numbers are hard to dismiss. ServiceNow beat the high end of its Q3 guidance on subscription revenue, cRPO, and operating margin, with cRPO growing 21% in constant currency, 100 basis points above guidance, and operating margin reaching 32.5%, 150 basis points above guidance. The company reported a 98% renewal rate and ended the quarter with 680 customers generating more than $5 million in annual contract value, including 31 additional customers surpassing $20 million in ACV over the past year.
AI monetization is not speculative. ServiceNow raised its 2026 AI annual contract value target to $1.7 billion, up from $1 billion at the start of the year, and management reported that year-to-date agentic AI consumption in production had increased 13-fold from a year earlier. AI net new ACV rose 65% year over year.
The pricing transition ServiceNow is navigating is not unique to one vendor. Salesforce is simultaneously running three live Agentforce pricing models, reflecting how genuinely difficult it is to translate agentic work into a billing structure.
The trailing P/E ratio now stands at roughly 93 times, below a level some data services show for recent history. For a company growing revenue at 21% with a 98% renewal rate and $29.7 billion in total RPO, that contraction is not obviously deserved.
The Bear Case: Per-Seat Pricing Is Broken
The market’s verdict may be less a panic and more a structural reset. The core anxiety is straightforward: AI agents do not need seats. A seat represented an authorized human user, and seat count was a reasonable proxy for software’s organizational footprint. An AI agent’s marginal cost of additional work is near zero, meaning an agent handling 1,000 support tickets per day can handle 5,000 on the same infrastructure, while 5,000 human tickets would require 5,000 human seats.
ServiceNow has acknowledged the shift. Management has said that more than 50% of net new ACV is already coming from non-seat licenses, and that the new AI-native packaging can come with 20% to 30% average price lift. Salesforce’s Agentforce is priced at $2 per conversation, with no seat concept at all. Microsoft, whose Copilot suite runs inside the same enterprise workflows ServiceNow touches, can bundle AI capability at scale no independent vendor can match.
The earnings result itself handed bears a real number. ServiceNow’s Q4 revenue guidance range of $4.25 to $4.26 billion came in below the analyst consensus of about $4.36 billion. Q4 cRPO growth guidance of 18.5% in constant currency reflects a deceleration from Q3’s 21%, partly due to early renewals in Q3 that pulled deals forward and a higher on-premises mix. Management explained those dynamics carefully; the market did not wait for the explanation.
Where the Evidence Leads
The strongest bearish evidence is the Q4 revenue guidance gap, not the EPS miss. The company did not raise full-year subscription revenue guidance by the full Q3 beat, passing through only a portion of the outperformance. At a premium valuation, a partial pass-through reads as a signal that growth headroom is compressing, not expanding. The strongest bullish evidence is the $1.7 billion AI ACV target and the 13x consumption surge, which suggest the transition to outcome-based pricing is proceeding faster than the stock price reflects.
CEO Bill McDermott noted that more than 50% of net new business is already non-seat-based, and AI-native SKUs carry 20% to 30% average price lift, which is precisely the answer to the bear case. If that figure is real and durable, the per-seat concern dissolves. If it is aspirational, the Q4 guidance gap is the leading indicator.
What Could Change the Debate
Watch Q4 cRPO closely when ServiceNow reports in January. If the 18.5% constant-currency guidance proves conservative the way Q3 guidance did, the bull case rebuilds quickly. If it lands at or below guidance while Salesforce and Microsoft report accelerating Agentforce and Copilot consumption numbers, the structural reset deepens.
The more compelling side today, on balance, belongs to the bears, but narrowly. A two-cent EPS miss does not erase 21% subscription growth or a 98% renewal rate. What it does is remind investors that at roughly 93 times trailing earnings, ServiceNow needed a clean beat and clear acceleration. It delivered neither. The stock is not broken. The pricing model it was built on is being renegotiated in real time, and the market just sent that invoice.