October 25, 2026
Bonus Content: Blue Owl’s 39% Withdrawal Rate in Its Tech Fund Is the Number That Matters Thursday
Dear Reader,
I don’t trust Sam Altman at all …
And neither should you.
Because my research tells me he is hiding something …
Something so potent, so revealing …
It could spark the biggest monetary crisis of our lifetime.
Worse than the Dot-Com Crash …
The housing market collapse …
Even the Great Depression …
That’s why I suspect he’s using every tool at his disposal to keep this from getting out.
But on Dec. 18, around 4 p.m. …
He will be forced to reveal a document that’s currently confidential.
When he does, it will immediately trigger a $40 trillion wealth shift …
Altman himself has even said …
“Someone is going to lose a phenomenal amount of money … And a lot of people are going to make a phenomenal amount of money.”
To make sure you’re on the right side of this divide, click here.
Sincerely,
Nilus Mattive
Nilus Mattive
P.S. Look, if you wait for OpenAI to go public before you act … you’ll be too late.
Altman is expected to drop this bombshell on Dec. 18 …
Weeks before a potential IPO.
So please, don’t hesitate.
Watch this video to find out how you can protect yourself.
Blue Owl’s 39% Withdrawal Rate in Its Tech Fund Is the Number That Matters Thursday
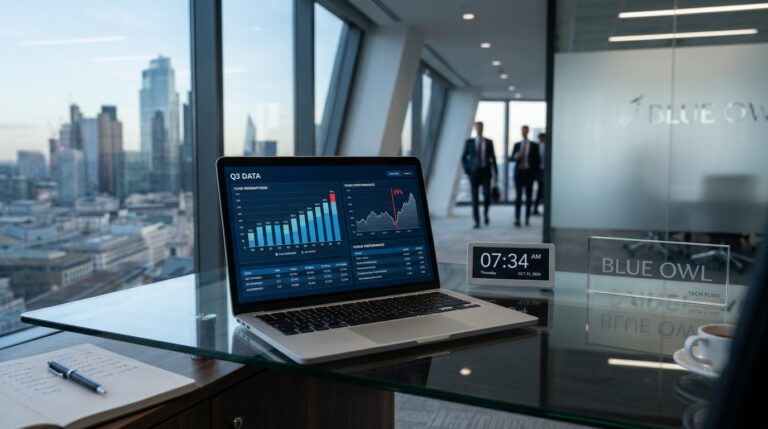
Blue Owl Capital reports Q3 results before the open on Thursday. The headline AUM number, the fee revenue, the dividend coverage at OBDC, none of those will tell investors what they actually need to know. The number that matters is 39.
That is the percentage of shares investors tried to redeem from Blue Owl Technology Income Corp. (OTIC) in Q3. Investors sought to withdraw about $1.1 billion, equivalent to 39.0% of shares, broadly unchanged from the $1.1 billion, or 38.1%, requested in the previous quarter. Blue Owl again capped withdrawals at 5%. The queue did not shrink. Thursday’s report will show whether that changes.
The Bull Case: A Structure Working Exactly as Designed
Start with what bulls have right. Investors sought $4.2 billion of repurchase requests from Blue Owl’s two non-traded private credit funds in Q3, down from $4.7 billion in Q2 and $5.4 billion in Q1. At the flagship $35.1 billion OCIC fund, repurchase requests fell to 16.8% of shares from 18.8%. That is a meaningful improvement at the larger vehicle.
Most requests at Blue Owl come from investors resubmitting tenders that went unfilled earlier. Management has said the group requesting redemptions was largely unchanged from the prior quarter, with very limited new participation. For the second quarter in a row, more than 90% of OCIC shareholders requested no redemptions at all. That is not a run on the fund. That is a concentrated minority working through a backlog.
Bulls also point to the credit fundamentals. Blue Owl wrote in a letter to shareholders that the results “underscore the disconnect between the market’s fears of AI disintermediating software and OTIC’s resilient credit fundamentals.” OCIC reported $11.2 billion of available liquidity as of August 31, 2026, across cash, undrawn debt, and other sources, giving management ample room to honor the 5% cap without distressed asset sales. And OTIC will have provided approximately $440 million of liquidity, or about 35% of original tender requests, within six months. That is not zero. The 5% limit is doing what it was designed to do: pace outflows against the natural rhythm of loan repayments.
The Bear Case: OTIC Is Not Improving
The bear case is more specific, and harder to dismiss.
OTIC’s technology exposure and concentrated investor base have contributed to its unusually high repurchase request levels, and the fund has said it has a more significant Asian shareholder base than Blue Owl’s other wealth-management products. The 39% request rate was well above the roughly 10% to 17% range recorded by several of the largest non-traded BDC managers during the third quarter. Blackstone’s private credit fund was about 10%. Apollo Debt Solutions BDC reported about 14.7% of shares requested. Every major peer is seeing demand to exit decline. OTIC is not.
The structural reason matters. Software has been among the most reliable cash-flow businesses of the past decade, with recurring subscription revenues, high margins, and low capital needs, making it attractive to direct lenders. Yet software firms’ revenues are now highly vulnerable to AI, which can both substitute for existing products and lower development costs, reducing barriers to entry and intensifying competition. BDCs as a group hold roughly $115 billion of lending exposure to software firms, about a fifth of all their lending, and over 80% of their fast-growing technology portfolios. OTIC is more concentrated in exactly that risk than almost any comparable vehicle.
The pressure on software lending is not hypothetical. Salesforce’s own Dreamforce pitch shows how the largest enterprise software vendors are racing to reframe their products around AI agents before subscription revenue erodes.
If withdrawals come faster than loan repayments and cash on hand, managers may have to sell assets at a discount, which can pull down stated values and sometimes lead to limits on withdrawals. At 39% demand to exit against a 5% cap, the backlog keeps growing each quarter. That is not a resolved problem. It is a deferred one.
Where the Evidence Leads
The two funds tell genuinely different stories. OCIC’s trajectory is encouraging: new redemption participation is minimal, and the absolute figure has fallen three quarters in a row. The developments add to signs that private credit is potentially moving past the worst of redemption pressures as investor sentiment improves and asset managers work through the backlog of unfulfilled withdrawal requests.
OTIC is different. The flat redemption rate, quarter over quarter, at a level triple the industry norm, reflects something specific to the technology lending thesis rather than general retail investor anxiety.
Thursday’s Q3 report will give the first full quarter of marks on the underlying loan book since retail investors began queuing to exit. The verdict on OTIC’s credit quality matters far more than the AUM line. If non-accruals tick up in the technology portfolio, the bear case stops being theoretical. If they hold, Blue Owl’s argument, that the market is wrong about software credit, gains real evidence. Watch the non-accrual rate, not the withdrawal rate. That is the number that actually moves the stock.