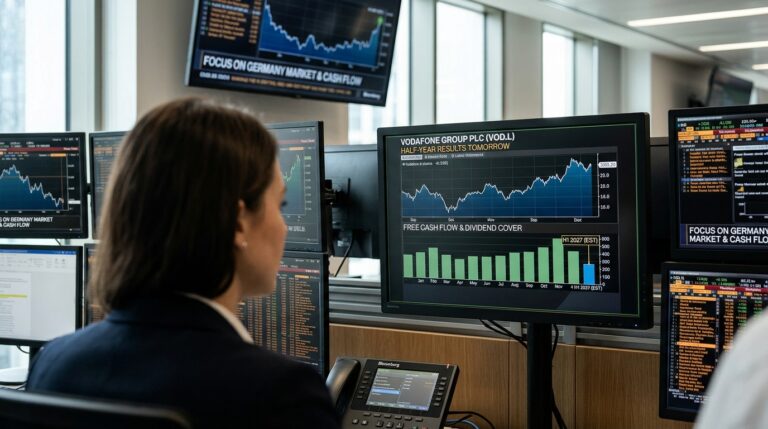
Vodafone’s half-year results land Tuesday, November 10, and the story investors should be tracking is not headline revenue. It is whether the free cash flow machine is running well enough to sustain a progressive dividend and fund the buyback that management has committed to.
The backdrop is better than it has been in years. In its Q1 FY27 trading update, Vodafone said organic service revenue grew 5.2% and organic adjusted EBITDAaL rose 6.2%, driven by broad-based growth across all segments, including improved retail revenues in Germany and strong commercial momentum in the UK. That is the best operational read Vodafone has delivered in a while. Tuesday is the first full half-year look at whether the momentum has lasted.
Germany: The Number That Decides Everything
Germany remains one of Vodafone’s most important markets, accounting for 32% of group service revenue in Q1 FY27. For years it was the group’s open wound: a market dragged down by regulatory pressure on cable TV bundling and fierce mobile competition. That is changing. Vodafone reported German organic service revenue grew 1.3% in the fourth quarter of FY26 and 1.2% in the first quarter of FY27, helped by higher wholesale and fixed-line revenue, stronger Consumer broadband pricing and Business digital services.
Two consecutive quarters of modest positive growth after a prolonged decline is a signal, not a verdict. Vodafone also said it lost 85,000 mobile contract customers and 98,000 broadband customers in Germany in Q1 as competitive pressure persisted. Tuesday’s H1 figures need to show that subscriber losses are narrowing and that the revenue line is not dependent entirely on wholesale pricing. If German service revenue posts a third successive quarter of organic growth, the turnaround starts to look structural rather than seasonal.
VodafoneThree: Integration Costs vs. Synergy Delivery
The UK merger is the other swing factor. Vodafone has described VodafoneThree as the UK’s biggest mobile operator, with 28.8 million customers, and its service revenue contribution has helped consolidate the UK as the group’s second-biggest operation after Germany. Early integration metrics are encouraging: VodafoneThree has said its network sharing upgrade is already live on more than 10,000 sites.
But integration costs are climbing. In its FY26 results materials, Vodafone said restructuring and integration costs are expected to peak at around €0.7 billion in FY27, including around €0.4 billion tied to VodafoneThree. Vodafone has also guided investors to £700 million of annual cost and capex synergies by FY30. The gap between near-term cost and long-term benefit is real, and Tuesday’s H1 numbers will offer the clearest read yet on whether the synergy timeline is holding.
The Income Question
For yield-oriented investors, the core question is straightforward: does free cash flow cover the payout? Vodafone reported adjusted free cash flow of €2.621 billion in FY26, and the company committed to a progressive dividend policy, declaring a total dividend per share of 4.6125 eurocents for the year, a 2.5% increase. In its Q1 FY27 update, management pointed to FY27 guidance of adjusted EBITDAaL of €13.0 billion to €13.3 billion and adjusted free cash flow of €2.6 billion to €2.9 billion.
At current share prices, the implied yield is meaningful for a large-cap European telecom. The risk is that the range’s lower bound, €2.6 billion, leaves little margin after dividends and buybacks if Germany stalls again or UK integration costs overshoot. Watch Tuesday’s H1 free cash flow figure closely. It tells you more about the dividend’s durability than any service revenue line.
Safaricom and Africa: The Underappreciated Driver
One element most investors underweight: Africa. In its Q1 FY27 trading update, Vodafone reported Africa organic service revenue growth of 12.6%, and Vodafone has said the Safaricom transaction closed on 30 June 2026. Tuesday will be the first half-year result to reflect consolidation of Safaricom following that closing. That adds complexity to the group accounts but also adds a genuinely fast-growing cash-generative business that improves the long-run free cash flow story.
The Wealth-Building Takeaway
Telecoms belong in income portfolios when three conditions align: a stable or recovering revenue base, manageable debt, and a dividend covered by cash flow rather than accounting adjustments. Vodafone is edging toward all three. In its Q1 FY27 update, management framed the main tests as Germany’s recovery, the UK integration of Three delivering synergies, and whether it can maintain its expectation of reaching the upper end of full-year guidance. A clean pass on all three would make the progressive dividend policy a credible multi-year income source, not merely a promise. Investors building for yield should watch Tuesday’s numbers before reaching a conclusion either way.