Hey,
I’m going to do something that may seem a little out of the “norm” these days…
I’m going to give you my #1 trade setup. For free.
It’s the same one I used to find winners like:
- 113% on GOOGL in under 2 hours.
- 240% on META in a single session.
I call it the “Opening Bell Breakout.”
It’s one simple setup I look for every morning. When it shows up…
I simply take the trade. And by 10 AM, I’m done.
I’ve put all the details on how it works in a simple, no-fluff guide.
No credit card required. No strings attached.
>> Get Your FREE “Opening Bell Breakouts” Trade Guide Here
This guide shows you the exact 15-minute window I trade, and how to spot the same setups the big funds are watching.
It’s yours for free.
Thomas Wood
P.S. This isn’t a 100-page novel. It’s a short, actionable guide you can read in about 10 minutes and put into action by tomorrow morning. Get it here.
Rising Yields Are Hurting European Banks, Not Helping
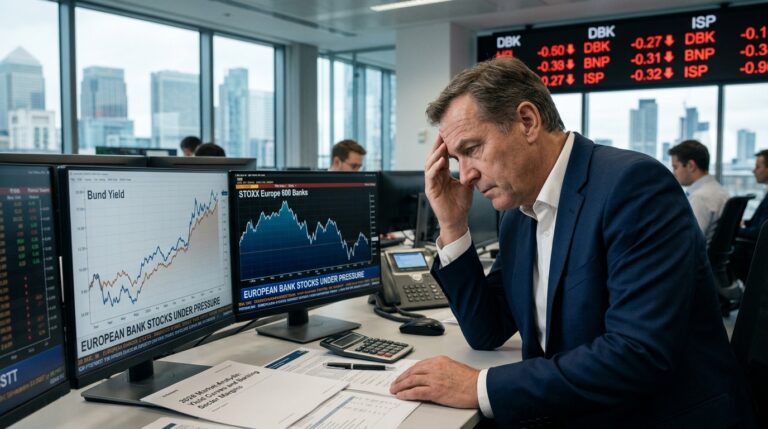
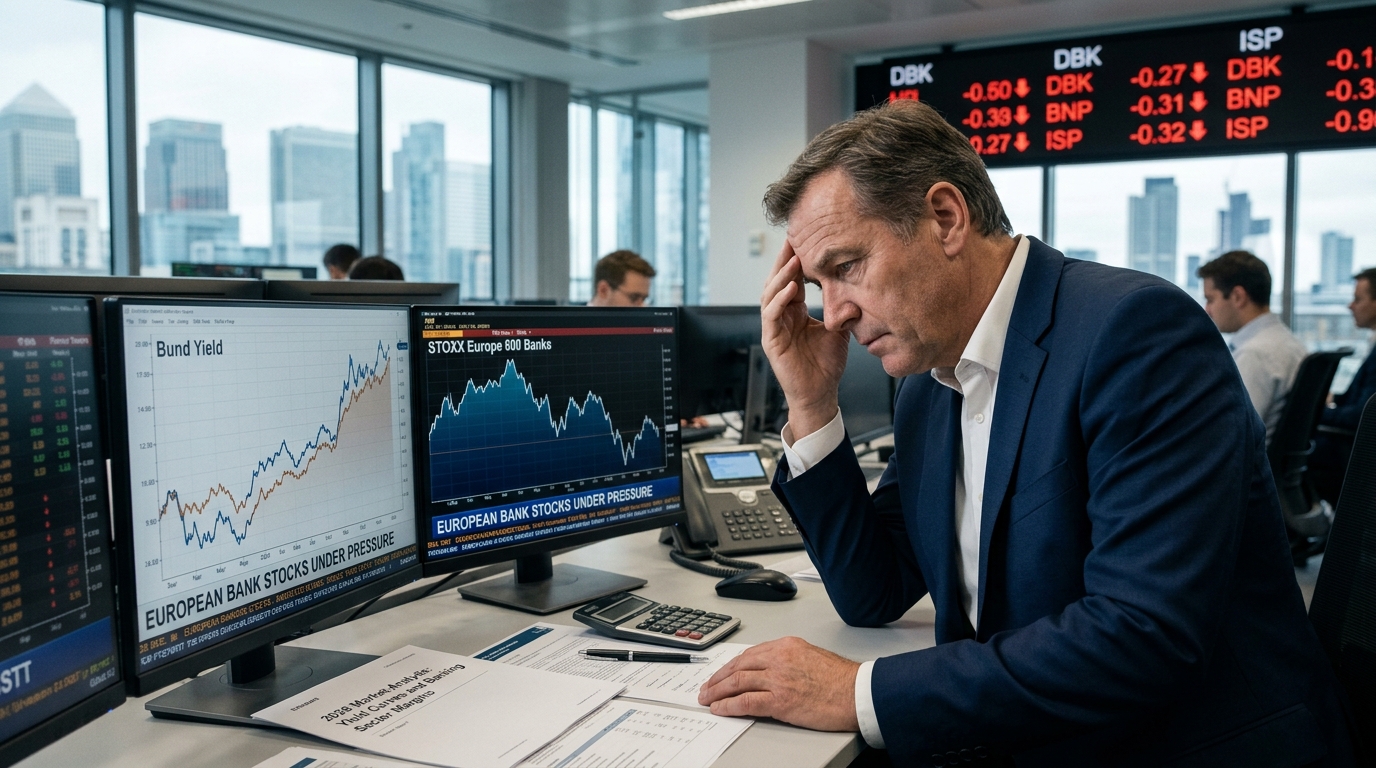
For most of this year, the investment case for European banks rested on one clean logic: higher rates mean fatter lending margins, and fatter margins mean better earnings. Investors bought it. European banks delivered an exceptional stock market performance in 2025, with the STOXX Europe 600 Banks index up 67% in euro terms. The trade looked intact heading into Q4. Then October 1 arrived.
European shares started the final quarter of the year on a downbeat note, with heavyweight banks marking sharp declines as global government bond yields hit multi-year highs. The pan-European STOXX 600 fell 1.3% to close at 626.65 points, while the banking sector index plunged about 3.7%. By the end of the week, the benchmark was on course for its worst weekly performance since mid-April, nursing a decline of nearly 2%.
The bond market context matters enormously. The 10-year French OAT approached the psychologically important 5% threshold, while the gap between French and German yields widened above 130 basis points, the largest since 2012. Germany’s 10-year Bund yield touched 3.6526% in late September, a level not seen since before the eurozone debt crisis. Data also showed German inflation accelerated to 3.3% in September, adding to expectations that the ECB may need to maintain a restrictive policy stance.
The Bull Case: Fundamentals Still Hold
The optimistic reading is that the sell-off was technical and sentiment-driven rather than a genuine reassessment of earnings power. Europe’s largest banks showed surprising resilience in the first half of 2026, with broad-based growth across their business segments. BNP Paribas delivered first-half revenue growth of 10.2% and a 21.3% increase in group pre-tax profit.
European banking entered Q4 2026 navigating a crossroads, with the ECB having raised its deposit facility rate to 2.50%, which continues to support net interest income, the sector’s core earnings engine. Bulls would also note valuation. BNP Paribas is currently trading at a price-to-book of about 0.8x, below the value of its own assets, with analyst consensus pointing to 23.2% upside, the highest in the peer group. That is the case for owning the dip.
The Bear Case: The Correlation Just Broke
The more troubling possibility is that this week revealed a structural shift, not noise. Rising government bond yields reduce the value of the sovereign debt that banks hold and raise fears about loan quality, outweighing the benefit of higher lending margins. Lenders with predominantly floating-rate asset books stand to benefit most from renewed tightening, while banks with fixed-rate portfolios may be negatively impacted. That distinction, which analysts largely glossed over during the rally, is now forcing a reassessment.
Nominal 10-year government bond yields have risen materially across major developed markets, but in Europe, higher energy prices, renewed inflation concerns, expectations for additional monetary tightening and sovereign fiscal uncertainty have played a more prominent role. That last item is where BNP Paribas is specifically exposed: France’s draft 2027 budget arrived against rising borrowing costs, with the 10-year OAT-Bund spread widening sharply and exceeding 130 basis points, the highest since 2012. The primary residual risk for European banks in 2026 is no longer monetary policy but the credit channel.
Where the Evidence Leads
Rising sovereign yields now pose a double-edged threat: they boost net interest income but compress bond portfolios and potentially weigh on credit demand. For most of 2026, investors focused entirely on the first half of that sentence. The events of this past week forced attention onto the second half.
The bear case carries more weight right now. The rally in European banks was built on a clean rate-positive story. That story has not collapsed, but it has become materially more complicated. Investors are now questioning whether higher interest rates are beginning to hurt borrowers as much as they help lenders. French fiscal anxiety, energy-driven inflation, and a German Bund yield at multi-year highs are not individually fatal to the thesis. Together, they introduce enough uncertainty to justify a more cautious position near term.
The names to watch most closely: BNP Paribas for its direct exposure to French sovereign spreads; UniCredit and Santander for credit quality as borrowing costs bite into their retail books. A stabilization in euro-area yield spreads, or any signal that the ECB is approaching the end of its tightening cycle, would be the clearest catalyst to revisit the bull case with conviction. Until then, the presumption that higher yields automatically benefit European bank stocks deserves to be retired.