Two things happened this week that, taken separately, look like isolated market events. Together, they describe the same problem: traders are pricing positions for yield and ignoring what it will actually cost to get out.
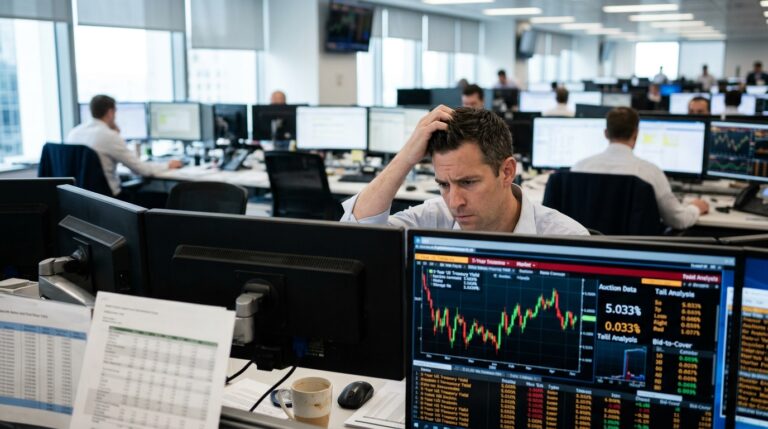
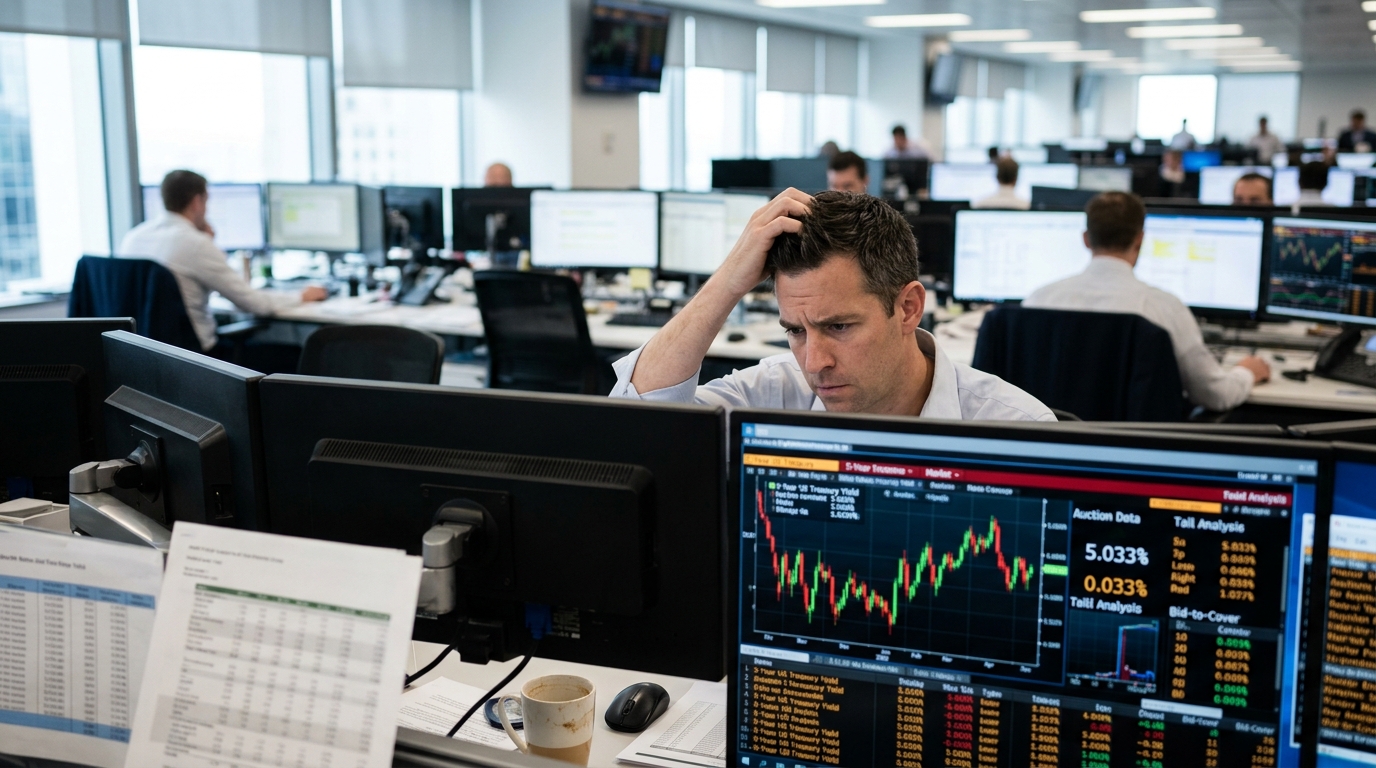
The auction told you something real. Wednesday’s $70 billion 5-year note auction cleared at 5.033%, producing the second-largest tail on record and the weakest bid-to-cover since December 2018. That 3.1bp gap between the when-issued rate and the clearing yield was not noise. The auction tailed by 3.1 basis points as participation softened, leaving primary dealers with about 15.8% of the offering, roughly $11 billion in supply the market didn’t want, cascading pressure across the curve. Thursday’s 7-year was not a clean all-clear either: $44 billion on offer, bid-to-cover of 2.42 against an average around 2.49, with indirects at 57.2% against an average around 64.6%. But the tail was materially larger than 0.7bp, it was about 3.5bp. Two consecutive soft auctions. The structural demand-destruction argument is no longer easy to dismiss.
The 5-year maturity sits in a particularly sensitive spot on the yield curve. It is long enough to embed meaningful inflation expectations but short enough to reflect near-term policy assumptions. Dealers use it heavily for hedging, which means pricing dislocations at this tenor can ripple outward into mortgage rates, corporate borrowing costs, and portfolio construction across fixed income.
Now look at where $20 billion has parked itself. Total assets under management across multiple ETFs built around S&P 500 box spreads is in the tens of billions, with Alpha Architect’s BOXX around the mid-teens of billions as of mid-September 2026. Once considered a clever but complex strategy reserved for high-end institutional clients and the biggest banks, the trade has gone mainstream as ETFs package it into low-cost vehicles and advisors get more comfortable with options-based strategies. Options-market data providers have reported outstanding notional value in S&P 500 box spread trades around $146 billion as of mid-September 2026, with average daily notional trading over the prior month above $2.3 billion, up about 26% from a year earlier.
The appeal is straightforward: S&P box spreads have recently screened at yields north of 4% for short-dated expiries, competing with cash alternatives. Three new competitors launched in 2026 alone, with lower fees, including XBOX from Roundhill. The category is crowding fast.
Here is where traders need to be honest with themselves. Volume is not depth. Some portfolio holdings may be valued on the basis of factors other than market quotations, and this occurs more often in times of market turmoil or reduced liquidity. A box spread ETF is a synthetic construct, not a Treasury bill. Its exit in a dislocated options market is a different problem than redeeming a T-bill.
The same pressure is already visible in small caps. IWM saw $3.3 billion in weekly outflows as the Russell 2000 fell 7.3% from mid-August, marking its second-largest weekly withdrawal of 2026 and third-largest in nine years. The Russell 2000 has been estimated to have roughly 32% of its debt tied to floating rates, compared to about 6% for the S&P 500, making it a direct transmission point for every basis point the curve moves higher. The 10-year Treasury yield has traded around 5.11% in September 2026, near the highest levels seen since 2007.
The action plan is mechanical, not predictive. For any position in IWM or leveraged ETFs, ask one question before adding size: at what price can you actually exit, and over how many sessions, given current average volume? IWM’s daily average volume has dropped sharply as yields spiked. For box-spread ETF holders, the question is what the bid-ask spread looks like in a risk-off market when everyone reaches for the same exit. Reduce position size to what you can liquidate in a single session at a reasonable spread. If that number is uncomfortable, the position is already too large for the market you are actually trading in, not the one you assumed you were.