Editor’s Note: For nearly two decades, Whitney Tilson managed money for wealthy investors – growing a hedge fund launched from his spare bedroom into a firm running more than $200 million. Today, at least five billionaires follow his daily research notes. Now, he’s revealing what he believes is Warren Buffett’s final “hidden” legacy move – and three ways to get in early before a newly-IPO’d power company lights the blue touchpaper. See below for the details…
Dear Reader,
I think we can all agree Warren Buffett is one of the greatest investors who ever lived.
He compounded his money at around 20% a year for six decades…
By turning a dying textile mill into the most famous holding company on Earth – one valued at $1 trillion today.
But hardly anyone is paying attention to what I believe is his final – and least understood – bet in the market.
The details are all laid bare in a story ex $200M hedge fund firm manager Whitney Tilson calls “Project Vulcan”… and what it says about Buffett’s last bet is truly astonishing.
For years, Berkshire has been quietly building a dominant position in a niche type of energy production to fuel the AI build-out…
A fuel source The Economist says is “better than nuclear.”
And one the International Energy Authority predicts could be flooded with over $2.5 trillion of investment in the next decade.
It’s been overlooked by mainstream investors for years.
But an imminent power station switch-on – slated for this October – could be about to light the blue touchpaper in this sector.
And now Whitney is sharing all the details on this story… including three ways you could potentially profit before the big money piles in.
Get the full details on Whitney’s 3 “Project Vulcan” plays now.

Sincerely,
Matt Weinshenck
Publisher and Director of Research, Stansberry Research
P.S. The clock started ticking on this opportunity the moment Buffett handed the keys to his empire over to his hand-picked CEO. Watch my presentation now so you don’t get left behind.
OpenAI’s $278 Billion Hole Is Financeable. Or It Breaks Everything.
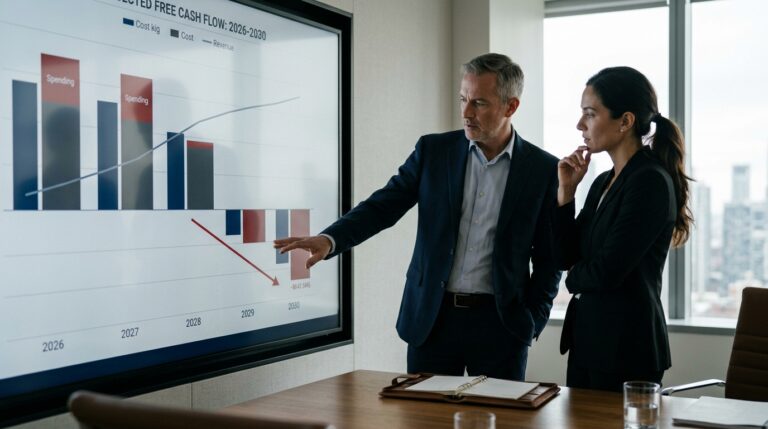
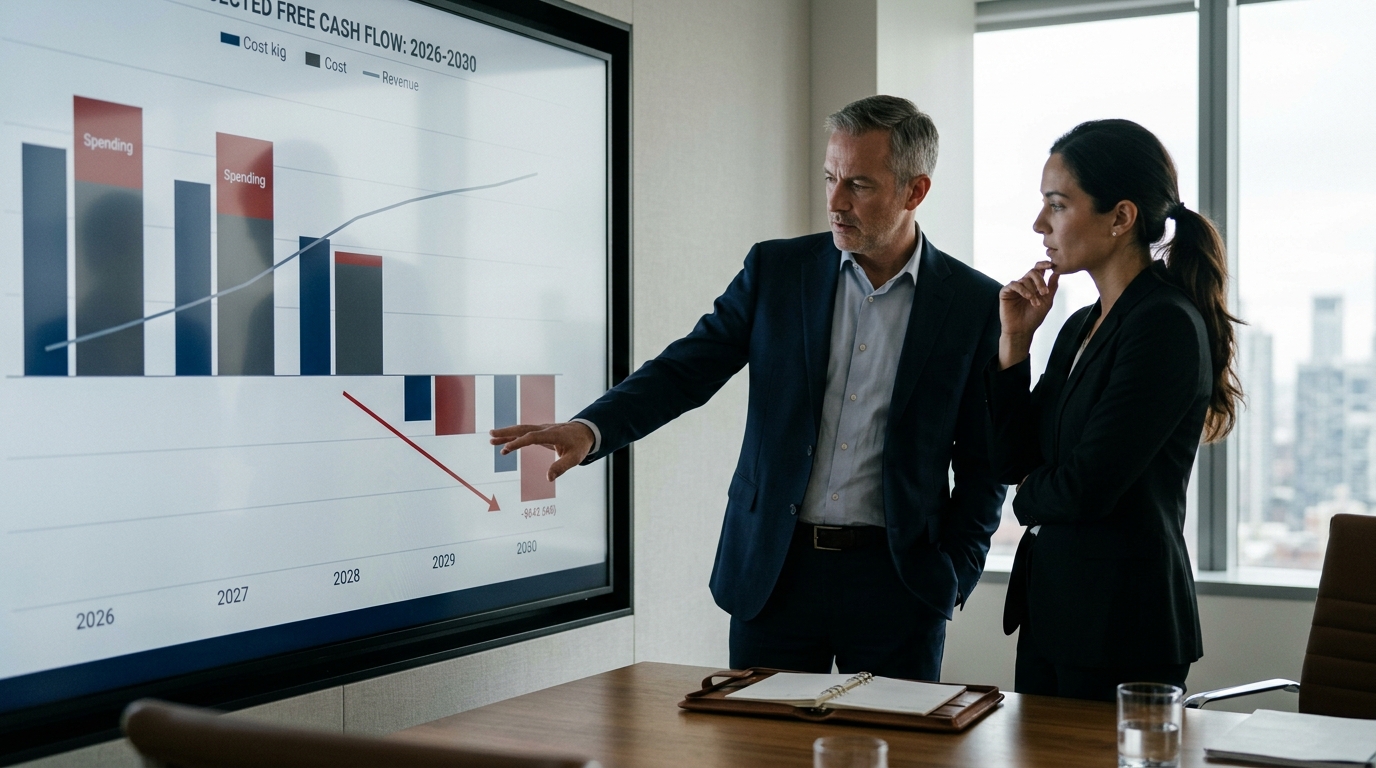
The figure the entire AI infrastructure trade has been missing finally arrived Friday evening. OpenAI expects its negative free cash flow to reach $278 billion from 2026 to the end of 2030, according to the Financial Times, citing materials shared in July as part of a major computing deal. The company projects revenue will increase from $36 billion in 2026 to $350 billion in 2030, yet expenses are expected to vastly outpace those gains. That gap is not a rounding error. It is the defining variable for Nvidia, Oracle, CoreWeave, Microsoft, AMD, and Broadcom, every company whose order book depends on OpenAI following through.
The Bull Case: A Tenfold Revenue Jump Covers the Math
Start with what the numbers actually say before assuming they spell disaster. OpenAI forecasts cumulative revenue reaching roughly $840 billion through the end of the decade, according to Reuters, citing the Financial Times report. Against $278 billion in cumulative negative free cash flow, that is a painful but survivable ratio for a company still in its infrastructure construction phase. Amazon ran negative free cash flow for years while building AWS. The question is whether OpenAI’s revenue trajectory is credible.
There is evidence it is, but the cleanest claim here is the one we can verify. OpenAI said on March 31, 2026 that it closed a funding round with $122 billion in committed capital at an $852 billion post-money valuation, giving it a runway that buys time for the revenue curve to catch up with spending.
The vendor side reinforces the bull argument, with one caveat: not all of the commonly cited vendor totals are presented as hard contractual obligations on identical terms. OpenAI has made more than $1 trillion worth of financial obligations tied to AI infrastructure, including a $38 billion computing deal with Amazon, and large commitments with Oracle and SoftBank plus semiconductor supply arrangements with Nvidia, AMD and Broadcom, as the Associated Press reported. Broadcom separately announced a multi-year collaboration with OpenAI to deploy 10 gigawatts of OpenAI-designed AI accelerators, with deployments targeted to start in the second half of 2026 and to complete by the end of 2029. Suppliers at that scale can become informal creditors.
The Bear Case: $278 Billion Implies a Single Point of Failure
The bear argument is structural, not cyclical. Every dollar of that $278 billion shortfall must be financed somewhere. A separate Reuters report summarizing the Financial Times presentation indicates OpenAI’s projected negative free cash flow spans 2026 through 2030, but the presentation excerpts reported publicly do not, on their own, confirm exactly when the March 2026 capital could be exhausted under management’s spending path. The Financial Times reported earlier this week that OpenAI held talks with investors that could value it at about $1.2 trillion ahead of a potential listing, but there is no reliable, on-the-record statement to support the claim here that CEO Sam Altman said the company would not go public in 2026 because of concerns about AI safety.
The counterparty concentration problem runs deeper than OpenAI’s own balance sheet. When a Wall Street Journal report in late April said OpenAI had missed internal targets for users and revenue, Reuters reported that shares of AI-exposed firms sold off, including CoreWeave down more than 7% in a session, with SoftBank down nearly 10% in Tokyo. The specific claim that Oracle fell more than 7% on that news is not consistently supported by contemporaneous reporting, which generally described a mid-single-digit decline. That reaction had little to do with Oracle’s or CoreWeave’s own operations. It reflected pure counterparty exposure. Some commentary has also highlighted lender caution tied to supplier balance sheets and heavy customer concentration. When lenders start treating a customer’s financial health as a credit risk for its suppliers, the loop tightens in ways that are hard to unwind.
If OpenAI doesn’t survive, it could walk away from large spending commitments across the AI industry, putting other highly leveraged players such as CoreWeave in jeopardy. CoreWeave’s quarterly filing disclosed that, under a master services agreement, OpenAI has committed to pay CoreWeave up to approximately $11.9 billion through October 2030, and that CoreWeave’s business is subject to counterparty credit risk that is heightened when a substantial portion of revenue is driven by a limited number of customers.
Where the Evidence Leads
The bull case requires OpenAI to execute a roughly tenfold revenue increase in four years while continuously accessing private capital markets at rising valuations, with no public market exit guaranteed. The bear case requires only that one of those conditions fails. Revenue misses its target, a funding round stalls, or a key model launch disappoints, any single break in the chain ripples directly into Oracle’s cloud revenue, CoreWeave’s debt service, Nvidia’s order flow, and Broadcom’s custom silicon contracts.
The evidence that tilts the scale: the Financial Times report, as summarized by Reuters, says OpenAI expects computing power and infrastructure alone to cost roughly $856 billion over the period, against cumulative projected revenue of $840 billion. The company is, in its own projections, spending more on compute than it expects to collect in total revenue. That is not inherently fatal, capital-intensive businesses do it during buildout, but it leaves no margin for error, and it means every stock that trades on OpenAI’s success is implicitly short volatility on OpenAI’s execution.
Watch two things: the velocity of OpenAI’s revenue in Q4 2026 relative to its $36 billion annual target, and whether the next funding round closes above or below the $1.2 trillion valuation figure now circulating. A round at a discount, or one that stalls, would reset the entire infrastructure supply chain before any earnings are reported.