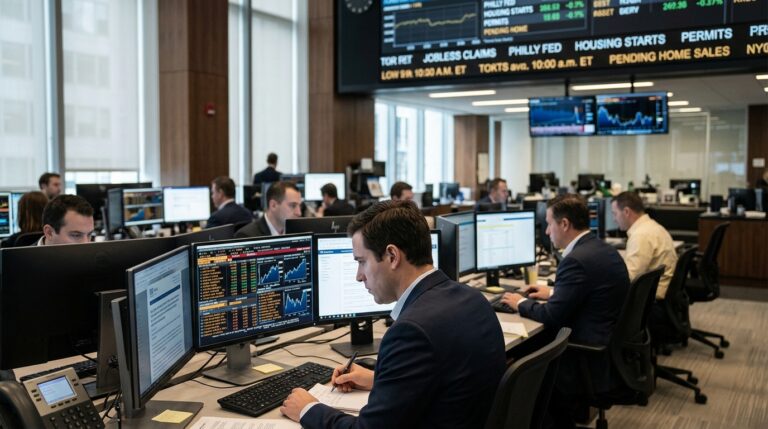
The Federal Reserve lifted its benchmark federal funds rate to a range of 3.75% to 4.00% on Wednesday, and this morning the economy starts talking back. Five releases land before 10:00 a.m. ET, and each one carries more weight than it normally would on a Thursday in September.
The Schedule
- 8:30 a.m. ET: Initial jobless claims, Philadelphia Fed Manufacturing Index, August housing starts, August building permits
- 10:00 a.m. ET: NAR pending home sales
Together, these reports cover the housing market, labor conditions, and regional manufacturing activity, and collectively they may influence Federal Reserve policy expectations and broader market sentiment. Under normal conditions that would be routine. Today it is not routine.
Why This Data Batch Is Different
The dot plot showed that 16 of 18 participating policymakers anticipate at least one additional rate increase before the end of the year. With four participants penciling in two more hikes for the year against just two seeing Wednesday’s move as the last one needed, the spread of views signals scope for volatility around upcoming data. Every number released this morning feeds directly into that debate.
The Fed raised the federal funds target range by 25 basis points to 3.75%-4.00%, its first increase since 2023, with the FOMC citing an economy that is expanding at a solid pace even as inflation stays elevated. The word “solid” now needs defending.
What the Forecasts Show
On the labor side, the most recent initial claims reading was 206,000 for the week ending September 5, loosely aligned with expectations and holding a trend of low claim counts since dropping to a near 60-year low of 189,000 in mid-July. Consensus for today’s number sits near that same range. A meaningful jump would be the first sign that rate-sensitive employers are beginning to pull back hiring decisions.
The Philly Fed is the more volatile read. Consensus forecasts the index at 31.3 versus a prior reading of 47.4, which would represent a sharp deceleration in mid-Atlantic manufacturing conditions. That drop matters because it follows a deteriorating signal from New York: the Empire State Manufacturing Index fell 13 points to 7.6 in September from 20.6 in August, missing expectations of 14.75. Worse, the pace of input price and selling price increases accelerated from already elevated levels, with the prices paid index rising five points to 63.1, edging above its recent four-year high reached earlier this year. Slowing activity plus rising prices is precisely the combination that pressures the Fed to keep hiking regardless of growth signals.
On housing, starts dropped 12.4% to a seasonally adjusted annualized rate of 1.239 million units in July, firmly below expectations. August starts are forecast at 1.320 million, a modest bounce. Building permits are expected at 1.400 million, down from 1.443 million prior. A second consecutive miss on either figure would signal that homebuilders have already adjusted to a world with a 4% funds rate, and now face another hike on top of it.
Sectors and Levels to Watch
XHB and ITB are the immediate pressure points. Both homebuilder ETFs price in permit and starts momentum, and the July starts collapse already left a mark. A weak August figure would test recent lows. XLI, the industrials ETF, carries exposure to the manufacturing deterioration visible in Empire State data and faces a compounding read from Philly Fed this morning.
On Treasuries, the unanimous vote and the median dot’s call for at least one more 2026 hike typically supports the dollar and pressures front-end Treasury yields higher. Stocks fell after Wednesday’s decision, the two-year yield and dollar rose, and the 10-year yield hovered around the psychologically significant 5% level. Soft data this morning could give the front end a brief reprieve. Hot data reinforces the case for another move, likely at the October or December meeting.
The Line That Matters
The dot plot suggests policymakers expect rates to remain higher for longer, with less room for easing over the next several years. That means this morning’s data do not just tell traders about August. They tell traders how much room the Fed has to pause. Watch claims for labor cracks, the Philly Fed headline against the 31.3 consensus, and housing permits for the first signal that builders have stopped pulling the trigger on new projects. Together, those three numbers will do more to shape October expectations than anything else released this week.