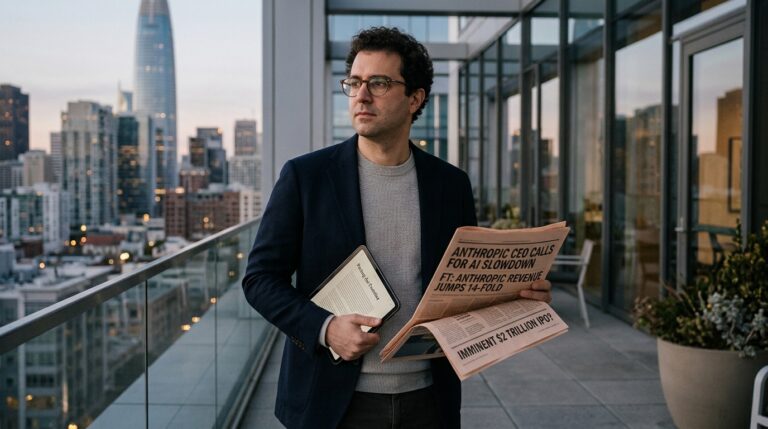
On Saturday, September 12, 2026, Dario Amodei published a roughly 3,800-word essay titled “We Must Pace the Frontier,” arguing that the AI industry needs to slow its rate of capability gains. The Anthropic CEO published the piece on his personal website, arguing that the industry needs to deliberately slow the rate at which it improves model capabilities. The next day, the Financial Times reported that Anthropic had told a select group of shareholders it would book a second consecutive quarter of adjusted operating profit, with gross margins above 80% before accounting for revenue shared with distribution partners (including Amazon) and the cost of training its models. The same report said Anthropic’s annualized revenue run rate was about $65 billion as of late July.
Both messages came from the same company. That tension is the central question every investor should sit with before October.
The Bull Case
The numbers Anthropic is circulating are extraordinary. Revenue surged more than 14-fold in the second quarter from a year earlier, reaching more than $11.5 billion, up from $787 million in Q2 2025 and $4.73 billion in Q1 2026, according to documents described in Bloomberg coverage. That is not a run-rate projection or a forward estimate; it is preliminary revenue already in the books.
The profitability signal matters more than the growth rate. Anthropic has told a small group of shareholders it expects to report an adjusted operating profit this quarter, which would mark a second consecutive quarter of adjusted operating profit as the company prepares to go public. Gross margins are described as above 80% before accounting for revenue shared with distribution partners such as Amazon and the cost of training its models. For a five-year-old lab that has previously reported multi-billion-dollar losses, that would represent a genuine structural turn, not accounting cosmetics.
Enterprise revenue tends to be higher margin and more durable than consumer subscriptions, which is part of why the quarter turned to adjusted operating profit even as infrastructure spending stayed heavy. Claude Code, the company’s developer agent product, has been a primary driver. Anthropic’s annualized revenue run rate reportedly exceeded $65 billion by the end of July, up from approximately $47 billion in May and about $9 billion at the end of 2025.
The Amodei essay, on this reading, is not a contradiction. A company demonstrating genuine operating leverage has the most to gain from an industry-wide slowdown. If competitors are forced to pace development while Anthropic is already generating adjusted operating profit, the safety argument and the competitive argument converge. That is a coherent strategy.
The Bear Case
The bearish case starts with the adjusted operating income metric itself. Positive adjusted operating income is a non-GAAP measure that does not by itself establish net profit or positive free cash flow. The measure can exclude costs including stock-based compensation. For a company planning to list at a rumored $2 trillion valuation, adjusted figures shown only to select shareholders are not the same as audited economics shown to every investor.
The eventual S-1 should clarify whether sales routed through cloud partners should be compared on a gross or net basis. That distinction matters enormously: public reporting has not established whether the $11.5 billion figure is presented on a gross or net basis, how cloud-distributed sales are treated, or how much came from subscriptions, API usage, and enterprise contracts.
Then there is the valuation. Anthropic’s reported $965 billion private valuation (from its May 2026 funding round) puts it in the company of the world’s largest public corporations. Secondary markets have been reported to imply a post-IPO value above $1 trillion, with some investor models reaching $2 trillion. A valuation near $2 trillion is hard to justify on today’s reported revenue alone.
Amodei’s call for a slowdown adds a different kind of risk. Slowing down development could save billions of dollars in model training costs, but it would also leave room for competitors to catch up. Critics have suggested the essay may also serve a competitive purpose. If public investors price the stock on 14-fold growth, they are implicitly betting that growth continues. The CEO’s own essay raises the probability that it doesn’t.
Where the Evidence Leads
The bull case is better supported right now, but only at a valuation well below $2 trillion. The operational progress is real: the company says it is on track for a second consecutive quarter of adjusted operating profit, it has described enterprise gross margins above 80% on a pre-partner-share and pre-training-cost basis, and it has reported a revenue trajectory that has compressed years of expected growth into months. Those are not projections; they are reported figures.
The bear case is harder to dismiss, though. The numbers being shared with shareholders remain preliminary and adjusted, the Amazon revenue-sharing structure has yet to be disclosed on a net basis in a public filing, and free cash flow has not been confirmed positive. The Information reported that Anthropic pushed its target for positive cash flow back to 2028. Paying $2 trillion for a company still burning cash requires confidence in a trajectory that Amodei himself just said should be slowed.
What Could Change the Debate
Reuters reported that Anthropic is seeking to raise as much as $100 billion at a valuation near $2 trillion, with Nvidia weighing up to $10 billion. The public S-1 will be the decisive document, providing audited revenue recognition, the gross-versus-net cloud revenue split, training cost disclosure, and free cash flow. Those figures will either confirm the profit momentum or reframe it.
Watch also for whether Amodei’s pacing proposals gain regulatory traction. A binding international agreement to slow capability development benefits a company already generating adjusted operating profit far more than one still racing to close a profitability gap.
The Verdict
The operational story is the stronger of the two claims right now. A company generating more than $11.5 billion in a single quarter, with margins described as above 80% at the gross level before partner revenue-share and training costs, is not a speculative bet on future technology. It is a functioning enterprise business. The equity deserves a premium valuation.
It does not deserve $2 trillion yet. That number depends on growth continuing at a rate the CEO just said the industry should abandon. Price the profitability, not the acceleration. The October listing will test whether public markets can make that distinction.