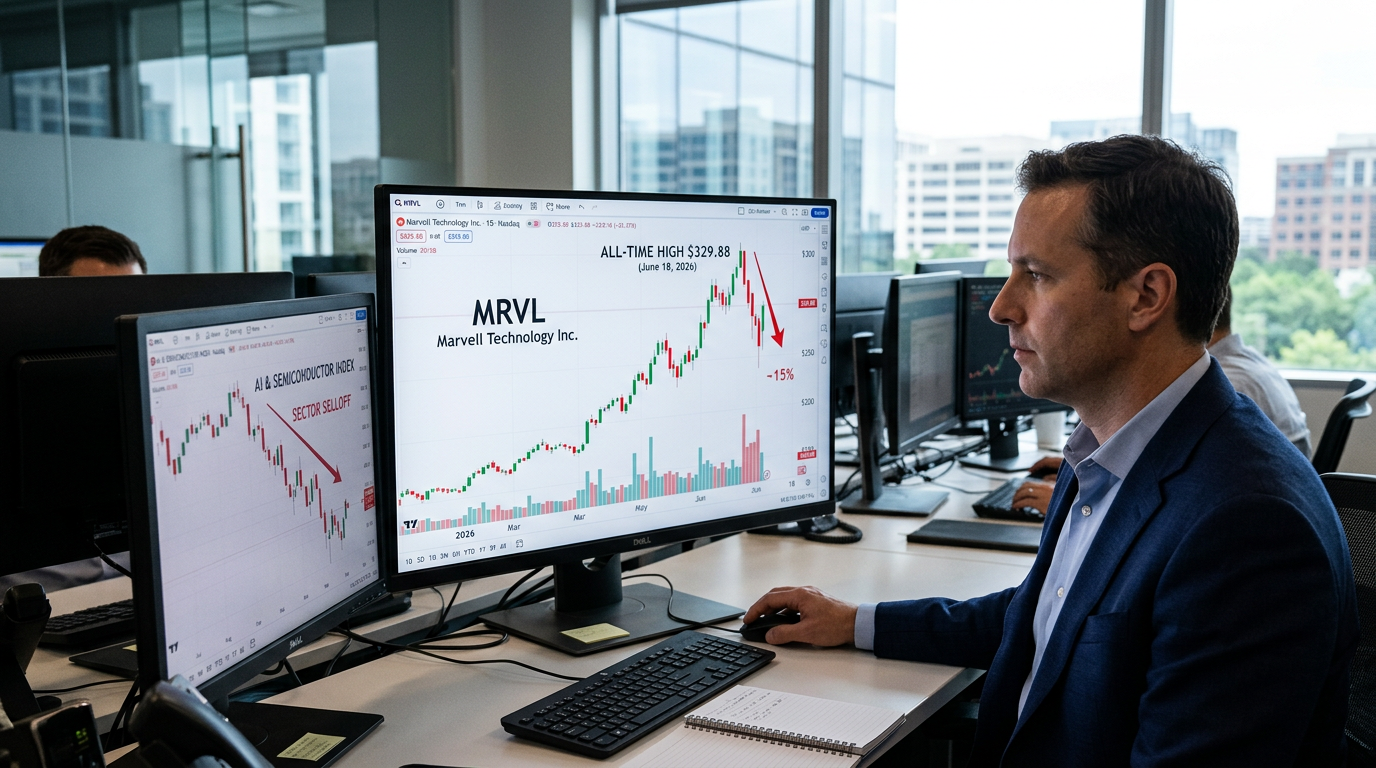
Here’s the thing about a stock that goes up 247% in a year: eventually the crowd gets nervous. Marvell shares have returned 247.4% year to date, hitting an all-time high of $329.88 on June 18, 2026 — then gave back more than 15% in less than a week, dragged lower by a sector-wide AI chip selloff that had nothing to do with Marvell’s actual business.
The selloff is real. The reasoning behind it is mostly noise.
Let’s go back to June 2. Nvidia CEO Jensen Huang appeared on stage at Computex 2026 in Taiwan with Marvell Technology CEO Matt Murphy and stated that it would be the “next trillion-dollar company,” sparking a feeding frenzy that sent MRVL shares surging 32.52% that day, adding over $70 billion to the company’s market capitalization. That wasn’t a throwaway comment. Huang highlighted Marvell’s networking and connectivity chips as essential to data centers where computing tasks are spread across thousands of connected chips that need to share data quickly. When compute disaggregates across massive clusters, data movement becomes the bottleneck. Marvell owns that bottleneck.
Marvell experienced significant intraday volatility and a downward trend on its first official day of trading as a member of the S&P 500. While inclusion in the benchmark index typically serves as a long-term catalyst due to forced buying from passive funds and ETFs, the transition on June 22, 2026 triggered a classic sell-the-news reaction, as institutional and momentum traders had aggressively front-run the index rebalancing in the weeks prior.
None of that changes the math.
The Numbers Behind the Thesis
Marvell posted record revenue of $8.195 billion in fiscal 2026 — a 42% year-over-year increase driven by data center growth that has now made AI the company’s dominant segment. In the first quarter of fiscal 2027, revenue hit another record at $2.418 billion, with record operating cash flow. The company guided Q2 fiscal 2027 revenue of $2.7 billion, representing 35% year-over-year growth, and raised its revenue outlook for both fiscal 2027 and fiscal 2028.
Marvell is transitioning into an AI connectivity leader, driven by interconnect growth exceeding 70% in FY2027. FY2027 revenue is expected at $11.5 billion, accelerating toward $16.7 billion in FY2028 with strong multi-year demand visibility. From fiscal 2026 to fiscal 2029, analysts expect revenue and adjusted EBITDA to grow at CAGRs of 41% and 43%, respectively, as the AI market expands. That’s not a speculative story. That’s a business in the middle of a structural demand surge.
What Marvell actually makes matters here. Marvell is emerging as a key enabler in AI infrastructure ecosystems, providing the high-speed networking, connectivity, and custom silicon that power AI clusters at scale. While Nvidia and AMD dominate the visible GPU layer, the broader AI chip stack requires seamless data movement across these accelerators — an area where Marvell’s specialized semiconductor designs carry critical advantages. The company raised its fiscal 2027 and 2028 revenue outlooks and expanded a $2 billion collaboration with Nvidia on custom XPUs and optical interconnects.
In late May, Marvell announced the industry’s first 102.4 terabits-per-second switch built for AI and cloud data center infrastructure. Emerging opportunities in photonics, scale-up optics, and switching remain underappreciated and largely excluded from current forecasts.
What the Selloff Is Actually About
The Philadelphia Semiconductor Index dropped 10.3% in a single session on June 5 — its worst day since March 2020 — wiping out more than $1.3 trillion in market value across the sector. Broadcom missed its AI revenue whisper number by roughly $1.2 billion. A stronger-than-expected jobs report killed hopes for a rate cut. Two data points, and suddenly a sector that had run 75% year to date looked fragile.
Slight tangent, but it matters: MRVL has been trading like a high-speed rollercoaster. Over the last few weeks, Marvell Technology ripped from around $196 on May 22 to above $300 by mid-June — a huge move for a large-cap chip name. That’s the environment it’s trading in right now, not a fundamental deterioration story.
The most likely driver of the recent decline appears to be a broad selloff in AI-linked and optical communications chip stocks rather than a company-specific operational setback, compounded by investors taking profits after Marvell’s sharp AI-fueled run higher. Broader chip weakness has been tied to worries about stretched AI valuations and the possibility of higher-for-longer U.S. borrowing costs, which can pressure richly valued growth stocks.
Institutional positioning remains constructive. We have seen 802 institutional investors add shares of MRVL to their portfolio and 752 decrease their positions in their most recent quarter. Boston Partners added over 6 million shares in Q1 2026, FMR added 4.4 million shares, and BlackRock added over 4 million shares. The CFO transition attracted attention but pre-planned sales following a 300% run are not unusual and don’t signal a fundamental view change.
The Valuation Question
The honest part: Marvell is not cheap. Following its rapid year-to-date rally, the stock is trading at an extreme trailing P/E of 99x and a forward P/E near 70x to 76x. To reach a $1 trillion market cap, MRVL shares would need to climb above $1,100 per share. But the framework for getting there is credible. If Marvell matches analysts’ estimates through fiscal 2028, grows its adjusted EBITDA at a 30% CAGR through 2036, and trades at 30x its current year’s adjusted EBITDA by the final year, its stock could rise more than eightfold over the next ten years. That rally would drive Marvell’s valuation above $2.3 trillion, easily surpassing Huang’s “trillion-dollar” outlook.
The risks are real. Marvell faces extreme revenue concentration, with its top ten customers accounting for roughly 80% of total revenue. Analysts warn that while current momentum is heavily tied to co-developing Amazon’s Trainium AI chips, there is a persistent long-term threat of hyperscalers shifting future custom chip designs to rival semiconductor manufacturers.
The Structured Trade Framework
Implied volatility in MRVL remains elevated following the sector-wide selloff, creating a high-premium options environment. The spread between realized and implied volatility has widened, which historically creates conditions where defined-risk structures offer better risk-adjusted exposure than outright long positions. For traders who believe the AI connectivity thesis is intact, a defined-risk long structure using longer-dated calls captures a recovery toward the $280-$310 range without the full exposure to continued sector volatility.
Bull case: AI cluster scale-out continues, Marvell’s optical and networking products capture an expanding share of hyperscaler spend, and the market rerates toward long-term growth potential as revenues compound at 40%+ annually. Bear case: hyperscalers internalize more custom silicon development, the AI spending cycle decelerates, and a 70x forward multiple compresses toward the sector norm of 35x. Neutral case: the stock consolidates in the $240-$280 range while the business continues to execute, offering a better entry point ahead of the next earnings catalyst in August.
What keeps coming back is this: Marvell’s business underneath the selloff really didn’t change at all. The stock and the fundamentals are not in the same conversation right now. That gap is exactly where the most interesting questions live.