October 12, 2026
Bonus Content: Salt Is Cheaper Than Lithium. The Midwest Grid Just Found Out.
Dear Fellow Investor,
When Elon Musk transforms an industry, his own companies aren’t the only ones that strike it rich.
The suppliers around him get rich too.
- ON Semiconductor makes the camera sensors and power chips inside every Tesla, and it ran as high as 1,550%.
- Planet Labs launches its satellites on SpaceX, and it soared as high as 3,000%.
- AST SpaceMobile rides SpaceX rockets to orbit, and it exploded as high as 6,695%.
Just $5,000 in each of those four stocks could have grown to more than $650,000.
And now Elon is about to do it again.
After disrupting payments… cars… and even the space industry…
This time he’s creating a new venture that dwarfs Tesla and SpaceX combined.
And former Wall Street CEO Dylan Jovine has found the one AI firm Elon needs to pull it off.
Elon has been quietly relying on this firm since 2012.
Dylan calls it “Elon’s 100X AI Stock.”
And he says a major catalyst could send this stock soaring on October 24.
Click here for the full story >>
The Buck Stops Here,
Kelly Maguire
Behind the Markets
Salt Is Cheaper Than Lithium. The Midwest Grid Just Found Out.
The most consequential battery decision being made on the American grid right now involves no lithium at all. It involves salt.
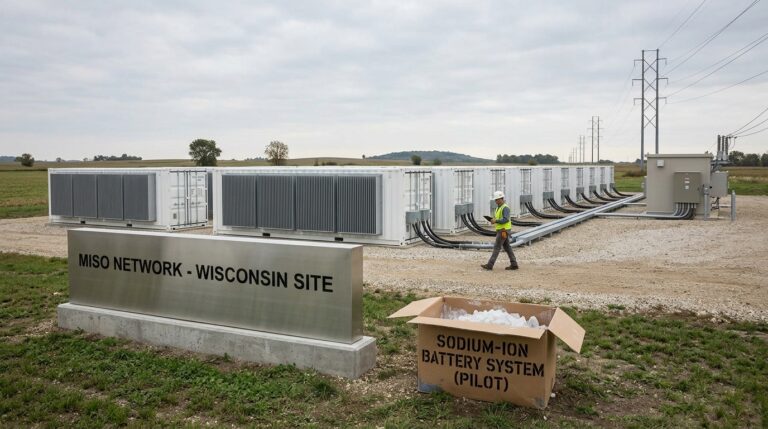
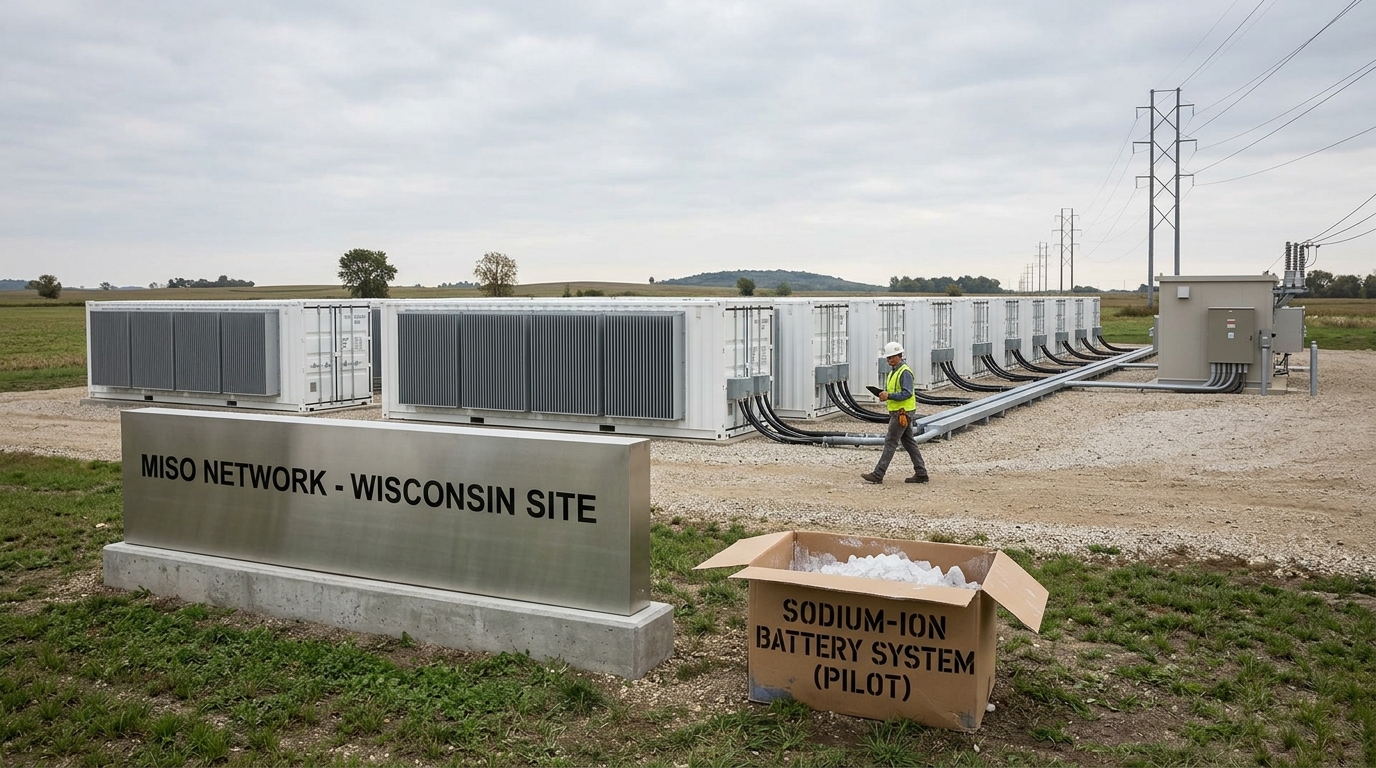
Peak Energy and RWE Americas are piloting a passively cooled sodium-ion battery system in eastern Wisconsin, the first sodium-ion deployment on the Midcontinent Independent System Operator (MISO) network. That is a modest sentence for a large shift. MISO covers 15 states and the Canadian province of Manitoba. When its operators start testing an alternative to lithium, the technology has crossed a threshold that press releases about laboratory cycles cannot.
The Bull Case: A Better Cost Structure, Baked In
The case for sodium-ion at the grid level is not primarily about chemistry. It is about procurement risk. Lithium carbonate prices swung violently through the mid-2020s, and supply chains run through a narrow corridor of Chilean brine fields and Chinese processing capacity. Sodium comes from salt, and salt is everywhere.
Peak Energy says its passively cooled system reduces the cost of energy storage by about 20% versus lithium-ion alternatives. That figure comes partly from removing active cooling entirely. Unlike conventional lithium-ion systems, sodium-ion technology can operate across a wider temperature range without requiring active cooling systems, which typically consume additional energy and add to maintenance costs. In a Midwest winter, that is not a minor detail.
Sodium-ion chemistries are generally described as more thermally stable than conventional lithium-ion approaches, potentially reducing the risk of thermal runaway and lowering fire-related permitting friction. For municipal operators managing storage near population centers, that safety profile can change the permitting conversation entirely.
CATL’s TENER Sodium platform is rated for 15,000 cycles and a 25-to-30-year service life, with the pitch being that sodium-ion’s longevity, not its energy density, is what wins grid storage. Thirty-year asset life simplifies municipal bond math considerably.
The Bear Case: Scale Has Not Caught Up to the Story
The bears have real data on their side. A September 2026 Chinese tender cited in industry analysis showed sodium-ion systems averaging 1.0322 RMB per Wh versus 0.5318 RMB per Wh for LFP, which is roughly double the price at current production volumes. Track record takes years to accumulate.
There is also the cell supply question. Peak says its Sacramento factory is expected to begin production and ship systems in Q1 2027, but the site is positioned as a manufacturing and assembly operation for containerized storage systems rather than a fully domestic, end-to-end sodium-ion cell supply chain. A domestic sodium-ion supply chain does not yet exist in full. The factory opening in Sacramento in Q1 2027 assembles; it does not yet smelt.
Where the Evidence Leads
A 2025 Aurora Energy Research study prepared for the American Clean Power Association found that adding about 11 GW of batteries across MISO between 2025 and 2035 could save around $27 billion in system costs by 2035. That arithmetic changes the procurement calculus for every regional operator watching Wisconsin.
Peak has said it has secured more than 6 GWh of customer commitments, including a deal with Jupiter Power for up to 4.75 GWh through 2030 that it said could exceed $500 million in value. Commitments at that size are not bets on laboratory results. They are bets on a supply chain that still needs to prove it can deliver at cost.
The bull case is structurally sound. The bear case is operationally valid. The honest verdict is that sodium-ion has cleared the hardest hurdle, which is convincing real grid operators to put real units in real grids. Whether unit economics follow at scale is the question that the next 18 months of Sacramento shipments will actually answer.