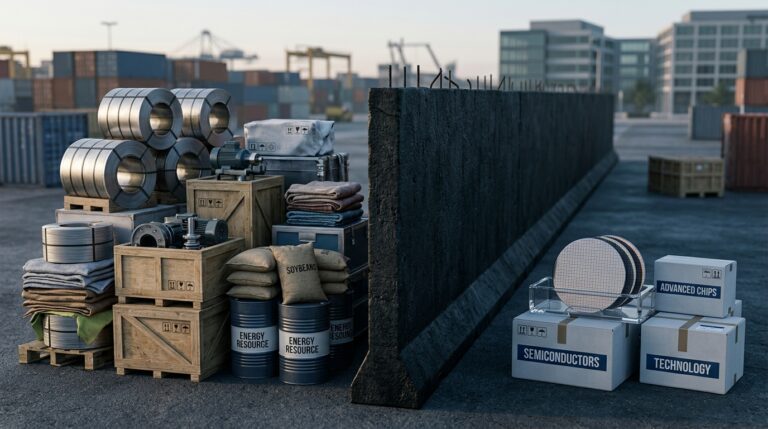
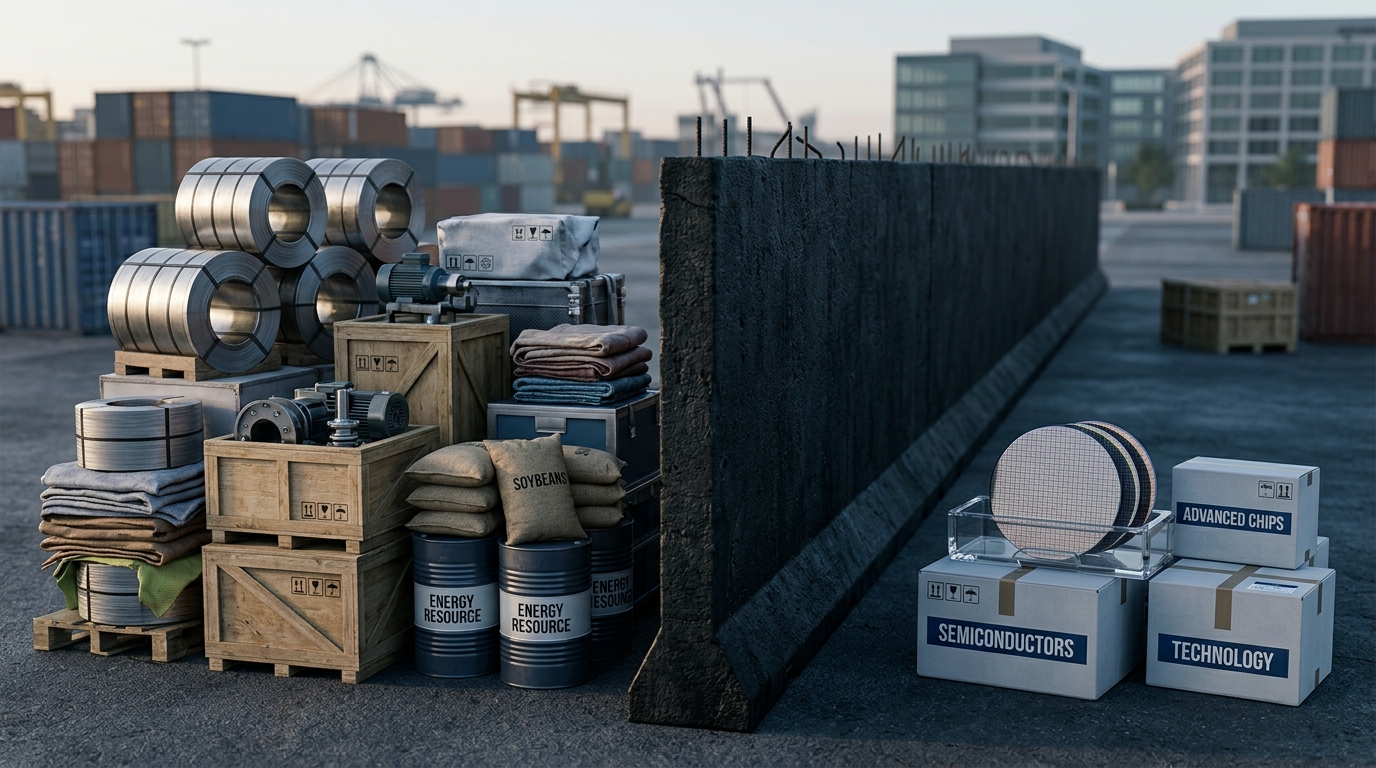
Six days before Xi Jinping is due at the White House, the two sides are closer to a deal on paper than at any point this year. Negotiators are striving to implement reciprocal tariff reductions on $30 billion of goods “at an early date,” China’s Commerce Ministry said. Treasury Secretary Scott Bessent said he will meet this weekend with his Chinese counterpart, He Lifeng, ahead of the Sept. 24 summit. The shape of the package is becoming clear: US energy and agricultural shipments are at the center, and the White House says Beijing has committed to buy at least $17 billion of US agricultural products each year on top of soybean purchases. Some Chinese goods could receive most-favored-nation tariff rates, according to people familiar with the private discussions.
The Bull Case
The optimists have a credible argument. The November 10 deadline is real: a research note from Barclays points out that the temporary tariff truce is scheduled to expire on November 10, making the Sept. 24 summit not just symbolic but structurally necessary. Failure to produce deliverables risks reigniting the escalation cycle that pushed tariffs toward triple digits earlier in the cycle.
The agriculture numbers are not trivial. China committed to purchase at least 25 million metric tons of US soybeans in each of 2026, 2027, and 2028 under the late-2025 framework, and any Sept. 24 announcement that locks in that buying across energy categories extends a demand floor that US farm states and LNG exporters will notice. US Trade Representative Jamieson Greer said he expected announcements on agriculture and related non-tariff barriers during Xi’s visit. FXI, the iShares China Large-Cap ETF that tracks the 50 largest Hong Kong-listed Chinese stocks, is down about 7% year-to-date and trades at a forward multiple below 12, leaving room for a sentiment-driven re-rating if a credible deal lands. Bulls argue that goods-level tariff relief, even if targeted, lowers input costs for Chinese manufacturers that supply US importers, compressing the inflation pass-through that has weighed on both consumer spending and Fed optionality.
The Bear Case
The bear case is simpler and, on the evidence, harder to dismiss: the technology conflict has not been paused, it has been institutionalized. In March 2025, the Trump administration added dozens of Chinese entities to export restrictions, widening the semiconductor and advanced-computing choke points. The regime has kept tightening at the edges even as headline tariffs softened. In June 2026, the Department of Commerce revised its licensing policy for semiconductor exports to China, even as it reiterated that licensing can follow the ultimate-parent rule, applying scrutiny to exports to entities located outside China if their ultimate parent is headquartered in China.
Congressional pressure runs in one direction only. In February 2026, a bipartisan group of lawmakers sent a letter to Commerce Secretary Howard Lutnick urging stronger export controls on chipmaking tools and closer coordination with allies. The executive branch has shown it can hold a softer line on chip licensing when trade talks are live, but the uproar from congressional hawks has been fierce. Any White House move to formally relax advanced chip controls as part of a Sept. 24 package would face immediate legislative resistance.
And the underlying technology gap is closing regardless. Policy blind spots and inconsistent implementation have left loopholes that China has exploited to accelerate its drive to dominate key industries, and multiple analyses now project China could overtake Taiwan in foundational, mature-node chip production share by 2027. Tariff relief on soybeans does nothing to alter that trajectory.
Where the Evidence Leads
The $30 billion figure covers roughly a month of bilateral goods trade. It is a confidence-building measure, not a structural reset. A tariff deal could test whether the Board of Trade discussed after Trump’s May 2026 meetings with Xi can produce results, and would give both governments a way to keep the broader relationship on track while disputes over technology and national security continue. That framing is instructive: both sides are explicitly designing the goods deal to coexist with the tech conflict, not to resolve it.
For FXI holders, a Sept. 24 announcement likely delivers a short-term bounce, particularly in consumer and energy-linked holdings. The fund’s financial-services and consumer cyclical sectors together account for more than 60% of its weight and are the primary beneficiaries of tariff normalization on manufactured inputs. But the export-control architecture limits how far any re-rating can run. Several major disputes remain, particularly over semiconductors and rare earths, and each party retains leverage that could reignite trade hostilities.
Final Verdict
The bull case wins the near term. A signed deliverable on Sept. 24 almost certainly lifts China-exposed equities and compresses volatility in agricultural commodity spreads. The bear case wins the medium term. A $30 billion tariff package negotiated against a November truce deadline is a holding pattern, not a reopening. Investors positioned in FXI for a durable China trade recovery should treat any summit rally as an opportunity to reassess exposure rather than add to it. The chip controls are not on the table at the White House dinner, and until they are, the ceiling on this trade stays low.