August 27, 2026
Bonus Content: Russia Is Still Flowing. The Real Test Starts Jan. 1.
Hi,
Take a look at this…
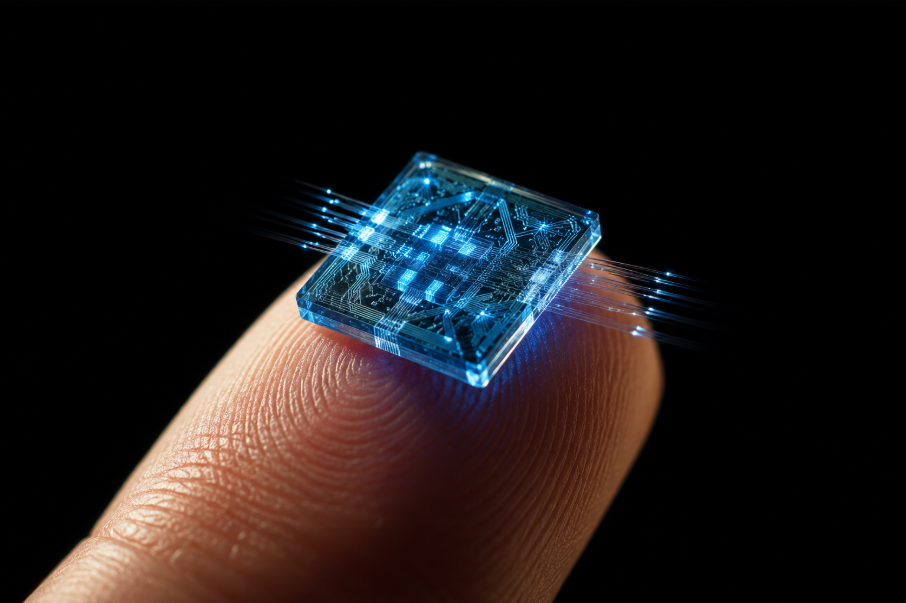
It’s smaller than a fingertip…
It’s made of glass…
And it’s about to unlock the next wave of AI growth.
Jensen Huang, Nvidia’s CEO, says this “light-speed” device is shattering the limitations of AI… and without it, AI can’t scale.
Google Ventures says it’s the future of AI compute…
And Sequoia Capital – the firm that backed Anthropic and OpenAI – calls it a “holy grail.”
Already, Elon Musk, Mark Zuckerberg, Cathie Wood, and Bill Gates are moving money to prepare for what’s coming…
Yet most Americans have never heard of it.
Wall Street insider Jason Bodner – the same man who called Nvidia at $4.50 – says this device is about to launch a whole new wave of AI winners…
And to prove it, he’s giving away his #1 stock involved with it – for free.
Click here to learn more. (No purchase necessary.)
We have so much to look forward to,
Jeff Brown
Founder & CEO, Brownstone Research
P.S. Stocks tied to this “light-speed” device already surged 133%, 217%, and even 320% – in a few short months. But it’s just getting started. Click here before the mainstream catches on.
Russia Is Still Flowing. The Real Test Starts Jan. 1.
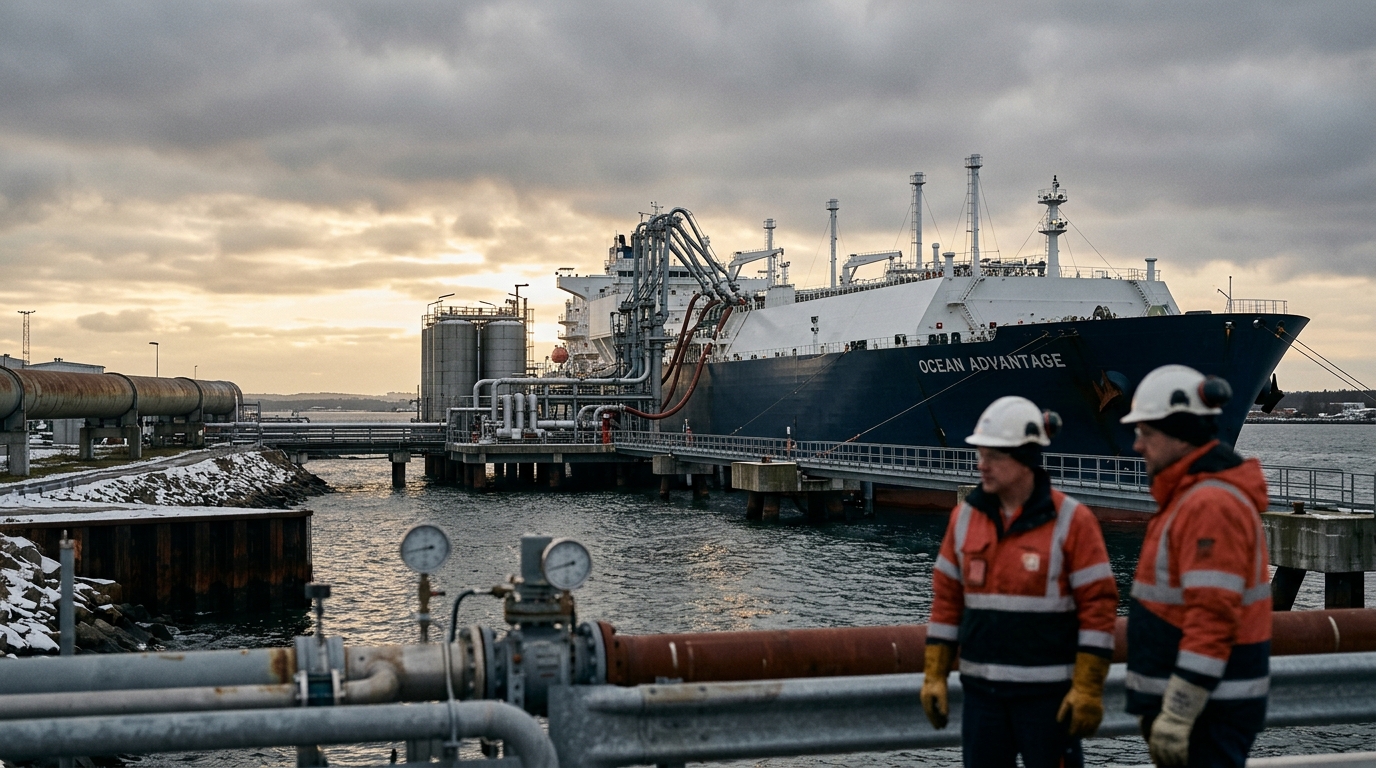
The bull case for US LNG writes itself right now. Dutch TTF futures have climbed roughly 120% since the start of 2026, reaching about €63.7 per megawatt-hour on August 18. European gas storage facilities were about 60.8% full as of August 17, compared with about 73.6% a year earlier. The EU’s binding 80%-by-November 1 target is still roughly 19 points away, and the window for injection rates to accelerate is narrowing fast, with European seasonal demand typically beginning to pick up from late September.
The Bull Case
The structural argument rests on a hard regulatory cliff. On January 26, EU countries formally adopted Regulation (EU) 2026/261, a gradual but permanent ban on Russian natural gas imports, turning the REPowerEU roadmap into EU law. A full ban will take effect for LNG imports from the beginning of 2027 and for pipeline gas imports from autumn 2027. That is not a suggestion. It is statute.
The replacement math favors US exporters. If the EU fulfills all existing supply agreements for US LNG and demand reduction efforts falter, the bloc could obtain as much as 75 to 80% of its LNG imports from the United States by 2030, up from about 57% of total LNG imports in 2025. Capacity to meet that demand is coming. US LNG exports rose from 0.5 billion cubic feet per day in 2016 to about 15.1 billion cubic feet per day in 2025, and the EIA’s outlook has projected exports around the high-18 billion cubic feet per day range in 2027. Cheniere (CQP), Williams (WMB), Kinder Morgan (KMI), and Energy Transfer (ET) all have exposure to a demand signal that, on paper, is legally guaranteed.
Record temperatures are pushing up electricity demand while drought and heat are curbing hydro and, in some places, nuclear generation, forcing gas-fired power stations to fill part of the gap just as Europe should be putting more gas into storage. Every megawatt-hour diverted to power generation is one less injected before the heating season. That tightness is structural, not seasonal.
The Bear Case
Here is the problem: the ban was supposed to already be working, and it is not. EU imports of Russian LNG climbed about 16% year-on-year to roughly 9.97 million tonnes during January through June, according to Kpler data.
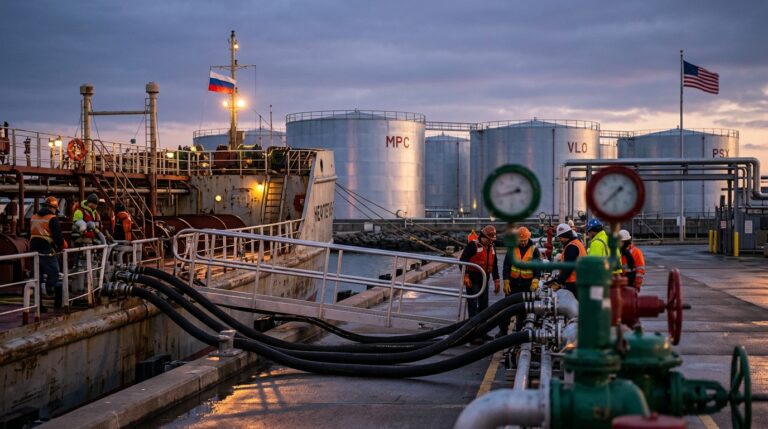
The mechanism is straightforward. The increase was supported by Yamal’s established European contract network, which remains exempt from the import ban for long-term contracts until January 1, 2027. Russian LNG accounted for roughly one-fifth of the EU’s total LNG imports in the first half of the year. That is the supply the January 1 ban must actually replace, not a theoretical volume.
The growth in US volumes has also been redirected elsewhere. US cargoes are globally fungible, and in months when Asia pays up, marginal US volumes can flow east rather than into Europe. There is no guarantee European buyers recapture those cargoes simply because Brussels passes a law.
Cost is a legitimate friction. American LNG can be among the more expensive options for European buyers on a delivered basis, and at TTF near €63/MWh the arbitrage looks comfortable today. Whether it still looks comfortable after a wave of new capacity lands and Henry Hub prices adjust is the question investors underwriting long-dated FIDs are actually answering.
Where the Evidence Leads
The regulatory floor is real. January 1, 2027 is a binary event for long-term Russian LNG contract volumes, not a gradual fade. Almost all of the roughly 9.97 million tonnes of Russian LNG delivered to the EU in the first half originated from the Yamal terminal, with the largest destinations including France, Belgium and Spain. Those volumes have to go somewhere else, or be replaced. That is a genuine structural bid for alternative supply, and US exporters are the primary alternative at scale.
The bear pushback worth taking seriously is not that the ban will fail. It is that the market has already priced the ban. TTF at 120% above its January opening is not an unloved trade. New US capacity entering service through 2027 may arrive precisely when the Russian supply gap is being absorbed, compressing the arbitrage that justifies the current FID wave. Shell (SHEL) and ExxonMobil (XOM) carry diversified upstream exposure across both sides of this equation.
What Could Change the Debate
Two variables dominate the next 90 days. First, the injection pace: EU storage was about 60.8% as of August 15, and the current injection pace has been roughly in the neighborhood of what is required to hit the 80% target by November 1. Any disruption to that pace, Norwegian maintenance, a hot September, a Hormuz flare-up, tips the balance hard toward the bulls. Second, watch sanctions implementation details around Russian LNG logistics. EU governments have already moved on additional restrictions tied to LNG shipping and related transactions, and further tightening would reduce Russia’s ability to redirect Yamal cargoes elsewhere.
Final Verdict
The bull case is better supported today, but only modestly. The January 1 ban is law, the storage deficit is real, and US capacity is expanding. What keeps this from being a one-sided call is that the EU has been buying record volumes of Russian LNG all year while the clock ticks, and futures markets are not asleep. The trade for LNG infrastructure names is less about whether demand arrives and more about at what price, and for how long. Position sizing, not conviction, is the active question.