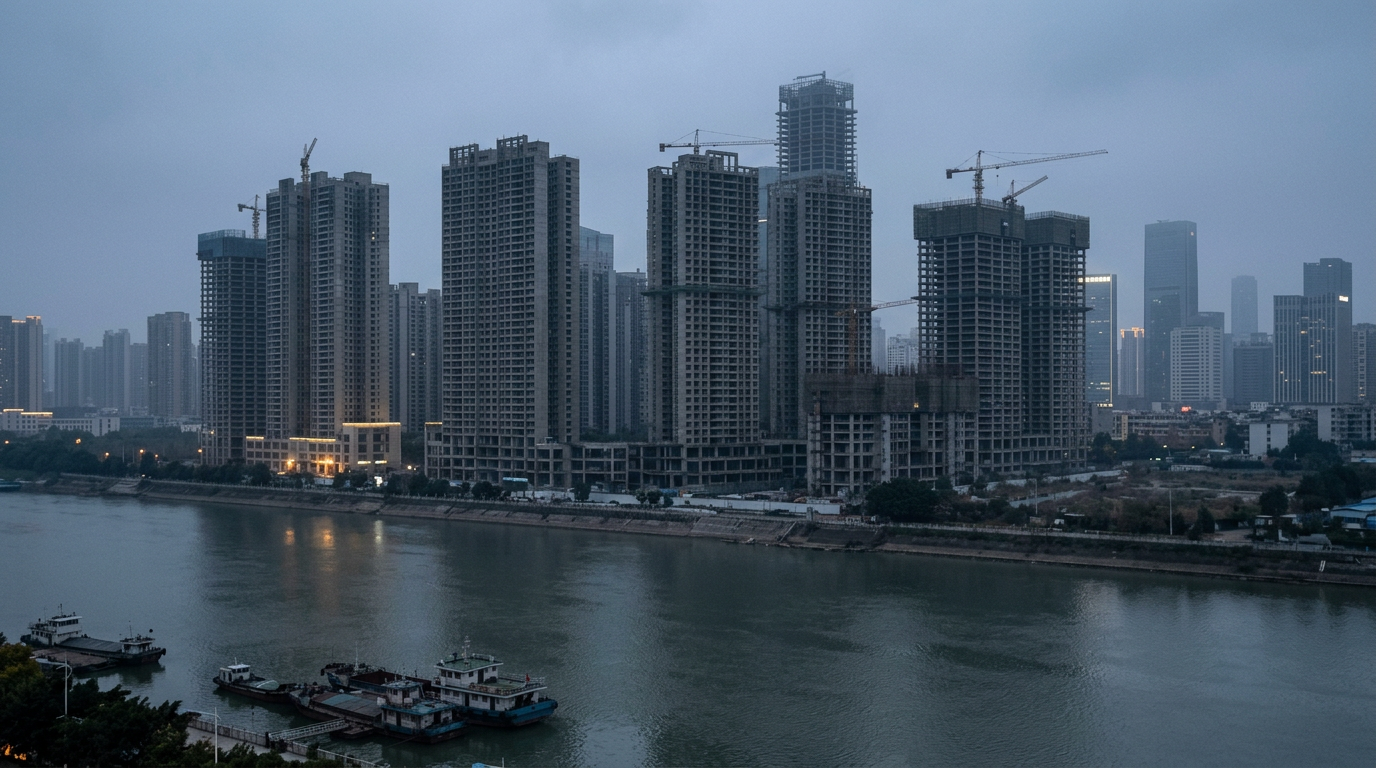
The framing keeps shifting, but the numbers don’t. China’s housing market — once valued at roughly $60 trillion at its peak — has shed an estimated 85% of the gains built between 2011 and 2021, according to research cited by The Economist. Primary home sales are forecast to fall another 10% to 14% in 2026. Inventory is estimated to be 45% above pre-downturn averages. New home prices in 70 major cities were down 3.5% from a year earlier as of May. And the policy response from Beijing remains, in the words of multiple analysts, “support, not stimulus.”
This is not a housing story anymore. It is a global macro story that most Western portfolios have not finished pricing.
The Wealth Effect Nobody Is Talking About
Start here: Chinese households allocate roughly 70% of their wealth to property. That is not a misprint. In a country where private property didn’t exist as a concept until the late 20th century, real estate became the dominant savings vehicle for hundreds of millions of households. When housing prices fall — and they have been falling for five years — households feel poorer. They save more. They spend less.
That dynamic is showing up in the data. China’s CPI inflation dropped to essentially zero in 2025 and was running at just 1.2% as of April 2026. The IMF expects deflationary pressure to persist. Outstanding housing loans fell by 1.8% in 2025 and continued declining into Q1 2026. The consumer is not spending their way out of this.
Goldman Sachs estimated the property downturn reduced China’s annual GDP growth by about 2 percentage points in 2024 and 2025. That drag is expected to narrow — but it has not disappeared. Fixed-asset investment fell 4.1% in the first five months of 2026. These are not numbers that describe a market transitioning smoothly to a new equilibrium.
The Global Commodity Connection
Here is the second-order trade that is genuinely underappreciated: China’s property sector is one of the largest demand drivers for steel, cement, copper, and aluminum on the planet. When construction starts collapse — and they fell nearly 30% in January through February — the demand destruction flows directly into global commodity markets.
This matters for how you read the copper trade, the steel trade, and any commodity play that has China construction as a core demand assumption. The consensus view is that AI-driven copper demand and the energy transition offset the China housing drag. That may be true in aggregate over a decade. It is not necessarily true in the next 12 months, when the China real estate supply glut is still being absorbed and developer financing remains constrained.
Analysts surveyed by Reuters expect national home prices to fall another 4% in 2026 before stabilizing in 2027. S&P Global Ratings projects secondary home prices falling 4% to 5% this year. That is not a bottom signal. It is a continued drag signal.
What the Market Is Missing
The consensus interpretation of the China property situation is roughly: yes, it is bad, but the government will manage it and it won’t become systemic. That is probably right on the systemic banking crisis question — China’s mortgage practices were conservative relative to U.S. 2008 standards, and the state has the tools to prevent a Lehman-style cascade.
But that framing misses the slow-burn problem. This is a wealth effect story, a deflation story, and a local government finance story all at once. Local governments in China relied heavily on land sales for revenue. When developer demand for land collapsed, that revenue collapsed with it. Beijing has had to step in to fill fiscal gaps at the local level. That is not a one-year fix.
The parallel that haunts the analysis is Japan in the 1990s. Japan’s real estate bust did not produce a banking crisis either — the state backed the banks. But it produced two decades of economic stagnation driven by balance sheet repair, weak consumer confidence, and persistent deflation. Kenneth Rogoff and others have drawn explicit comparisons between China’s current situation and Japan’s post-bubble experience. The differences are real. The similarities are uncomfortable.
Where the Opportunity Sits
Tier 1 cities — Shanghai, Beijing, Shenzhen — are showing relative resilience. Commercial logistics assets are attracting selective institutional interest. And the companies benefiting from China’s deliberate pivot toward technology, high-end manufacturing, and domestic consumption are not the same as the companies that benefited from the construction boom.
The AI cycle is providing a genuine offset — China’s manufacturing and tech sectors are generating real activity even as construction contracts. But the consumer story, the commodity demand story, and the local government fiscal story all have further to run. Anyone building a bullish China thesis in 2026 needs to be specific about which China they are betting on. The construction China and the AI-manufacturing China are two very different economies right now.
The property reset is not over. The global implications of that reset are still being absorbed. That gap between what is happening and what most Western portfolios are pricing is where the real risk — and the real opportunity — lives.
For informational purposes only.